


Samsara (IOT) is back in focus after the launch of Samsara for Equipment and its new 360 AI camera for operated machinery, alongside growing attention on its next earnings report.
Despite a small 1-day share price decline of 2.18% to US$41.32, Samsara has kept a positive tone over 2026 with a year-to-date share price return of 21.82% and a 3-year total shareholder return of 55.46%. This suggests momentum has been building as product launches and the upcoming earnings report shape expectations around both growth potential and risk.
Scan beyond Samsara and line up other AI and automation plays with strong operational themes using our hand-picked 85 robotics and automation stocks as a comparison set.
After a strong multi year run and fresh AI product buzz, Samsara now sits at a level where expectations feel full. Does the current price still offer a sensible risk reward balance for new money going in?
Most Popular Narrative: 100% Undervalued
The narrative fair value of $57,342.55 sits far above Samsara's last close at $41.32, which creates a sharp gap between what this view implies and where the market currently prices the stock. According to Averagemike, an investor in the Simply Wall St Community who wrote the narrative, the debate is less about near term quarterly numbers and more about how far regulation and technology could push adoption.
I can tell you right now that drivers don't want to be spyed on 24/7. Especially drivers who are in their truck all week or longer. The truck is home and with 360 views are unacceptable. Even a camera focused only on the driver would be a tough sell. Truck drivers and carriers are so over regulated already. Cameras don't move freight truck drivers do. It is better to improve the regulations they already have to deal with.
See why 3 investors see Samsara as 100% undervalued.
Result: Fair Value of $57,342.55 (UNDERVALUED)
Still, the bullish story around Samsara meets real friction if driver pushback slows camera adoption, or if tighter rules reshape how AI driven monitoring can be used.
Find out about the key risks to this Samsara narrative.
Another View: Samsara Through The P/S Lens
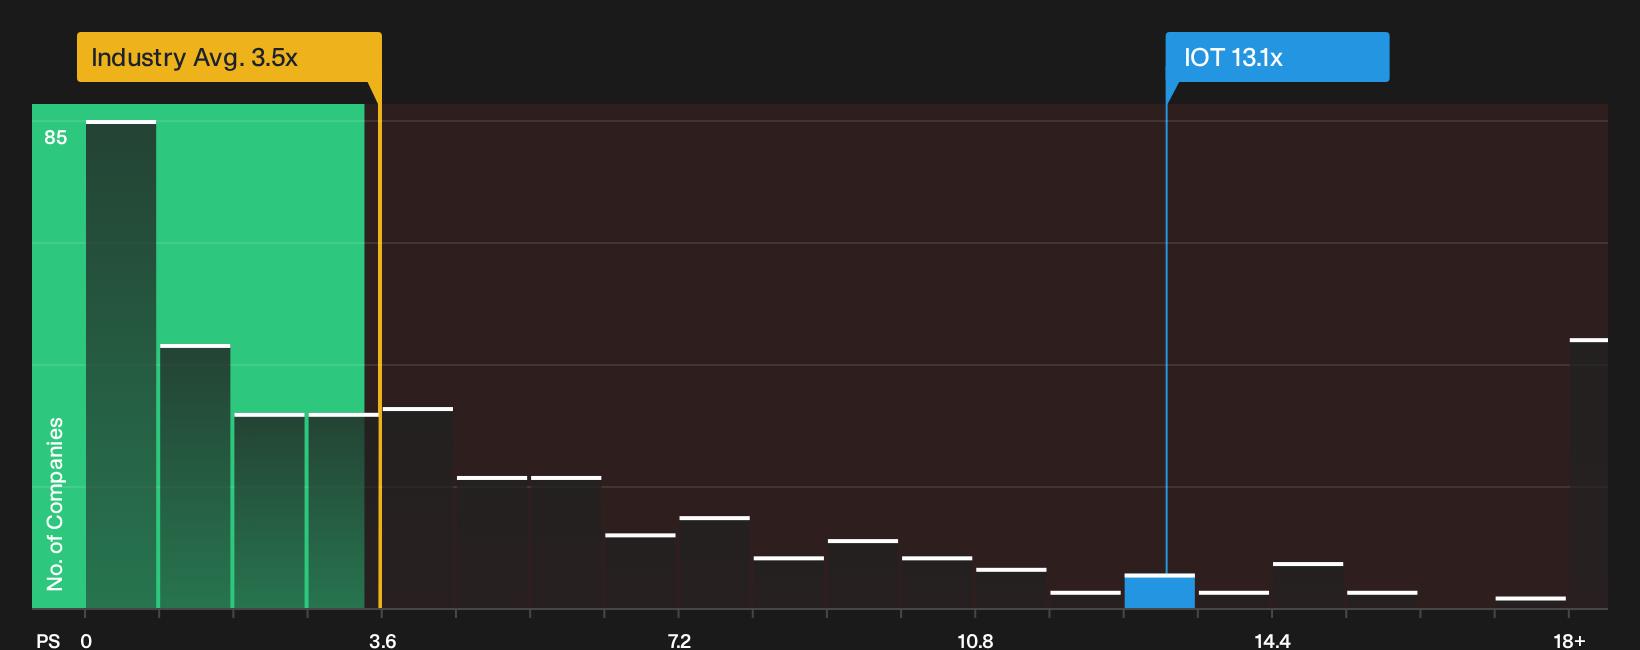
The user narrative calls Samsara 100% undervalued, yet the market is already paying a rich P/S ratio of 13.1x. The broader US Software group trades at 3.5x, while Samsara's own fair ratio is estimated at 9x. That gap points to valuation risk if expectations slip even slightly.
For a closer look at how this pricing compares with peers and the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Samsara is clearly split, with both risk flags and upside angles on the table. Move quickly, interrogate the data, and weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Samsara?
Do not stop at Samsara. Use the Simply Wall St screener to line up fresh opportunities that fit your risk tolerance, return goals, and investing style.
- Target potential mispricings by zeroing in on quality companies that screens flag as attractively priced through the 32 high quality undervalued stocks.
- Protect your capital by focusing on businesses with sturdier finances, starting with the list of solid balance sheet and fundamentals (23 results).
- Boost your income focus by reviewing companies that combine higher yields with durability through the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com