


Trupanion has seen its share price fall sharply over the past few years even as recent headlines have focused on improved profitability, which raises a straightforward question for investors who care about valuation. Is the current US$34.30 price properly anchored in what the insurer is actually earning today and may be able to earn over time?
- Over the last 5 years the stock has declined 73.9%. That puts the spotlight firmly on whether the business now justifies a very different earnings profile than investors once priced in.
- Recent profit and cash flow improvements, helped by higher subscription revenue and more insured pets, can reshape how you think about the durability and level of Trupanion’s earnings stream.
- The analysts covering Trupanion have run their own numbers. See what analysts think Trupanion's shares could be worth.
The issue now is whether Trupanion’s current market value lines up with what its earnings can realistically support.
If you are weighing Trupanion against other ideas where valuation and quality both matter, a focused stock screen is a useful next step. You can start with 32 high quality undervalued stocks
Does Trupanion Look Pricey on Earnings?
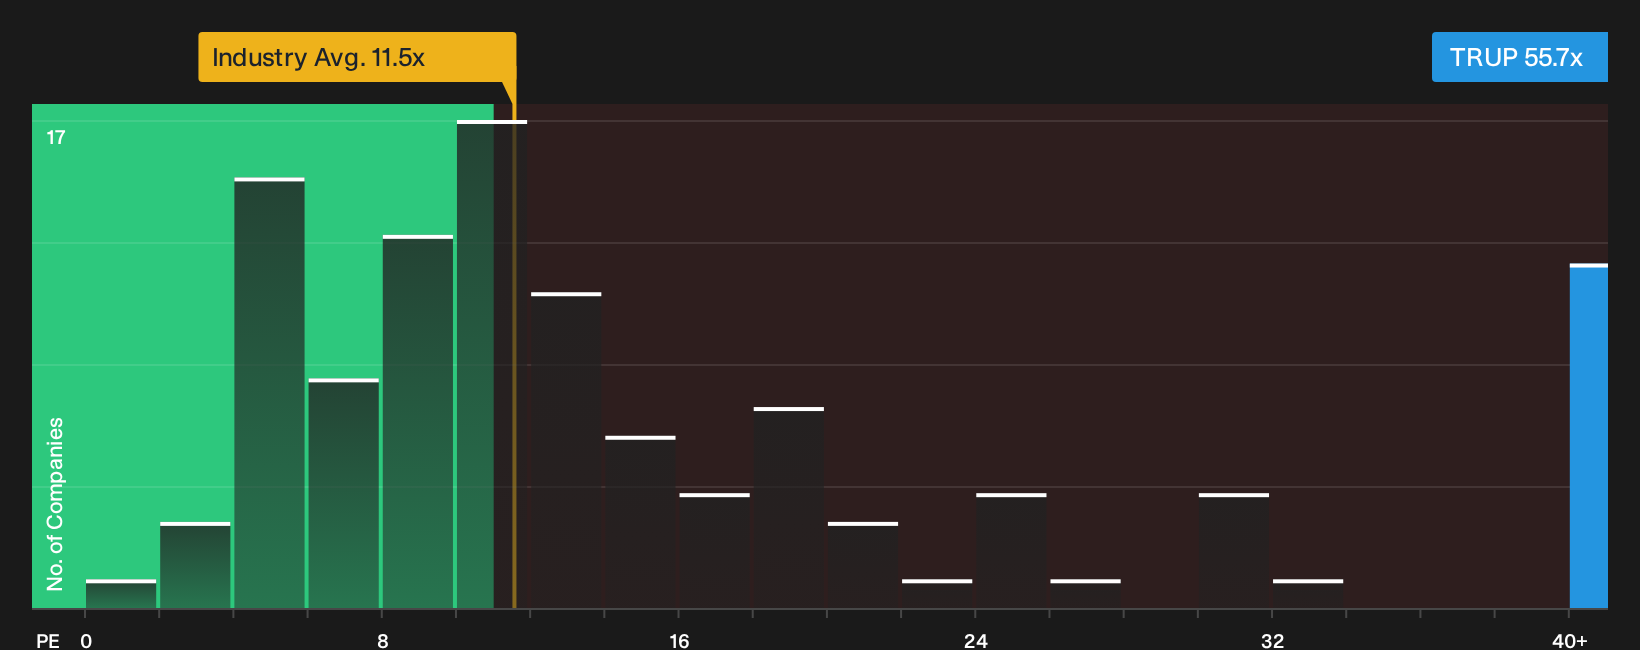
P/E fits Trupanion because earnings have recently turned positive and investors are again weighing what those profits might be worth. At roughly 55.7x, the stock trades at a much richer P/E than the broader insurance industry average of about 11.5x and a peer group near 11.9x. That is a big step up in price for each dollar of reported earnings.
The fair value model, which blends Trupanion’s growth profile, margins, size and risk, points to a materially lower P/E than the market is currently paying. Because this framework heavily penalises earlier losses and perceived risk around the quality and durability of profits, the implied fair multiple is better read as a warning flag that Trupanion screens as overvalued on earnings rather than a precise target. Despite the strong Q3 2026 report and record profitability, the present valuation already bakes in a lot of good news on this metric. Explore the numbers behind Trupanion's P/E valuation.
The Trupanion Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Trupanion valuation puzzle leaves off, by spelling out which paths for growth, margins and earnings would need to hold for the share price to end up meaningfully higher or lower than it is today. Each storyline treats its fair value as the output of specific assumptions rather than a single headline multiple, so you can line those expectations up against Trupanion's reported numbers as they come through.
Bulls and bears looking at Trupanion today are really debating how durable its improved profitability and cash generation will prove over time.
Bull case: 29% undervalued
The bullish analyst Narrative on Simply Wall St frames Trupanion as a cash generative subscription engine with more levers still to pull.
"Consistent free cash flow generation together with the ability to upstream about $130 million of excess capital and a US$100 million share repurchase authorization create headroom for Trupanion to shift its capital mix toward lower share count alongside continued reinvestment..."
Discover why this Narrative puts Trupanion at 29% undervalued.
Bear case: 7% overvalued
The bearish analyst Narrative on Simply Wall St leans on cost pressures and customer acquisition challenges to question how far Trupanion can stretch.
"While management cites higher lifetime value per pet as justification for increased marketing spend, rising average pet acquisition cost to more than US$300 per pet in recent quarters indicates that each new subscriber is becoming more expensive to win..."
Explore why this Narrative puts Trupanion at 7% overvalued.
One more Trupanion angle worth checking before you move on
Valuation only tells you what the market is paying today, while the analyst models sketch out where they think this business could reasonably land a few years from now. Explore where analysts expect Trupanion to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com