


Why Brookdale’s latest earnings matter for shareholders
Brookdale Senior Living (BKD) just reported third quarter and nine month results that shifted from a large prior loss to a small profit for the year to date, even as revenue declined.
The headline numbers tell two different stories. Quarterly sales and total revenue were lower than a year earlier, while the third quarter still showed a net loss. Over the first nine months, though, the business moved from a sizeable deficit to a modest net income, which points to meaningful cost control or operational changes behind the scenes.
For investors following Brookdale Senior Living, that mix of weaker top line and better bottom line raises a practical question: Is this early evidence of a more efficient operator, or mainly the product of one off moves that may not recur? And how does that tension square with how the stock has traded recently?
Recent trading tells a mixed story. The share price is down 11.37% over the past month and 29.11% over the past quarter, and the 1 year total shareholder return is lower by 14.09%. However, the 3 year total shareholder return of 70.67% and the 5 year figure of 34.74% point to investors who held on through volatility seeing materially different outcomes from those focused on the latest swing.
Compare Brookdale Senior Living’s shift toward profitability with other healthcare operators that pair earnings momentum with balance sheet strength by scanning our curated list of solid balance sheet and fundamentals (23 results).
Brookdale Senior Living has a share price that has retreated sharply just as its income statement has flipped from deep losses to a small profit. Is this the moment to commit fresh capital or wait for an even cheaper entry and more proof of resilience?
Most Popular Narrative: 25% Undervalued
On the latest numbers, the bearish analyst Narrative on Simply Wall St puts Brookdale Senior Living’s fair value at $12.00 per share, compared with a last close of $8.96. This frames a sizable valuation gap built on cautious long term assumptions and higher required returns.
Planned community reinvestment, including the scaling up of high ROI First Impressions projects and US$175 million to US$195 million of 2026 CapEx, aims to support higher occupancy and pricing but also keeps repair and maintenance spending elevated. Together with higher utilities, insurance, food, and bad debt, this has already compressed same community margins and could keep net margins under pressure if returns on this spend do not materialise as expected.
See why 1 investors see Brookdale Senior Living as 25% undervalued.
The valuation work behind that $12.00 figure leans on a 10.2% discount rate and a set of forecasts that already assume relatively modest revenue expansion of about 3.4% a year and a shift from a current net loss of $37.5 million to earnings of $310.5 million by 2029. Even though this view is built from the lower end of analyst price targets, it still rests on a big improvement in profit margin to 9.8%, and a future P/E multiple of 12.6x that is well below the 24.9x level currently used for the broader US Healthcare sector.
For Brookdale Senior Living shareholders, the tension is clear. The stock is trading well below both the $12.00 bearish fair value and the $16.17 consensus price target, yet analysts do not show tight agreement and the business still carries negative equity and high leverage. The result is a valuation case that suggests upside relative to the last close, but one that depends on occupancy, RevPAR, and margin targets being met over several years while balance sheet repair stays on track.
Result: Fair Value of $12.00 (UNDERVALUED)
Still, the bearish Brookdale Senior Living story can fray if adjusted EBITDA and free cash flow continue to outpace expectations, or if leverage declines more quickly than modeled.
Find out about the key risks to this Brookdale Senior Living narrative.
Another View on Brookdale’s value
The analyst fair value of $12.00 paints Brookdale Senior Living as undervalued, yet the Simply Wall St DCF model tells a cooler story. On that future cash flow view, the shares around $8.96 sit above an estimated value of about $8.24, which reads as slightly overvalued instead. Which lens do you trust when the cash flow math and analyst targets pull in opposite directions?
Look into how the SWS DCF model arrives at its fair value.
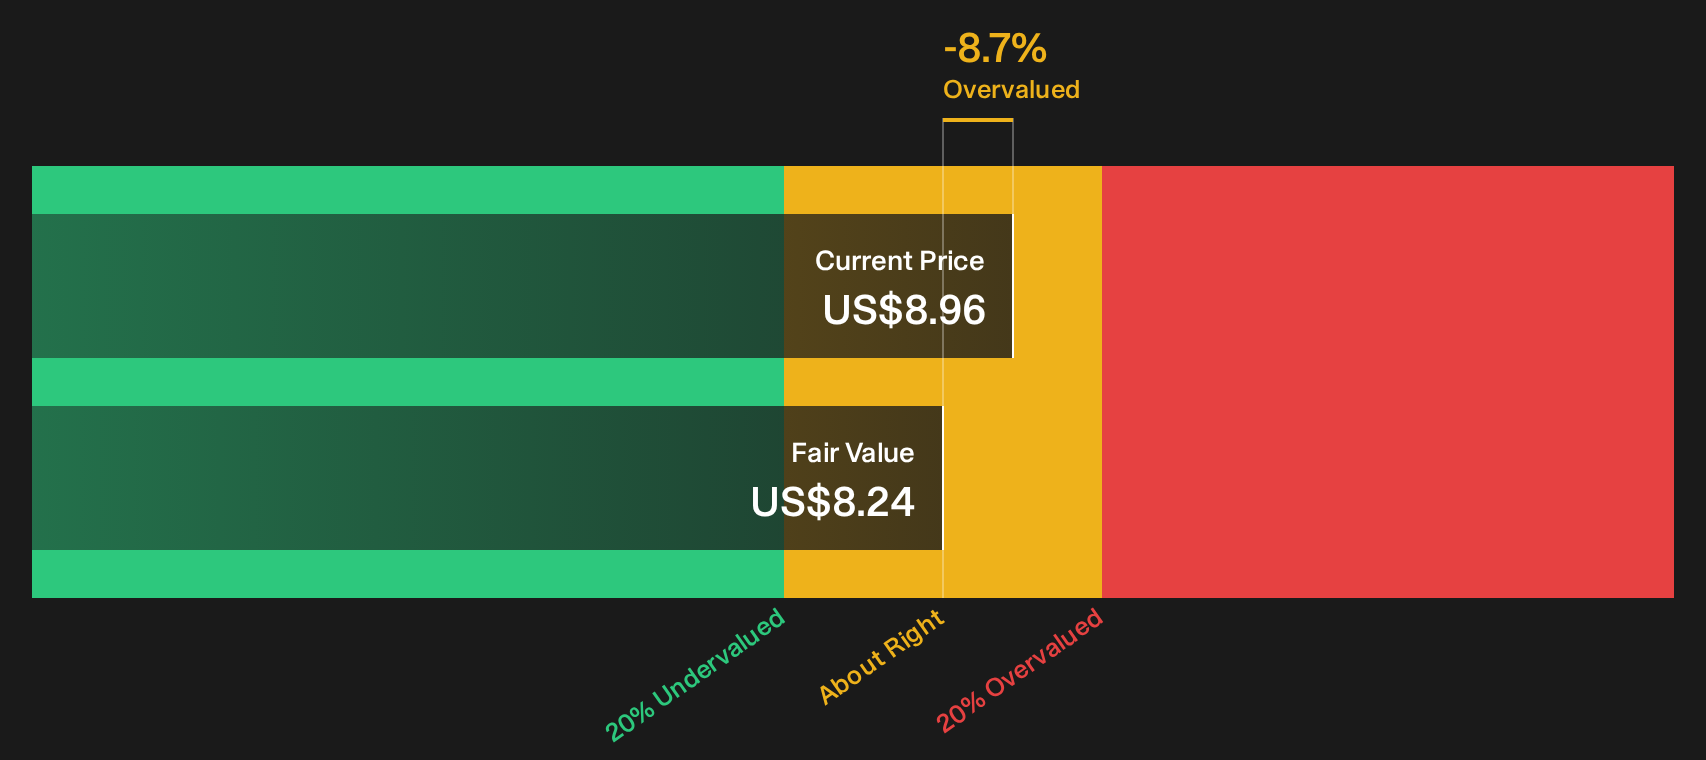
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Brookdale Senior Living for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Brookdale Senior Living’s story carries both optimism and unease, so move quickly, pull up the data, and weigh the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Brookdale Senior Living?
If Brookdale Senior Living has you rethinking your watchlist, use these focused screeners to spot other opportunities that might deserve a closer look.
- Target resilience first and sidestep fragile balance sheets by scanning a 29 resilient stocks with low risk scores that already screens for stronger financial profiles.
- Hunt for mispriced quality and let valuation work harder for you by reviewing a curated 32 high quality undervalued stocks tailored to fundamental strength.
- Spot potential early movers before broader attention arrives by combing through a 20 high quality undiscovered gems built around solid underlying businesses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com