


- Kanematsu reported half year sales of ¥571,910 million and net income of ¥24,414 million for the period ended September 30, 2026, with both figures above the prior year's levels.
- The board paired this profit performance with plans for an interim dividend and a higher year end dividend forecast, signaling an emphasis on returning cash to shareholders alongside earnings growth.
- Next, the focus is on how Kanematsu's stronger profitability and planned dividend increase might shape the broader investment narrative for investors.
Scan how Kanematsu's latest earnings and dividend plans compare with other potential opportunities by reviewing our handpicked list of 18 high quality undervalued stocks.
What Is Kanematsu's Investment Narrative?
To own Kanematsu, you have to buy into a fairly simple idea. This is a trading and solutions group that lives and dies on execution across very different lines, from electronic devices to food to steel and vehicles. The latest half year results, with ¥571,910 million in sales and ¥24,414 million in net income, suggest operations are holding up across that mix. Higher basic EPS of ¥146.71, plus the plan to lift both the interim and year end dividends, points to management using stronger profitability and equity method gains to support shareholder returns in the near term.
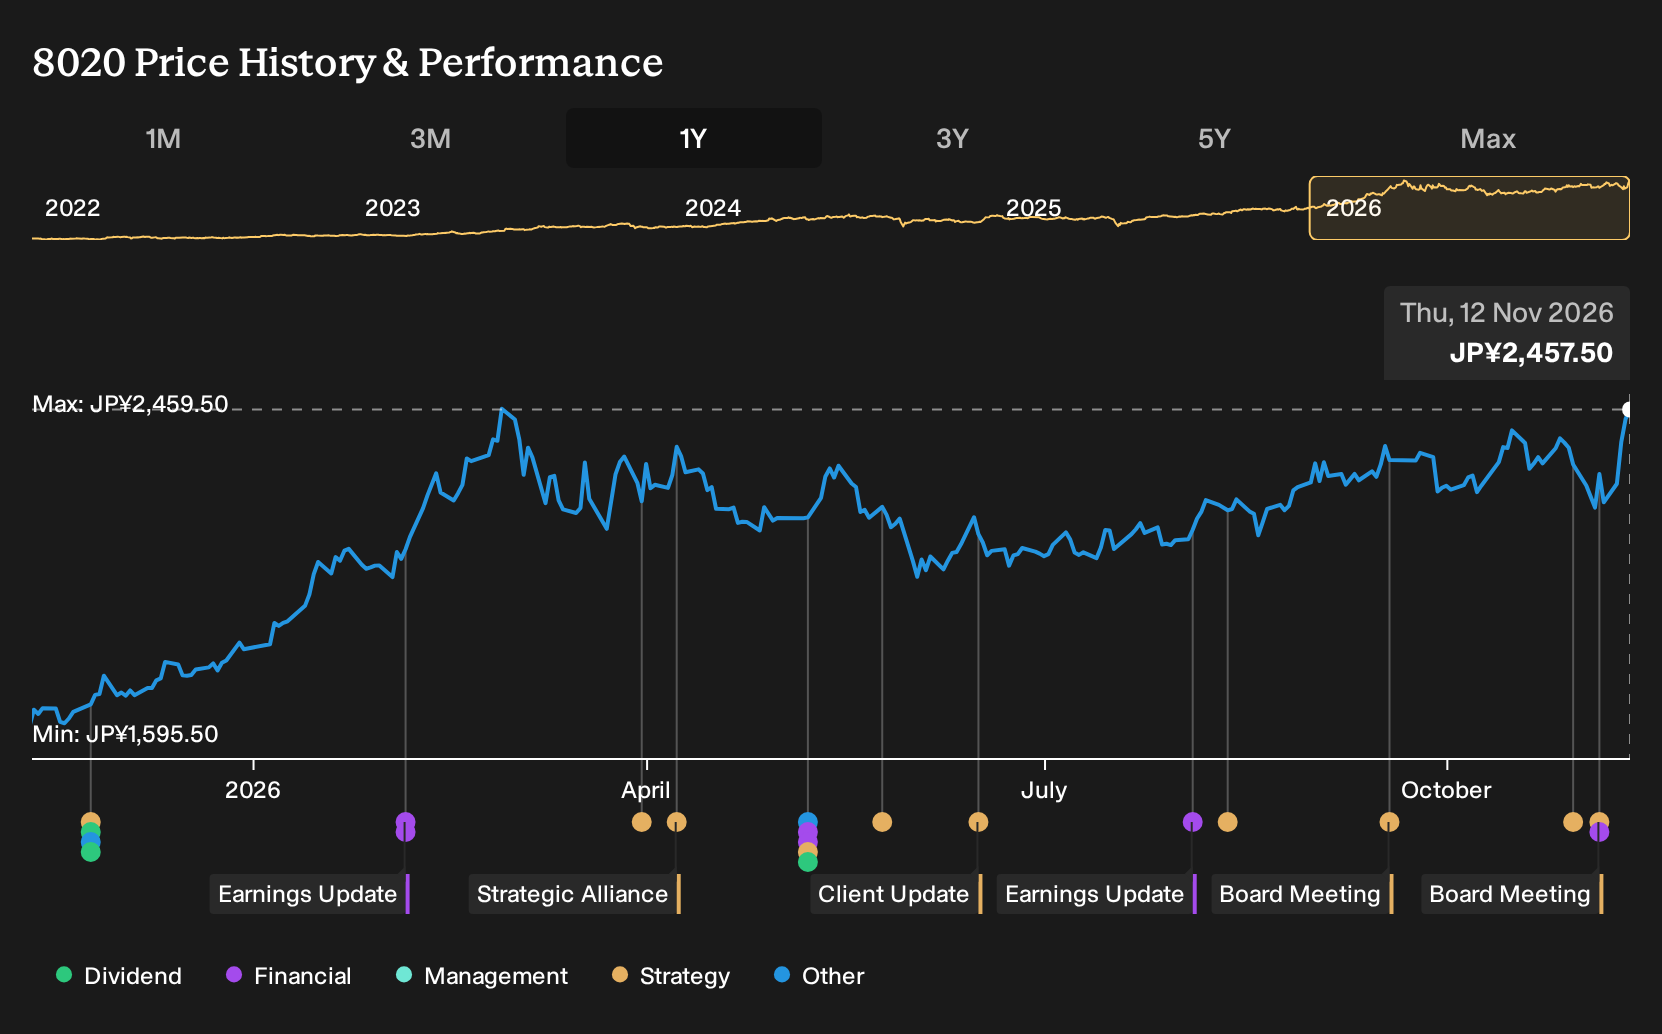
The bigger swing factor is how repeatable this earnings step up really is. Tender offer related equity method profit, board approved on October 27, 2026, will not recur in the same way, and the group still runs with a high level of debt and an unstable dividend track record in the background. Recent share price strength and a P/E around 10x versus the wider Japanese market keep the stock in focus. However, the short term story now leans heavily on Kanematsu proving it can keep margins and cash generation intact while funding a higher payout.
Even so, beneath the upbeat dividend headlines sits a balance sheet and cash flow question that could matter a lot if...
There's only one way to know the right time to buy, sell or hold Kanematsu. Head to Simply Wall St's company report for the latest analysis of Kanematsu's Fair Value.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Kanematsu research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Kanematsu. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kanematsu's overall financial health at a glance.
Looking For More Investment Ideas Beyond Kanematsu?
If Kanematsu has sharpened your interest in what else might be out there, it can help to line it up against a wider field of candidates that match different priorities such as income, resilience, or future re rating potential.
- If you want potential income plus staying power, scan companies offering resilient payouts and balance sheets through our 27 dividend fortresses.
- If capital preservation is your priority, filter for companies with steadier risk profiles by using the 20 resilient stocks with low risk scores.
- If you are hunting for mispriced quality, compare Kanematsu with a curated pool of potentially underappreciated ideas through the 74 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com