


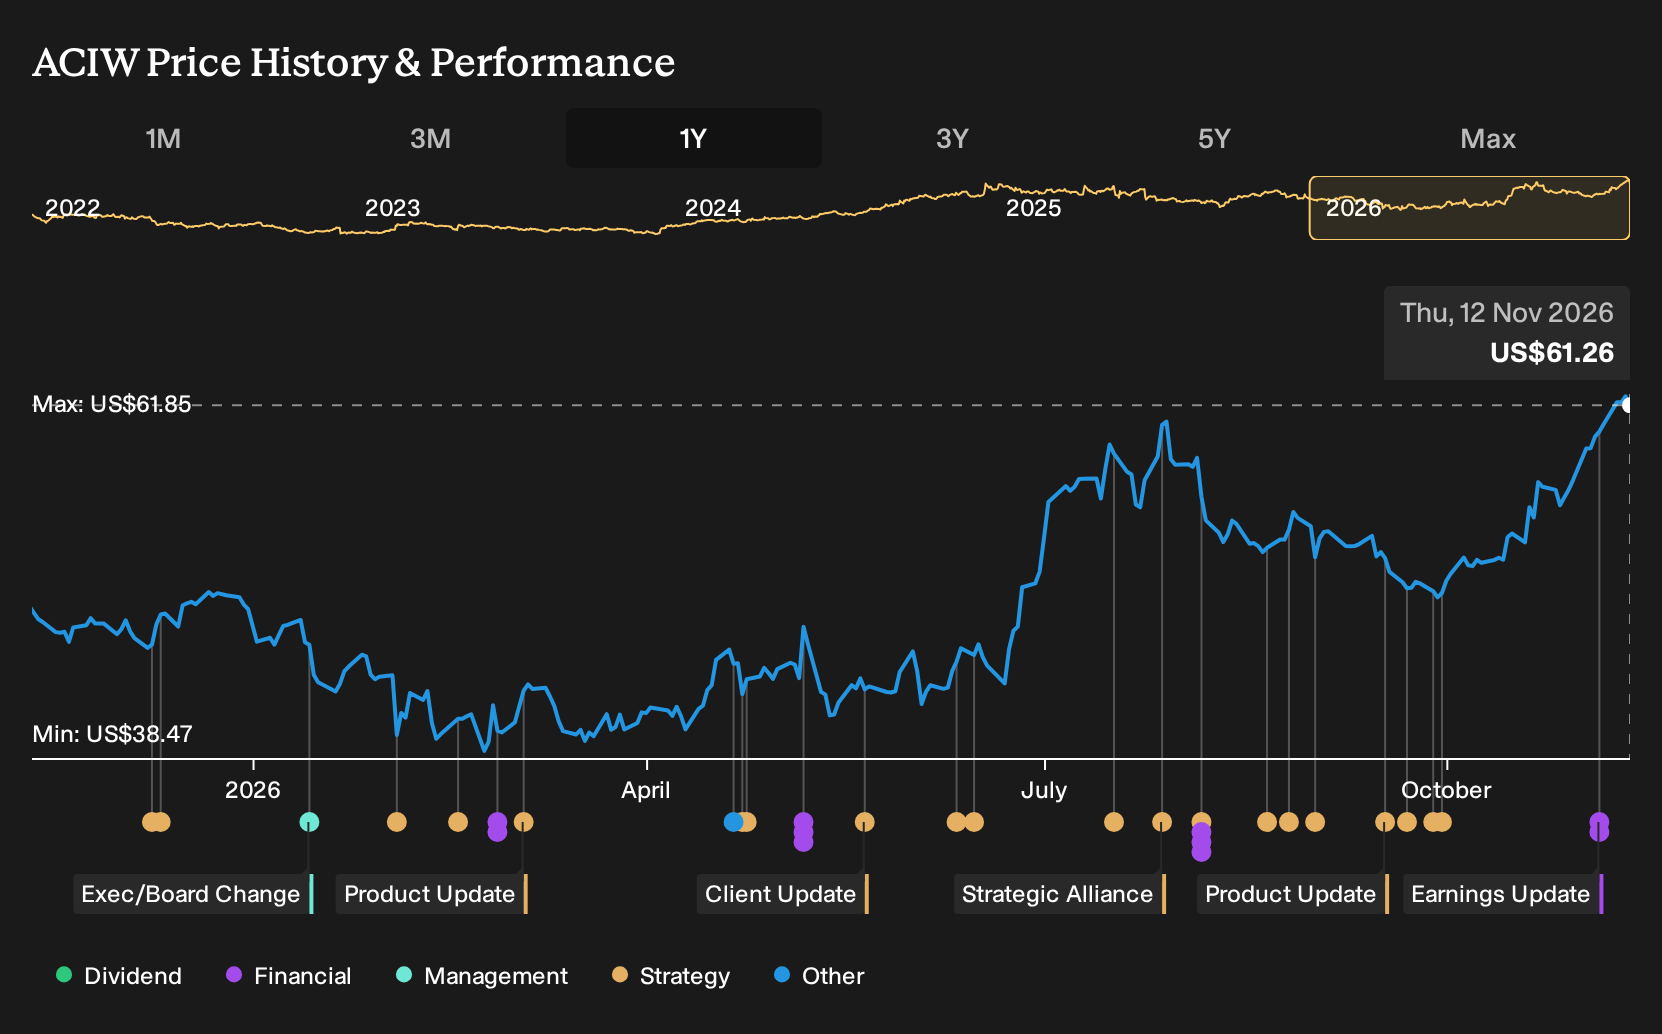
- ACI Worldwide reported third quarter 2026 results on 5 November 2026, with revenue of US$426.81 million and net income of US$32.53 million, and reaffirmed full year revenue guidance of US$1.895 billion to US$1.925 billion alongside fourth quarter guidance of US$612 million to US$642 million.
- The sharp year over year drop in quarterly revenue and earnings, contrasted with steady full year guidance, highlights execution pressure on near term performance while management signals confidence in the broader 2026 outlook.
- This context helps frame how ACI Worldwide's weaker third quarter earnings but reaffirmed full year guidance fit into its broader investment narrative.
Scan how ACI Worldwide's latest guidance compares with a curated group of payment and fintech peers by reviewing the 32 high quality undervalued stocks, which combines stronger balance sheets with disciplined cash generation.
ACI Worldwide Investment Narrative Recap
To hold ACI Worldwide, you need to believe the payments software and biller platforms, like ACI Connetic and Speedpay One, can keep winning volume and wallet share despite heavy competition and regulatory change. The third quarter shortfall in revenue and earnings, relative to last year, puts more attention on execution. However, full year guidance being reiterated suggests the near term thesis has not been reset.
The key short term catalyst remains proof that newer cloud and real time payments wins translate into steadier, higher quality revenue and improved profitability after a period of margin pressure. The biggest risk is that competitive and contract related hits, especially in areas like the Biller segment, continue to weigh on earnings even when guidance stays unchanged.
The most relevant update is ACI Worldwide reaffirming full year 2026 revenue guidance of US$1.895b to US$1.925b while posting weaker third quarter figures. That combination keeps the focus squarely on how much of the fourth quarter and pipeline is already locked in through recurring contracts and committed projects, compared with what is still dependent on closing new deals.
For an investor, that guidance ties directly into the analyst consensus Narrative on Simply Wall St, which leans on recurring software, real time payments and efficiency gains as core drivers. Any sustained gap between reported margins and those longer term expectations, especially with high debt and lower recent profit margins, becomes the operational tension to watch into the next set of results.
ACI Worldwide Long Term Assumptions And Valuation Bridge
ACI Worldwide's narrative projects US$2.3b revenue and US$404.5 million earnings by 2029. This implies revenue expanding at 10.0% per year and earnings rising by about US$237.5 million from US$167.0 million today.
Uncover why ACI Worldwide's fair value indicates an 11% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on ACI Worldwide leans hard into Biller earnings risk. The most cautious analysts were already assuming 2029 earnings of about US$399.3 million on roughly US$2.3b of sales before this third quarter miss. That is a more restrained narrative than consensus, and this latest report may push those forecasts further apart.
Explore 4 other ACI Worldwide fair value estimates, including one that suggests as much as 27% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ACI Worldwide research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ACI Worldwide. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ACI Worldwide's overall financial health at a glance.
Looking For More Investment Ideas Beyond ACI Worldwide?
Once you have a view on ACI Worldwide, it helps to set it against a wider watchlist so you can compare quality, balance sheet strength and income potential in one place using the Simply Wall St Screener.
- For investors focused on stability and capital preservation, start with companies that pair resilient operations with modest risk profiles through the 29 resilient stocks with low risk scores.
- If you care most about financial resilience and cleaner balance sheets, filter for businesses with stronger leverage and liquidity metrics using the list of solid balance sheet and fundamentals (23 results).
- Those looking to combine quality fundamentals with a price that still looks reasonable can scan a curated set of potential mispriced opportunities via the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com