


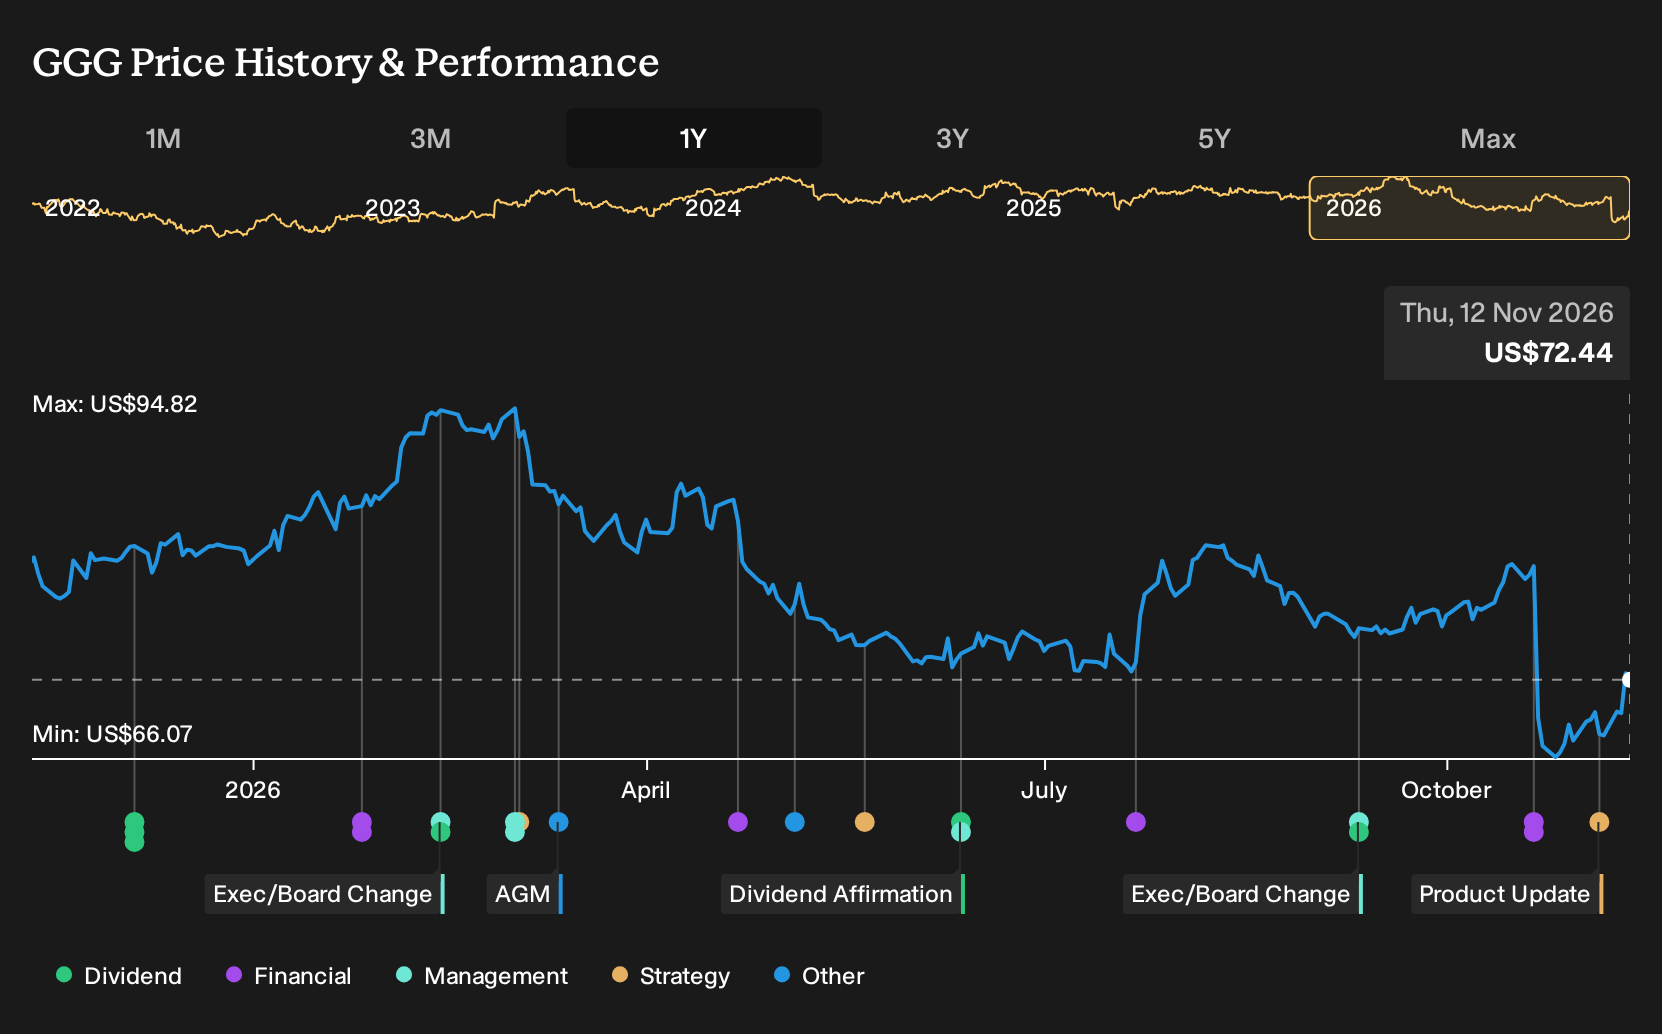
- Graco has rolled out two new products, a redesigned SnugRide Turn & Slide rotating infant car seat and the QUANTM i230 electric double diaphragm pump, while also executing a US$600 million accelerated share repurchase funded by cash and borrowings.
- The combination of a higher tech electric pump aimed at throughput and energy costs, a reengineered car seat following a voluntary recall, and a large capital return program suggests that Graco is focusing on product execution, safety credibility, and cash flow per share at the same time.
- This article examines how Graco's investment narrative is influenced by the accelerated share repurchase alongside the updated rotating car seat.
Scan how other industrial and consumer stocks are trying to turn product launches and buybacks into potential breakouts with our hand picked 20 high quality undiscovered gems aligned to Graco's playbook.
Graco Investment Narrative Recap
To own Graco, an investor needs to believe in disciplined product execution, steady margins and consistent cash generation across Contractor, Industrial and Expansion Markets. The analyst consensus Narrative on Simply Wall St leans on those themes, pointing to earnings growth and high return on equity. The US$600 million accelerated share repurchase sits on top of that and affects per share metrics more than near term operations.
Right now, the key short term swing factor is how demand holds up as organic sales have already shown pockets of softness. The biggest risk remains pressure on margins if tariffs rise or price increases start to meet resistance at the same time as volumes weaken.
The launch of the QUANTM i230 electric double diaphragm pump feels most tied to that near term story. It targets high flow, energy intensive industrial processes where customers care about throughput and power costs, which directly links to Graco’s Industrial segment focus on higher technology end markets.
If QUANTM adoption tracks the broader product rollout plan flagged in the analyst consensus Narrative on Simply Wall St, it could support revenue mix and margin resilience over time. Execution risk sits in qualifying the pump into demanding plant environments and proving the claimed energy savings in real customer settings.
Graco’s current analyst script points to revenues of US$2.9b and earnings of US$652.1m by 2029, based on an assumed 8.0% yearly increase in revenue and an earnings uplift of about US$134.6m from the US$517.5m reported today.
Uncover why Graco's fair value indicates a 15% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between US$60 and about US$90.88, which already shows how far apart views on Graco can run. Set that against tariff and margin risks on one side, and product launches plus capital returns on the other, and you are looking at sharply different performance paths. Consider those contrasts and explore more community viewpoints before fixing on your own thesis.
Explore 2 other Graco fair value estimates, including one that suggests up to 25% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Graco research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Graco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Graco's overall financial health at a glance.
Looking for more investment ideas beyond Graco?
If the Graco story has sharpened your thinking on product execution, capital returns, and risk, use that same lens to filter other opportunities with the Simply Wall St Screener. Start with a few focused toolkits that line up with different styles of portfolios.
- For investors hunting for companies that screen as potentially underpriced with solid fundamentals, scan our curated set of 32 high quality undervalued stocks that fit that brief.
- If resilience and balance sheet strength matter most to you, narrow your watchlist using the list of solid balance sheet and fundamentals (23 results) to pinpoint businesses with sturdier financial foundations.
- For readers who want to widen the search to less crowded ideas with healthy metrics, cast a wider net through the 20 high quality undiscovered gems and see what else aligns with your thesis.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com