


UK GDP just surprised on the upside, and that matters for you if you care where your money is working hardest. Stronger output, healthier services activity and more confident consumers can shift the odds for domestically focused shares, creating chances that do not sit around forever. This piece breaks down what the new data could mean and walks through 3 UK services stocks that look closely tied to this story.
The stocks covered below are only a small sample of what this rebound could mean for UK services. The full screen surfaces 30 more domestically focused companies with equally compelling narratives that are not unpacked here. To go further and identify your own highest conviction angles, head straight into the UK domestically focused services stocks screener to filter and analyze the wider set of UK services stocks tied to this story.
Fintel (AIM:FNTL)
Fintel plugs directly into the UK domestically focused services theme by supplying fintech, software and support to advisers and lenders whose activity is closely linked to the health of local financial services. The bullish analyst Narrative on Simply Wall St captures why that mix is attracting attention right now.
"The shift within Fintel toward a higher mix of SaaS and subscription income, now 68% of group revenue with management guiding to 70% to 80%, creates room for a richer layer of add on modules and premium tiers that could influence revenue growth and margin mix beyond what headline recurring revenue targets alone capture."
What happens if one still underappreciated part of Fintel’s UK-focused ecosystem starts to change the pricing power behind those recurring cash flows?
Fintel is a Huddersfield based fintech and support services group for the UK retail financial services sector, with Software & Data generating about £38.9 million and the Services division about £48.9 million. At a market value near £187 million, it sits firmly in the UK mid-cap services bracket.
As that pricing power question opens up, the full narrative for Fintel lays out how Fintel’s recurring model, capital allocation and risks could interact if UK services momentum keeps accelerating.

Mha (AIM:MHA)
Mha is a UK professional services group rooted in Milton Keynes that advises domestic businesses and individuals on tax, audit, accountancy and wider business strategy. It generated about £251 million from professional services and carries a market value of roughly £377 million.
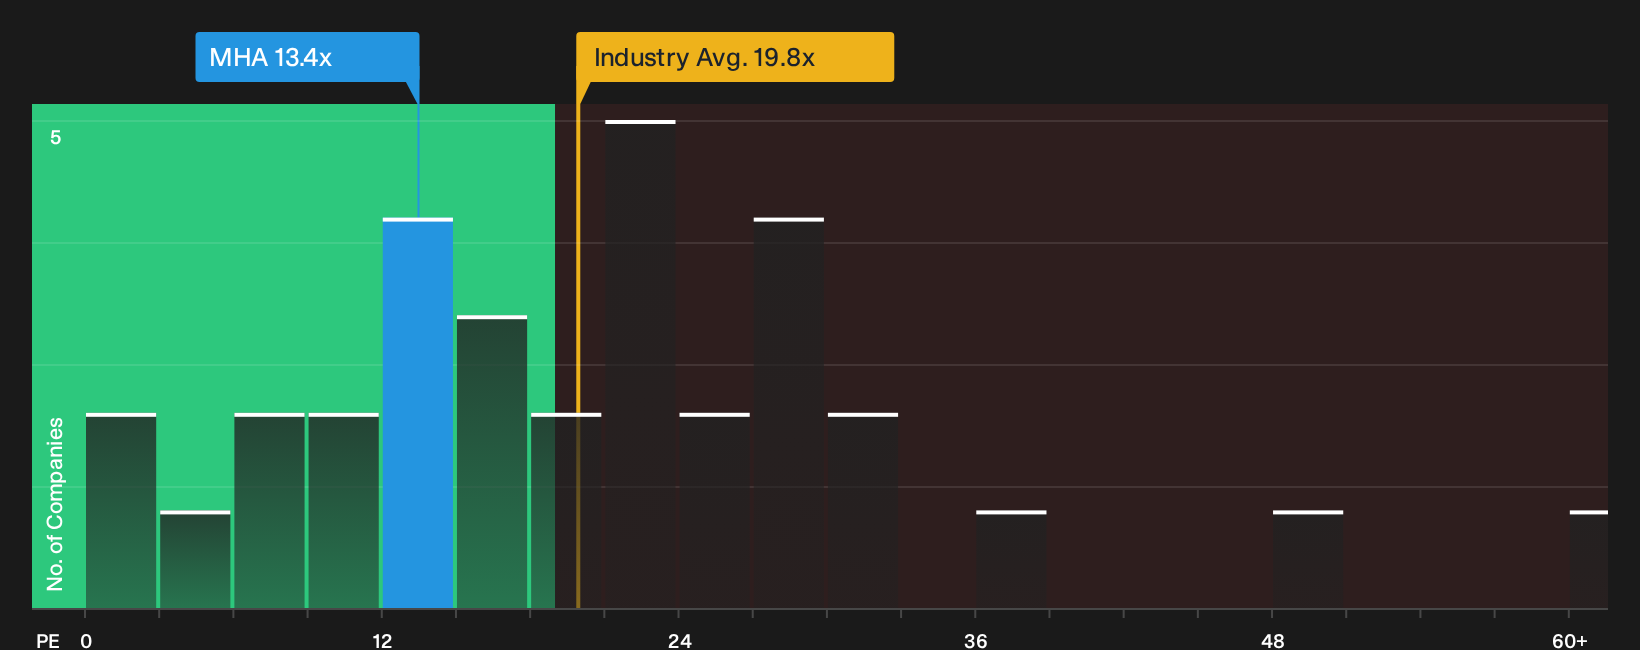
Mha is closely aligned with the UK services theme, with professional and business advice predominantly purchased by domestic clients whose activity reflects local GDP and corporate confidence. Modest forecast revenue and earnings growth, a P/E below sector averages and high reported ROE together present an interesting setup if a single pressure on profitability changes direction.
If that single pressure on Mha’s profitability really starts to turn, the 4 key rewards and 1 important warning sign shows where the upside and the friction may actually lie.
BTG Consulting (AIM:BTG)
BTG Consulting plugs directly into the UK domestically focused services theme as a Manchester based financial and real estate adviser, with about £116.8 million from restructuring and advisory work and £51.7 million from property services, and a market cap near £182 million.
The analyst consensus Narrative on Simply Wall St argues that the real interest in BTG Consulting right now lies in how its restructuring and real estate engines link into the current UK cycle, not just that they exist.
"Higher insolvency and restructuring activity, including larger and more complex cases with improved hourly recovery rates, is feeding into BTG Consulting’s restructuring and advisory division and is likely to be a key driver of future revenue and earnings quality."
What happens if one quietly building trend inside those UK focused advisory mandates starts to reshape how much profit each instruction produces?
As that margin shift builds, the full narrative for BTG Consulting spells out how BTG Consulting’s restructuring engine, real estate arm and risks could interact as conditions keep evolving.

Seeking Fresh Alternatives Before They Fly
Fresh opportunities do not wait. Breakout themes pick up momentum, early data gets stale and prices move before the crowd reacts. Scan these curated ideas while it matters and consider getting in early.
- Consider strong cash generators with room to move by running the list of solid balance sheet and fundamentals (9 results) and focusing on businesses where resilient finances back up the story.
- Explore powerful income streams from companies offering robust yields by using the 5 dividend fortresses while these payout opportunities remain under the radar for now.
- Look for AI exposure that is already earning its keep with the 41 profitable AI stocks that aren't just burning cash before momentum around real profits, not just hype, is fully reflected in prices.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com