


Rapid7 (RPD) is back in focus after third quarter results showed softer revenue and profit compared with last year, along with fresh guidance that points to lower full year 2026 sales.
Rapid7’s share price has slipped 2.57% over the last day and 6.74% over the past week. It still holds a 30 day share price return of 11.46% and a 1 year total shareholder return of 4.58%, while the 3 and 5 year total shareholder returns remain deeply negative, which points to fading long term momentum after a recent short term bounce.
Scan beyond Rapid7 and see how other cybersecurity stocks are trading on weak guidance and mixed returns by reviewing the hand picked 29 resilient stocks with low risk scores in this corner of the market.
Rapid7 now trades at a meaningful discount to both analyst targets and an estimated fair value, yet guidance points to shrinking sales. Is the stock cheap for a reason, or is the market leaning too hard on caution?
Most Popular Narrative: 7% Undervalued
On the analyst consensus Narrative on Simply Wall St, Rapid7 screens as modestly undervalued, with a fair value of $15.45 against a last close of $14.40. This puts the focus squarely on whether profit expansion can offset pressure on shrinking revenue.
Plans to reach about 20% non GAAP operating margin by Q4 2026, up from 13.7% in Q2 2026, together with guidance for roughly flat free cash flow of around US$130 million in 2026 and expectations of improvement in 2027, indicate that investors are already pricing in significant net margin expansion that is not yet reflected in earnings.
See why 15 investors see Rapid7 as 7% undervalued.
Result: Fair Value of $15.45 (UNDERVALUED)
Still, the bearish narrative can crack if Rapid7 proves steadier Detection & Response and Exposure Management ARR, or if margin gains outpace today’s cautious expectations.
Find out about the key risks to this Rapid7 narrative.
Another View: Rapid7 Looks Expensive On Earnings
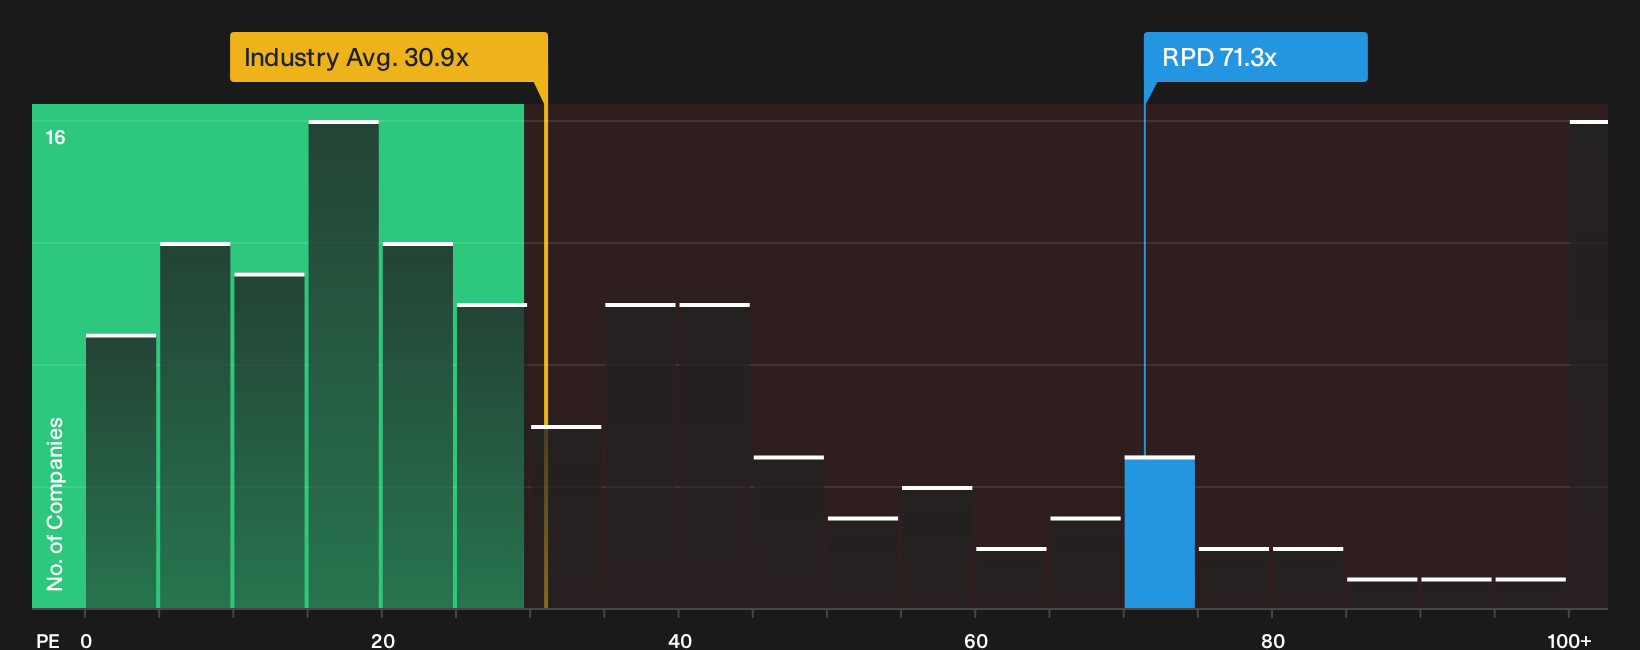
On the flip side of that cash flow based undervaluation, Rapid7 screens as pricey on its P/E ratio. The stock trades on 71.3x earnings, compared with 31.2x for the US Software group, 42.6x for peers and a fair ratio of 36.1x that the market could move toward over time.
This wide gap increases the risk that the share price has less room for error if profit growth or sentiment cools, even with an attractive cash flow story in the background. Which lens do you trust more when the signals pull in opposite directions, the income statement or the DCF model underpinning those future cash flows?
For a closer look at how that earnings multiple stacks up against fundamentals and peers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Rapid7 is clearly mixed, with caution on risks sitting beside some genuine bright spots that investors are watching closely. Act quickly, review the underlying data, and pressure test the 2 key rewards and 4 important warning signs
Looking for more investment ideas beyond Rapid7?
If Rapid7 has your attention, do not stop here. Cast a wider net so you can compare opportunities side by side and avoid missing stronger setups.
- Target resilient balance sheets and steadier fundamentals by reviewing the list of solid balance sheet and fundamentals (23 results).
- Spot potential value opportunities earlier in the cycle by scanning the 20 high quality undiscovered gems.
- Focus on quality at a discount by running through the 32 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com