


JFrog (FROG) is back in the spotlight after third quarter results turned a prior loss into a US$6.55 million profit and management raised full year 2026 revenue guidance.
Investors have responded quickly to JFrog's earnings and raised guidance, with a 1 day share price return of 1%, a 7 day share price return of 9.5% and a 30 day share price return of 20.3%, adding to an 85.7% year to date share price return and a 1 year total shareholder return of 87.2%. This points to strong momentum built up over several years given the very large 3 year and 5 year total shareholder returns.
Scan for other software and AI infrastructure players showing similar earnings momentum to JFrog by reviewing our hand picked 53 AI infrastructure stocks along with this quarter's results.
After a move this strong, driven by JFrog's profit swing and higher guidance, the key issue now is whether the current price still offers a favourable risk reward profile for new money.
Most Popular Narrative: 2% Undervalued
JFrog's last close at $110.60 sits just below the $113.14 fair value in the analyst consensus Narrative on Simply Wall St. This view applies an 8.57% discount rate and blends revenue and earnings forecasts into a single assessment of upside risk versus execution risk.
The main thing that has to go right is that JFrog continues to convert the AI fueled demand for binaries and software supply chain security into sustained growth in high value cloud and platform contracts, including strong attach rates for security across its largest customers.
The current valuation and upgraded price targets into the US$115 to US$125 range from several research firms suggest that the market is starting to price in JFrog as an undervalued, high quality platform with meaningful upside if the AI and security driven growth thesis plays out.
See why 18 investors see JFrog as 2% undervalued.
Result: Fair Value of $113.14 (UNDERVALUED)
Still, the narrative around JFrog can be shaken if another security incident erodes trust, or if AI driven cloud usage fails to convert into longer term commitments.
Find out about the key risks to this JFrog narrative.
Another View On JFrog's Valuation
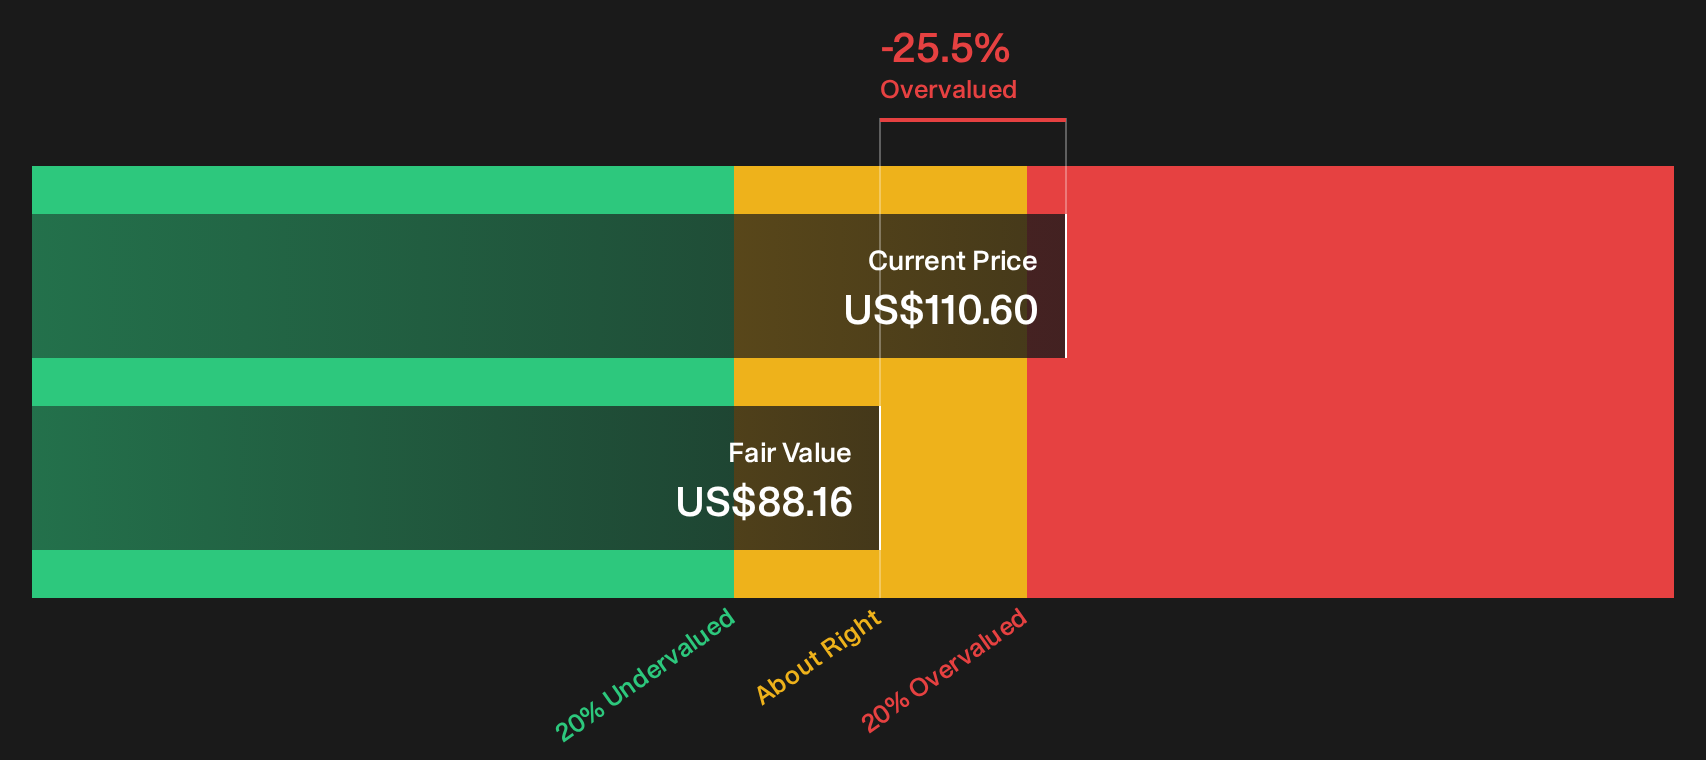
The analyst Narrative frames JFrog as about 2% undervalued at $110.60 versus a $113.14 fair value. The SWS DCF model paints a tougher picture, with an estimated future cash flow value of $88.16, which implies the shares are priced well above that level and could be overvalued on this lens. Which roadmap do you trust more: the earnings based story or the cash flow math?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Whether you are encouraged by the mix of optimism and concern around JFrog, or feeling cautious after such a sharp run, you should move quickly and consider both perspectives by reviewing the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond JFrog?
If JFrog is already on your radar, do not stop there. Spread your research across other opportunities so you are not relying on a single winner.
- Target resilient returns by scanning a basket of companies with lower historical risk profiles through our 29 resilient stocks with low risk scores.
- Hunt for potential mispricing by reviewing companies that combine solid fundamentals with appealing valuations using our 32 high quality undervalued stocks.
- Stack potential income on top of growth by focusing on companies with stronger yields in our 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com