


Liberty Latin America has delivered a solid share price run in recent years, and the question now is whether that momentum lines up with what its current sales can support. With the stock changing hands at US$9.73, investors are weighing how the recent performance and fresh corporate moves stack up against the revenue base of the business.
- Liberty Latin America has returned 39.6% over the past 3 years, which puts real weight on whether the present valuation can be grounded in its sales rather than just share price strength.
- The group reported a loss alongside stable revenue of about US$1.12b and higher interest and tax costs, which can influence how much of each dollar of sales ultimately supports equity value.
- There is a second opinion on Liberty Latin America worth weighing. See what analysts think Liberty Latin America's shares could be worth.
The issue now is whether Liberty Latin America’s current share price is justified by the revenue it generates when viewed through its sales based valuation lens.
If you want to explore similar sales-based valuation questions beyond Liberty Latin America, you can run the numbers across our 32 high quality undervalued stocks.
Does Liberty Latin America Look Undervalued on Sales?
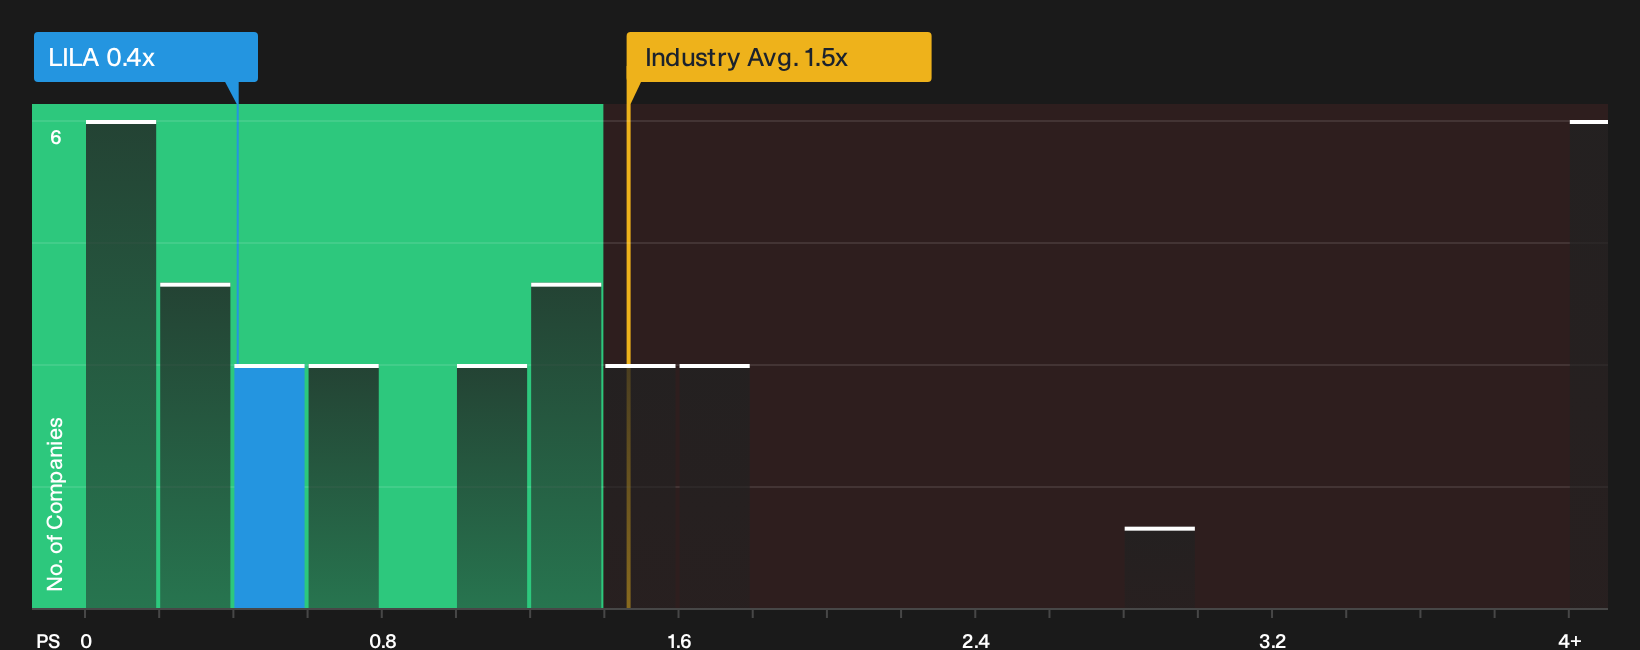
For a telecom operator like Liberty Latin America, where net income can be noisy, investors often look at the P/S ratio to anchor the share price to the revenue line. On this yardstick, the stock trades on about 0.4x sales, which is well below the Telecom industry average of roughly 1.5x and also below peers around 1.1x. Based on a tailored fair multiple that takes the group’s scale, margins and risk profile into account, the current P/S sits on the low side. This points to the shares screening as undervalued on this framework.
Because Liberty Latin America recently reported a quarterly loss despite stable revenue around US$1.12b, the low P/S suggests investors are giving limited credit for that top line while focusing on interest costs, taxes and leverage. That gap between what the market is paying for each dollar of sales and what the valuation model implies as a fair anchor is what readers need to weigh against factors like free cash flow, capital intensity and the ongoing Puerto Rico debt talks. Explore the numbers behind Liberty Latin America's P/S valuation.
The Liberty Latin America Narrative: What Would Justify Today's Price?
Narratives pick up where the P/S puzzle leaves off for Liberty Latin America. They spell out which combinations of future revenue growth, profitability and earnings power would need to materialise for the current share price to look either conservative or stretched, and each one links its implied value to a clear view on how growth, margins and risks might evolve so you can come back to it as fresh numbers and news flow through Simply Wall St's Community page.
The bullish and bearish views on Liberty Latin America are far apart, with one side seeing the stock as 8% undervalued and the other 39% overvalued.
Bull case: 8% undervalued
This view comes from the analyst consensus Narrative on Simply Wall St, which aggregates mainstream forecasts into a single storyline.
"Analysts expect Liberty Latin America to keep leaning into higher value mobile and fixed mobile convergence bundles, AI driven cost savings, and its subsea and enterprise networks to support further margin resilience and cash generation…"
Discover why this Narrative puts Liberty Latin America at 8% undervalued.
Bear case: 39% overvalued
This view is set out in the bearish analyst Narrative on Simply Wall St, which builds around the lowest targets and assumptions.
"Bearish analysts expect Liberty Latin America to see its recent 75% share price rally unwind, as rich valuation, high leverage, and reliance on buybacks and Puerto Rico litigation leave limited support if sentiment turns…"
Explore why this Narrative puts Liberty Latin America at 39% overvalued.
One more Liberty Latin America check that belongs beside the price tag
Before you file Liberty Latin America away as cheap, expensive or somewhere in between, it helps to see how professional analysts think the business might look a few years from now and compare that to today’s share price. Explore where analysts expect Liberty Latin America to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com