


Otsuka Holdings (TSE:4578) has given investors fresh numbers to work with after raising its full year earnings guidance and reporting higher nine month sales and net income on October 30, 2026.
The raised guidance, ongoing share buyback and move toward an Audit and Supervisory Committee have arrived during a strong run for Otsuka Holdings, with the share price up 35.54% year to date and a 5 year total shareholder return of 226.65% indicating continued momentum.
Scan other companies that are showing similar earnings momentum and shareholder returns to Otsuka Holdings by checking our curated list of 18 high quality undervalued stocks.
After a 52% one year total return and upgraded earnings guidance, the question for Otsuka Holdings now shifts. Does the current price still leave enough upside to compensate you for the risks?
Most Popular Narrative: 16% Undervalued
On the analyst consensus Narrative on Simply Wall St, Otsuka Holdings screens as undervalued, with a fair value of ¥14,584.62 against a last close of ¥12,265. That gap sits on top of a strong recent share price run, so the question becomes how much weight you place on the assumptions behind that estimate.
Maintaining growth in both pharma and nutrition or consumer businesses, with recent guidance pointing to higher full year revenue and profit than previously planned, adds to Otsuka Holdings’ ability to reinvest in new products while supporting operating leverage and margin stability.
Cash generation running above the current midterm plan, together with higher planned growth investment and increased returns such as a larger dividend and share repurchases, signals capacity for Otsuka Holdings to fund additional assets and platforms that can drive future earnings and potentially support a re rating of valuation multiples.
See why 0 investors see Otsuka Holdings as 16% undervalued.
Result: Fair Value of ¥14,584.62 (UNDERVALUED)
Still, the bullish script around Otsuka Holdings frays quickly if delayed generics finally arrive for key drugs, or if analyst growth and margin forecasts prove too optimistic.
Find out about the key risks to this Otsuka Holdings narrative.
Another View: What Otsuka Holdings’ P/E Is Really Telling You
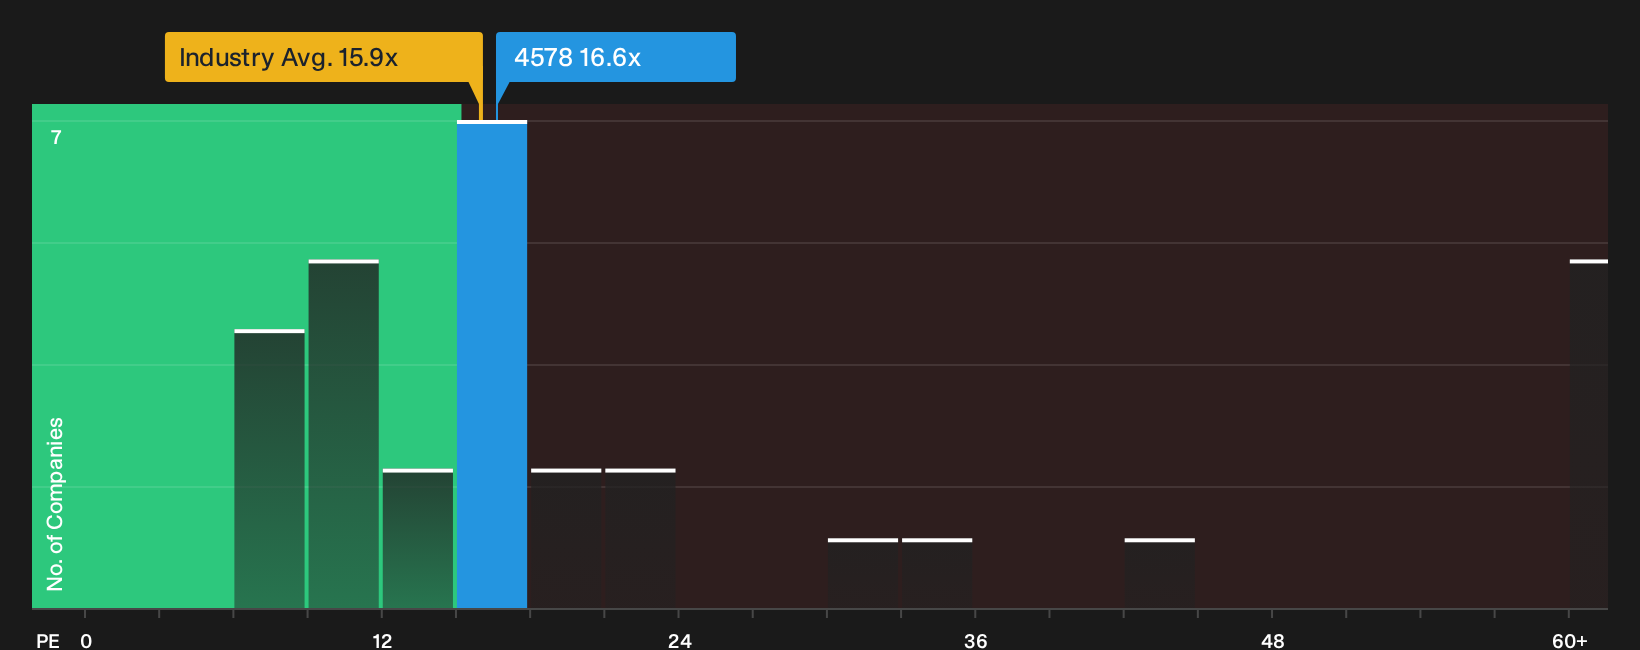
That 16% discount to the Simply Wall St fair value is only one lens. On earnings, Otsuka Holdings trades on a 16.6x P/E, slightly above both the JP Pharmaceuticals group at 15.7x and peers at 16x, yet well below a fair ratio of 30.2x. Is that a safety margin or a warning that expectations are already full?
To see how that earnings multiple stacks up in more detail, and how the fair ratio could influence where the market moves, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Otsuka Holdings is upbeat right now, so do not just take the consensus at face value and move on. Act while the information is fresh and stress test the thesis for yourself by weighing the 2 key rewards.
Looking for more investment ideas beyond Otsuka Holdings?
If Otsuka Holdings has sharpened your focus on quality opportunities, do not stop here. Use this momentum to scan broader markets and test your next move.
- Target companies with stronger cash generation by reviewing those in our 27 dividend fortresses, which focuses on income potential alongside balance sheet strength.
- Look for businesses with fewer red flags by scanning the 20 resilient stocks with low risk scores, which filters for sturdier financial profiles and lower risk scores.
- Identify potential earlier-stage opportunities by checking the 74 high quality undiscovered gems, which highlights under-the-radar candidates with solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com