


Sally Beauty Holdings has rewarded long term shareholders with a strong run in recent years, and that kind of performance naturally raises the question of whether the current share price is still supported by its earnings power. With the stock near recent highs and fresh company updates in the mix, the focus now turns to what the profit stream actually justifies.
- Over the past 3 years the share price has gained about 113%, which puts real pressure on the question of how much earnings strength is already reflected in the valuation.
- Recent reports of modest sales growth together with stronger profit figures and solid cash generation can support a case that earnings quality and balance sheet flexibility matter more than headline revenue momentum for this story.
- Your read on Sally Beauty Holdings is one view; the desks covering it have another. See what analysts think Sally Beauty Holdings's shares could be worth.
The issue now is whether Sally Beauty Holdings' current price around US$18.41 is adequately backed by the earnings the business is generating today and is expected to deliver in the near term.
If you are weighing Sally Beauty Holdings through the lens of its earnings and recent three year share price run, it can help to stack it against 32 high quality undervalued stocks.
Is Sally Beauty Holdings a Bargain on Earnings?
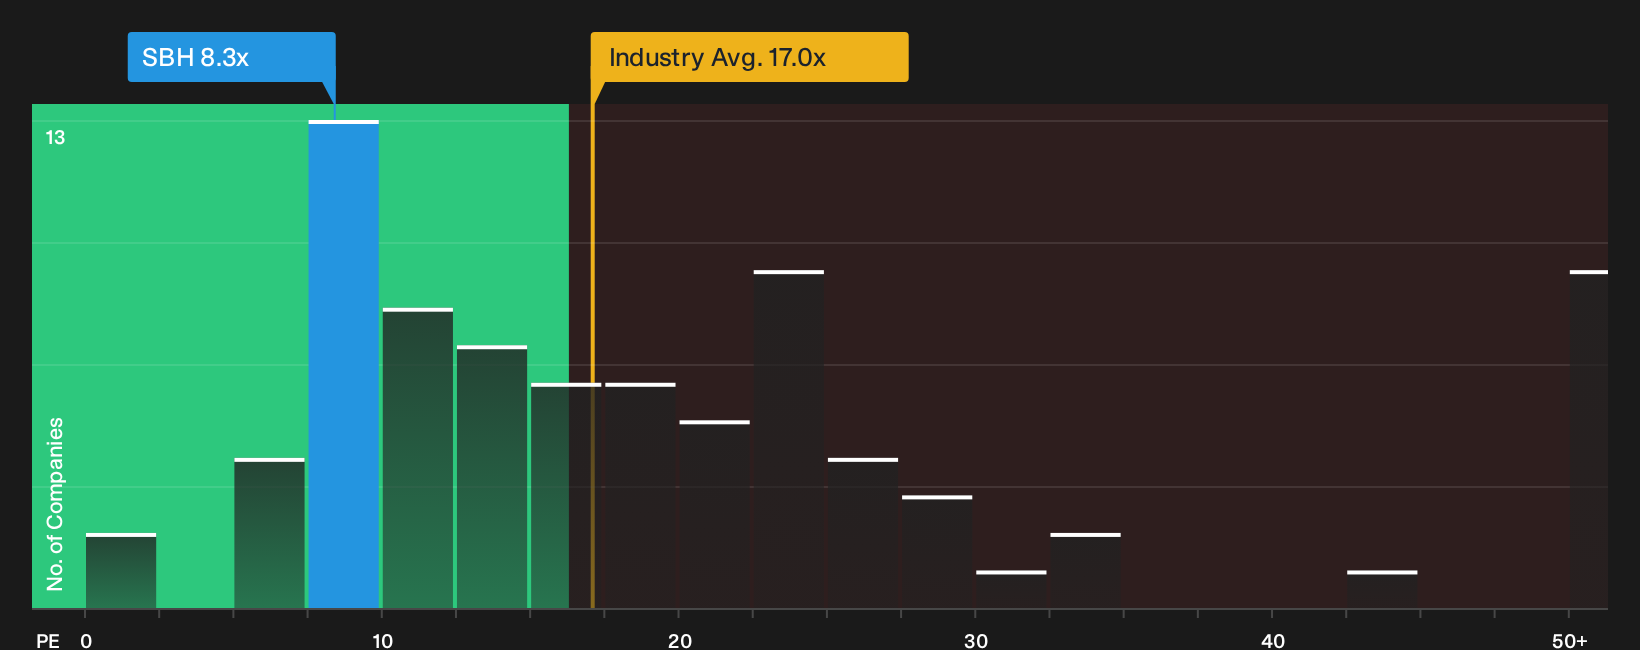
The P/E ratio suits Sally Beauty Holdings because recent profit figures give you an earnings anchor that is easier to relate to than sales alone. On this lens, the stock trades on about 8.3x earnings, which is well below the Specialty Retail industry average of roughly 17.0x and also beneath a broader peer group around 23.1x. Despite the recent FY 2026 update pointing to solid earnings and cash generation, the market is still attaching a lower earnings multiple than many comparable retailers.
The Fair Ratio model, which takes into account factors like the company’s sector, margins, size and risk profile, points to a higher P/E than where Sally Beauty Holdings currently trades. That gap suggests the shares screen as undervalued on this earnings yardstick, even after the run in the share price and the 2027 guidance outlined this year. Explore the numbers behind Sally Beauty Holdings's P/E valuation.
The Sally Beauty Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Sally Beauty Holdings link the valuation puzzle above to clear future paths for the business by spelling out what would need to happen to growth, margins and earnings for the shares to be worth materially more or less than they are today on the market. Where a single ratio or model output gives one number, these storylines lay out the future that number relies on so you can watch in real time how closely reality tracks it on the Community page.
The two views on Sally Beauty Holdings sit close on valuation, yet one side sees more to play for than the other.
Bull case: 10% undervalued
This view comes from the analyst consensus Narrative on Simply Wall St, which leans on shared forecasts rather than a single voice.
"Expansion of personalized digital initiatives like Licensed Colorist On Demand, which is delivering more than 5,200 weekly consultations with LCOD customers spending about 80% more annually than others..."
Discover why this Narrative puts Sally Beauty Holdings at 10% undervalued.
Bear case: roughly fairly valued
This angle is drawn from the bearish analyst Narrative on Simply Wall St, which builds off the most cautious forecast set.
"Bearish analysts expect Sally Beauty Holdings to remain growth constrained as physical stores carry much of the load, while Beauty Systems Group comparable sales and transactions continue to face pressure..."
Explore why this Narrative puts Sally Beauty Holdings at roughly fairly valued.
Before you finish on Sally Beauty Holdings, one more check belongs beside the earnings multiple
Valuation only tells part of the story, because Simply Wall St’s broader review has also surfaced specific risk indicators for Sally Beauty Holdings that deserve a closer look before you grow too comfortable. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com