


Why Ventas Earnings Are Back In Focus
Ventas (VTR) returned to investor watchlists after its latest earnings report highlighted a 23% revenue increase and 10% growth in normalized FFO per share, supported by strong senior housing operating performance.
The latest earnings update has arrived after a strong run in Ventas, with the share price up 6.92% over the past month and 15.93% year to date. The 1 year total shareholder return of 18.93% and very large 3 year gain of about 7x point to momentum that has been building rather than fading.
Scan the senior housing momentum around Ventas and compare it with other real estate operators showing similar strength using our curated list of solid balance sheet and fundamentals (23 results)
Ventas has already put up a strong run, yet the shares still sit below both analyst targets and some fair value estimates. Is that discount a genuine opportunity, or is it the market’s way of pricing in risk?
Most Popular Narrative: 10% Undervalued
Ventas is trading at $89.65 versus an analyst consensus Narrative fair value of about $99.73, pointing to a valuation gap that the analyst consensus Narrative on Simply Wall St attributes mainly to how senior housing demand and capital deployment might play out.
Ventas is positioned to benefit from a rapidly growing aging population driving sustained demand for senior housing and healthcare facilities, combined with historically low new construction, supporting multi-year occupancy gains and net operating income growth as occupancy rates move toward the 90% level. This can add operating leverage and support higher margins and earnings.
See why 16 investors see Ventas as 10% undervalued.
Result: Fair Value of $99.73 (UNDERVALUED)
Still, the Ventas narrative can be knocked off course if competition reduces acquisition yields or if senior housing occupancy and pricing fail to hold recent levels.
Find out about the key risks to this Ventas narrative.
Another View: What Multiples Say About Ventas
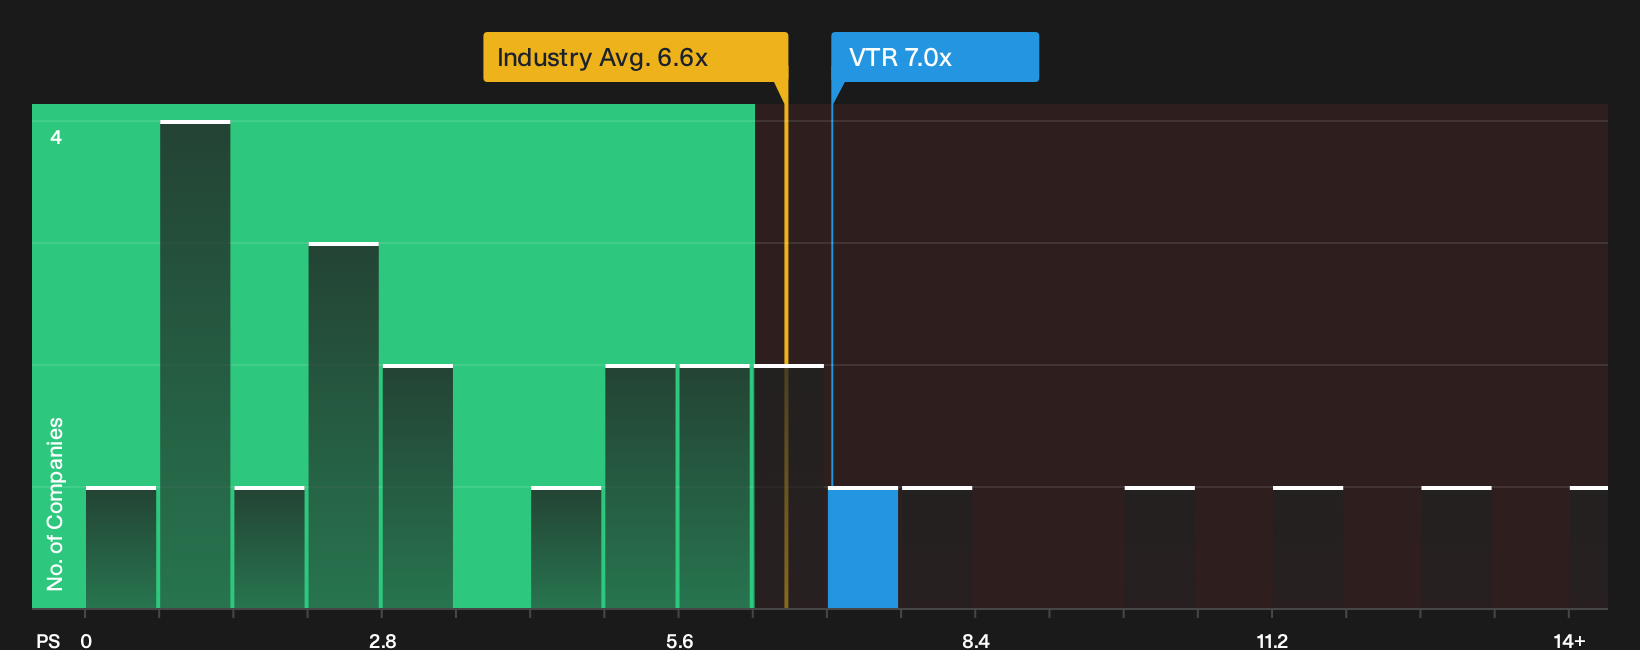
There is a twist when shifting from narrative fair value to simple pricing ratios. Ventas trades on a P/S of about 7x, which is higher than the global Health Care REITs average of 6.6x and also above a fair ratio estimate of 6.1x. That gap points to real risk that the market leans ahead of fundamentals, even if some investors see a DCF style story of undervaluation.
For a closer look at how that pricing gap lines up with earnings quality, interest cover, and balance sheet strength, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Ventas so far. If you want to move past headlines and form your own view quickly, start by weighing its 3 key rewards and 3 important warning signs.
Looking For More Ideas Beyond Ventas?
If you stop with Ventas, you only see one angle. Broaden your watchlist with other potential opportunities that match the kind of quality and pricing you care about.
- Target value with discipline and scan a curated pool of companies that combine stronger fundamentals with more modest pricing through our 32 high quality undervalued stocks.
- Prioritise resilience and stress test your portfolio against shocks by filtering for businesses that appear on our 29 resilient stocks with low risk scores.
- Spot early potential before the crowd piles in by reviewing the 20 high quality undiscovered gems that align with your return and quality filters.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com