


Why Tower Semiconductor’s latest earnings are on investors’ radar
Tower Semiconductor (TSEM) has drawn fresh attention after third quarter results showed higher sales and net income compared with a year earlier, paired with updated revenue guidance for the rest of 2026.
The share price tells a mixed story. Tower Semiconductor trades at US$157.86, with the stock falling around 29% on a 30 day share price return and roughly 41% over 90 days, even after a 7 day share price rebound of about 21% and a 1 year total shareholder return of 59%. Long term momentum remains strong, but shorter term enthusiasm has cooled as investors reassess the recent earnings beat, upgraded guidance and the November partnership update on Near Package Optics for AI infrastructure.
Scan how Tower Semiconductor’s latest earnings and AI-focused optics work compares with peers by reviewing hand-picked 53 AI infrastructure stocks that are shaping tomorrow’s data centers and compute capacity.
Bulls point to Tower Semiconductor’s rapid earnings and guidance shift, while bears focus on the sharp pullback in the share price and execution risk. Which side does the current valuation evidence really support?
Most Popular Narrative: 45% Undervalued
On the analyst consensus Narrative on Simply Wall St, Tower Semiconductor’s fair value sits at $287.41 against a last close of $157.86. This frames a wide valuation gap and sets up an ambitious earnings path that needs to be understood in detail.
The analysts have a consensus price target of $287.41 for Tower Semiconductor based on their expectations of its future earnings growth, profit margins and other risk factors.
In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be $4.6 billion, earnings will come to $1.6 billion, and it would be trading on a PE ratio of 32.2x, assuming you use a discount rate of 14.4%.
See why 34 investors see Tower Semiconductor as 45% undervalued.
Result: Fair Value of $287.41 (UNDERVALUED)
Still, the Tower Semiconductor story can break if the large Japan and photonics buildouts outpace wafer demand, or if today’s premium P/E compresses on weaker sentiment.
Find out about the key risks to this Tower Semiconductor narrative.
Another View: What Tower Semiconductor’s P/E Is Really Saying
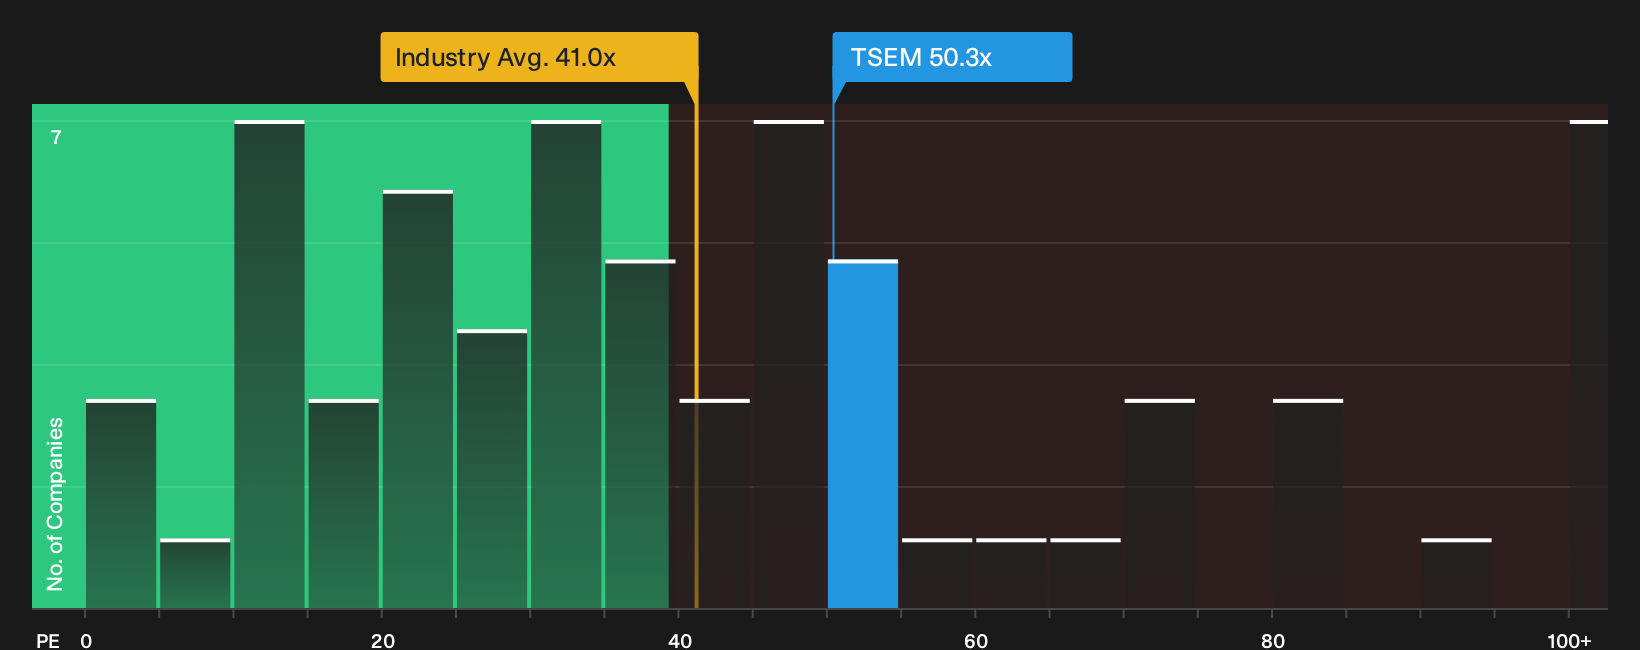
The analyst narrative focuses on a rich long term earnings path. A second lens looks at what investors currently pay for those profits. Tower Semiconductor trades on a P/E of 50.3x, which is lower than the peer average at 77.3x and close to a fair ratio of 53.5x. That mix of cheaper than peers but above the industry at 41x suggests some room for upside if the market leans toward the fair ratio, and also clear downside if sentiment shifts back to the broader sector level. Which side of that trade off are you more comfortable with?
For a closer look at how these P/E gaps compare with peers and the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Tower Semiconductor for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or clear opportunity? Take a moment to review the full data set, weigh the setbacks against the upside, and see the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Tower Semiconductor?
If you stop with Tower Semiconductor, you miss a broader field of opportunities that could fit your goals better than a single high profile stock.
- Target quality at a discount by scanning companies on our 32 high quality undervalued stocks that pair strong fundamentals with prices that trail their assessed worth.
- Protect your downside first and build around strength using a 29 resilient stocks with low risk scores that highlights businesses with sturdier balance sheets and more measured risk profiles.
- Get ahead of the crowd and focus on tomorrow's potential leaders with a 20 high quality undiscovered gems before they move onto everyone else's radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com