


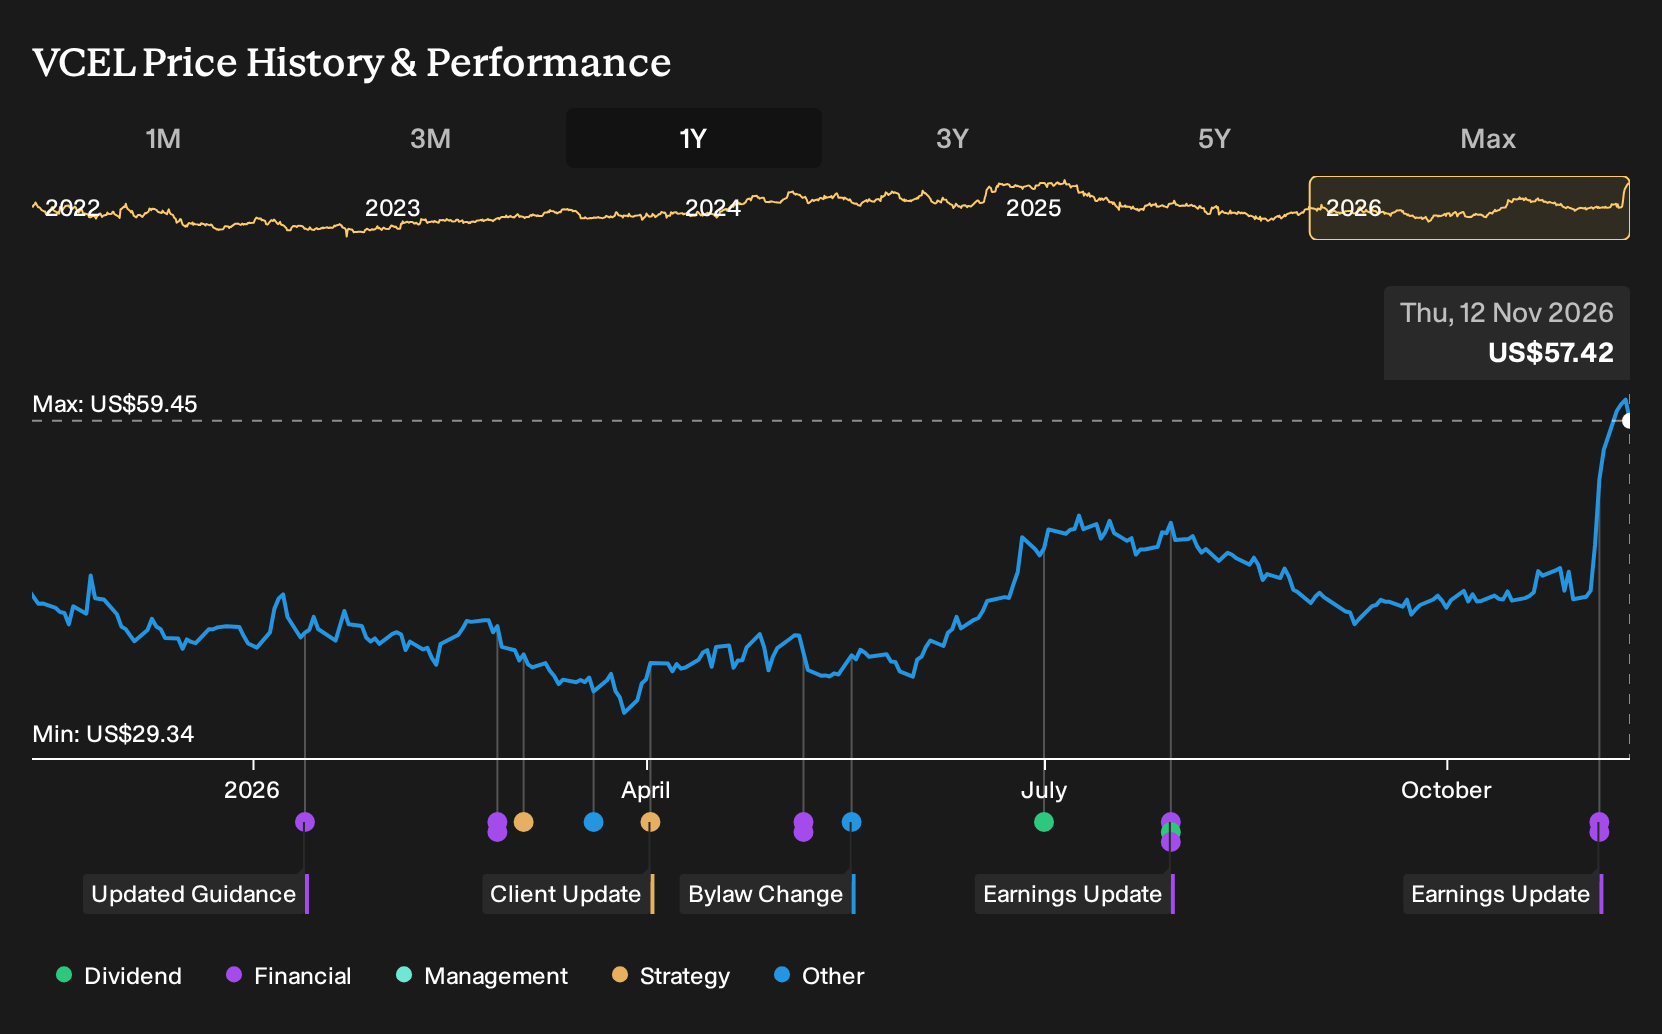
- Vericel reported third quarter 2026 revenue of US$85.37 million and net income of US$14.16 million, and raised full year revenue guidance to US$344 million to US$346 million.
- The shift from a year to date net loss in the prior period to net income in 2026, alongside share repurchases, highlights management’s focus on profitability and capital return during a heavy investment phase.
- We will now look at how Vericel’s raised 2026 revenue guidance shapes the existing investment narrative around MACI and Burn Care.
Compare Vericel’s profitability pivot with other financially resilient players by scanning our hand picked 29 resilient stocks with low risk scores designed to balance growth potential with lower risk profiles.
Vericel Investment Narrative Recap
To own Vericel, you need to believe MACI and Burn Care can keep gaining traction with surgeons while the expanded manufacturing and sales footprint stays well used. The analyst consensus Narrative on Simply Wall St leans on that idea, with higher biopsy and implant volumes absorbing 2026’s heavier fixed cost base and supporting earnings growth.
The near term swing factor is whether procedure demand for MACI and NexoBrid holds up as Vericel exits this transition year. The key risk is that volumes or pricing soften against those higher costs, which would pressure adjusted EBITDA margins and challenge expectations embedded in the current share price.
The raised 2026 revenue guidance to US$344 million to US$346 million is the announcement that ties everything together. Management pointed to third quarter performance and a strong start to the fourth quarter for both MACI and Burn Care, which directly touches the core thesis that these platforms can support higher cash generation over time.
For catalysts, that guidance update gives investors a fresh reference point to test against the analyst consensus Narrative on Simply Wall St. Execution now needs to show that surgeon adoption, Burn Care volumes and the Burlington facility can sustain this higher revenue bar without eroding profitability, especially given the current P/E premium to biotech peers.
Vericel’s current analyst script points to forecast revenue of US$508.5 million and earnings of US$93.3 million by 2029, based on an assumed 16.2% yearly revenue growth rate and an expected rise in earnings of about US$60 million from US$33.3 million today.
Uncover why Vericel's fair value indicates a 4% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Vericel’s potential MACI expansion outside the U.S., including a targeted U.K. launch and a MACI Ankle market they size above US$1b. Before this earnings release, that bullish group was already modeling about US$516.5 million of revenue and US$110.5 million of earnings by 2029. Their view could shift again once this new guidance is fully factored in. Treat it as one of several competing storylines to test rather than a blueprint.
Explore 2 other Vericel fair value estimates, including one that suggests potential upside of up to 14% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment results often come from independent thinking, so consider doing your own research.
- A great starting point for your Vericel research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Vericel. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Vericel's overall financial health at a glance.
Looking for more investment ideas beyond Vericel?
Once you have a view on Vericel, it can help to cross check that thesis against other opportunities with different risk and income profiles using the Simply Wall St Screener.
- If capital preservation is your priority, start with a set of resilient businesses by scanning a curated 29 resilient stocks with low risk scores that focuses on stability and lower downside risk.
- For investors hunting for mispriced opportunities, compare Vericel with a 32 high quality undervalued stocks that blend healthy cash flows with balance sheets that can support future growth.
- If portfolio income matters most, line up Vericel beside a 6 dividend fortresses that aim to combine yield above 5% with durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com