


- Pan Pacific International Holdings reported first quarter results for the period ended September 30, 2026, with sales of ¥649,283 million, net income of ¥27,630 million, and basic earnings per share from continuing operations of ¥9.15.
- The retailer paired higher top line performance with slightly softer net income and earnings per share, which highlights potential pressure from costs, mix, or other operating factors even as demand supports higher sales.
- We will now look at how Pan Pacific International Holdings' investment narrative could be affected by higher sales alongside softer earnings per share.
What Is Pan Pacific International Holdings' Investment Narrative?
To own Pan Pacific International Holdings, you need to be comfortable with a retailer that is still growing its top line while accepting some earnings noise in the short term. The latest quarter fits that pattern. Sales moved to ¥649,283 million, yet net income and earnings per share were slightly softer than a year ago. That combination points to execution questions around costs, assortment, or store level efficiency rather than a demand problem, especially with earnings quality flagged as high and profit growth running ahead of the 5 year average.
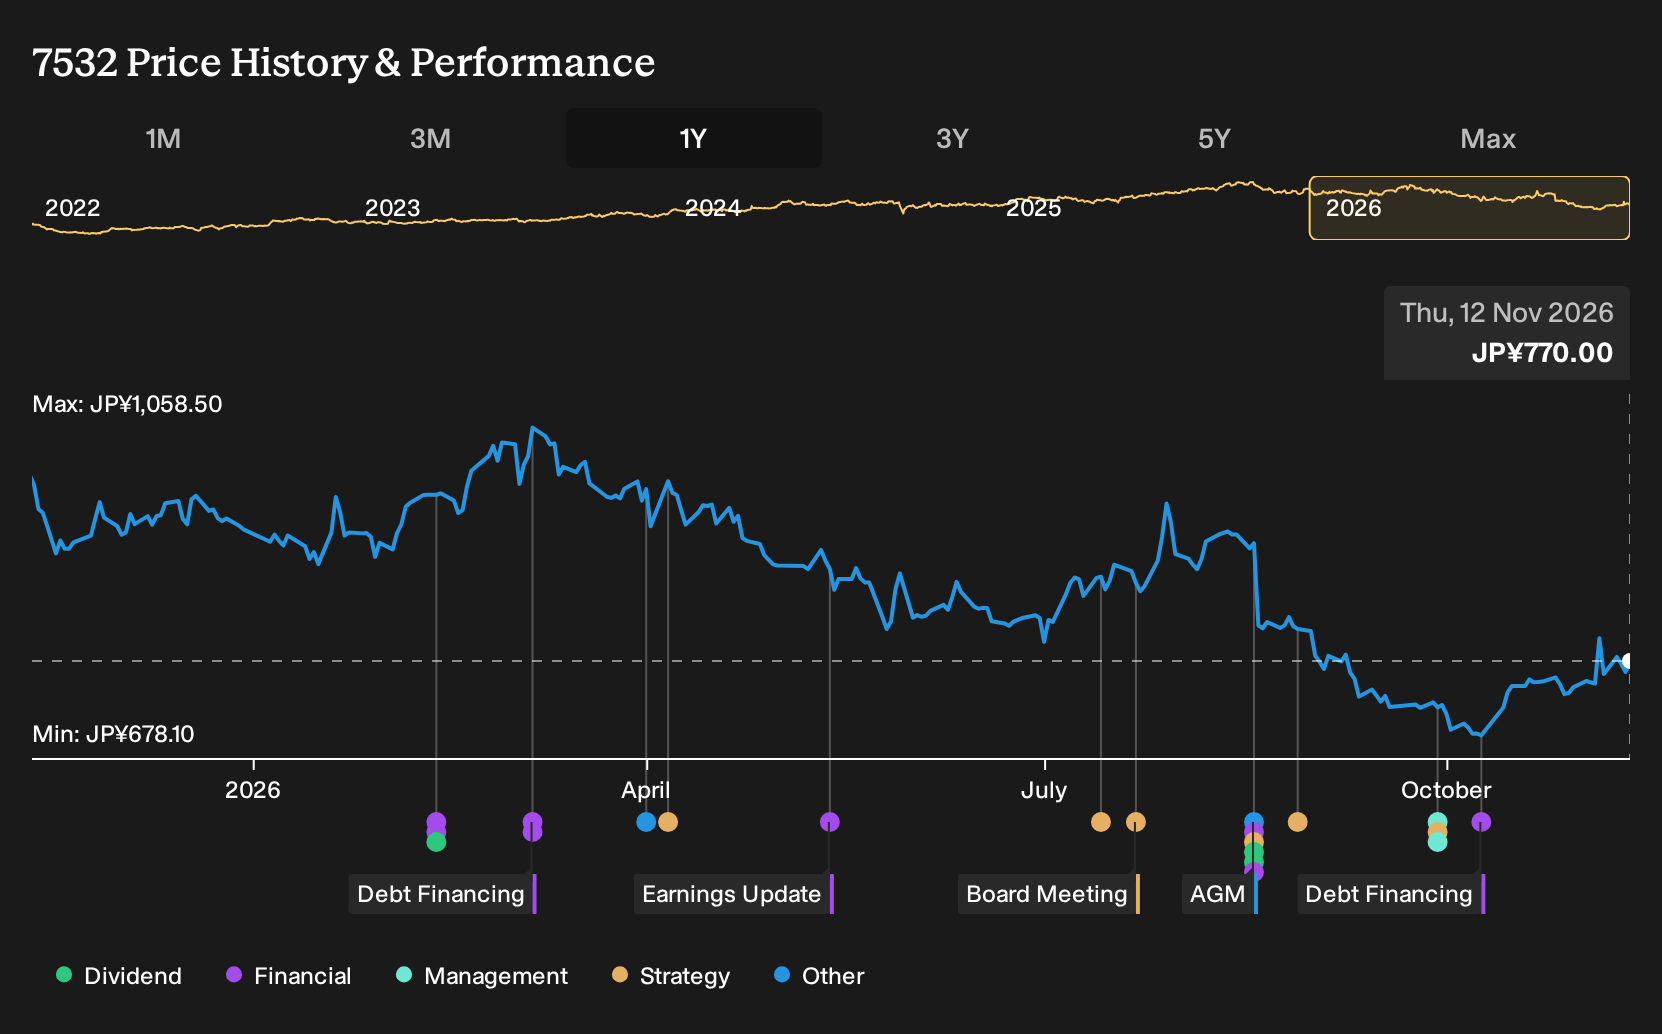
In the short term, the key swing factors are how effectively management manages expenses, keeps pricing sharp across Japan and North America, and funds growth when 100% of liabilities come from higher risk borrowing. The share price has fallen about 19% over the past year even as analysts see upside and earnings are forecast to grow 7.5% a year. That mix means the latest quarter does not break the Pan Pacific International Holdings story, but it does raise the bar for cleaner execution into upcoming results.
Yet there is still a structural issue in the background that could matter far more if...
There's only one way to know the right time to buy, sell or hold Pan Pacific International Holdings. Head to Simply Wall St's company report for the latest analysis of Pan Pacific International Holdings's Fair Value.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Pan Pacific International Holdings research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Pan Pacific International Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Pan Pacific International Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Pan Pacific International Holdings?
If Pan Pacific International Holdings has you thinking about where else to allocate capital, it can help to line it up against a wider field of stocks with different strengths. The Simply Wall St Screener lets you filter for specific traits so you can build a watchlist that matches your own risk appetite and income goals.
- For steadier balance sheets and fewer financial surprises, start with companies that show strong fundamentals and prudent leverage through our list of solid balance sheet and fundamentals (25 results).
- If resilience and capital preservation matter most to you, focus on businesses that screen well on risk metrics by reviewing the 20 resilient stocks with low risk scores.
- To cast a wider net across underfollowed opportunities with solid underpinnings, sift through the 74 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com