


Concentra Group Holdings Parent (CON) just packed several shareholder updates into one week, combining third quarter earnings, a new dividend declaration, fresh guidance and a larger share repurchase program.
The recent flurry of updates from Concentra Group Holdings Parent lands after a powerful run in the shares, with a 30-day share price return of 14.76% and a 90-day gain of 21.34% contributing to a 121.48% year-to-date share price return and 123.60% total shareholder return over 1 year. This pattern suggests that momentum has been building as investors reassess both growth potential and risk around the story.
Scan how Concentra Group Holdings Parent compares to other healthcare operators showing strong momentum and fundamentals with the hand picked list of solid balance sheet and fundamentals (23 results).
After a 121% year to date surge and fresh buyback and dividend news, Concentra Group Holdings Parent now forces a timing call. Is it worth paying up today or waiting for a cooler entry point as the valuation case unfolds next?
Most Popular Narrative: 2.7% Undervalued
On the analyst consensus Narrative on Simply Wall St, Concentra Group Holdings Parent screens as slightly undervalued, with a fair value estimate of $44.20 versus the latest close at $42.99. This puts only a small gap between model and market and frames a very modest valuation edge.
The analysts have a consensus price target of $44.2 for Concentra Group Holdings Parent based on their expectations of its future earnings growth, profit margins and other risk factors.
In order for you to agree with the analysts, you would need to believe that by 2029, revenues will be $2.8 billion, earnings will come to $269.6 million, and it would be trading on a PE ratio of 24.7x, assuming you use a discount rate of 7.3%.
See why 3 investors see Concentra Group Holdings Parent as 3% undervalued.
Result: Fair Value of $44.20 (UNDERVALUED)
Still, the Concentra Group Holdings Parent story can break if acquisition related costs keep margins tight, or if high leverage limits flexibility just when volumes soften.
Find out about the key risks to this Concentra Group Holdings Parent narrative.
Another View: Concentra Group Holdings Parent Looks Expensive On Earnings
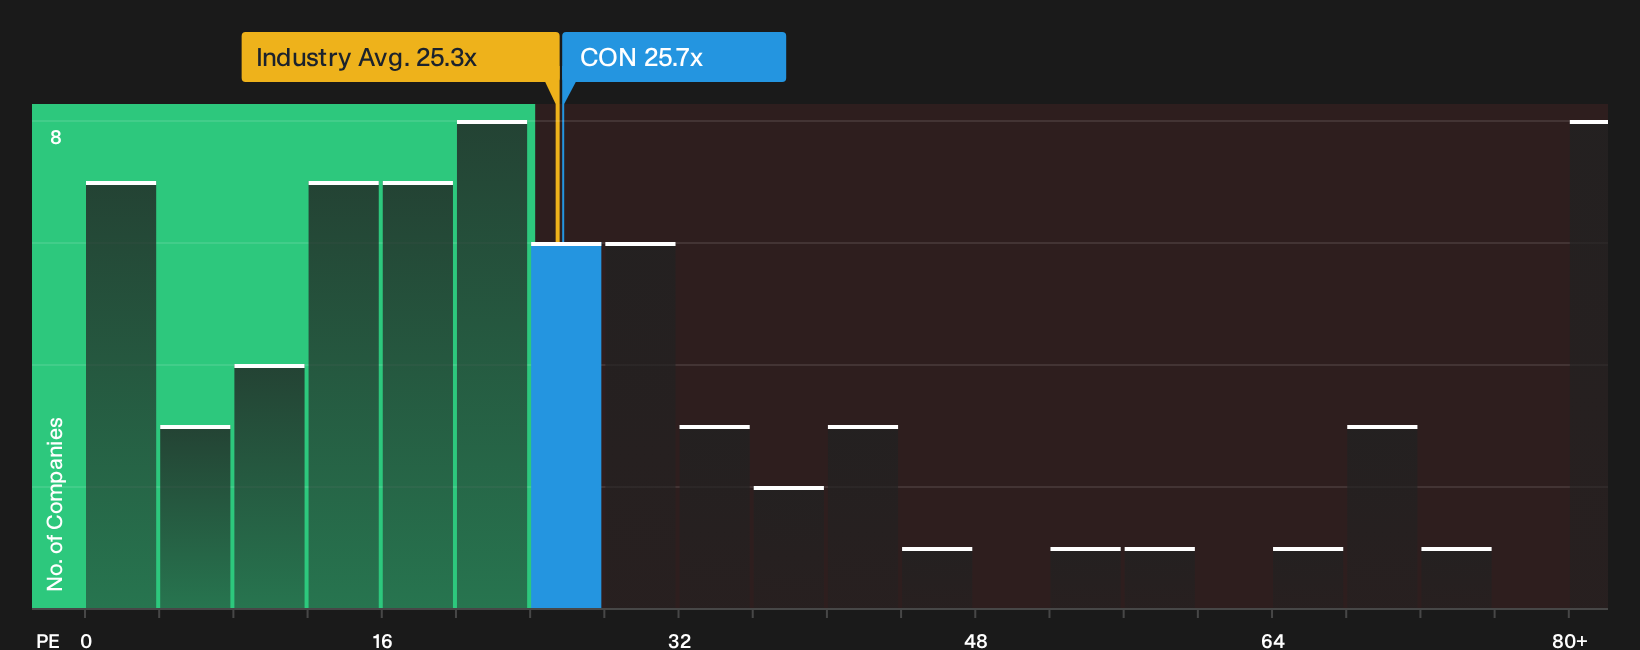
The analyst narrative frames Concentra Group Holdings Parent as modestly undervalued, yet the P/E story pulls in the opposite direction. At 25.7x earnings versus 25.3x for the broader US Healthcare group and 22.7x for peers, the stock carries a clear premium.
The fair ratio sits even lower at 23.6x. That implies investors today are paying ahead of both the sector and the level the market could eventually gravitate toward. This raises the question: is this simply the price of quality earnings and recent momentum, or extra valuation risk if sentiment cools?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Concentra Group Holdings Parent story so far. Act while sentiment is split and build your own view from the ground up with 3 key rewards and 1 important warning sign.
Looking for more Concentra Group Holdings Parent style investment ideas?
If Concentra Group Holdings Parent has sharpened your focus, do not stop here. Broaden your watchlist now so you are not late to the next setup.
- Target resilient balance sheets and steady fundamentals by reviewing the list of solid balance sheet and fundamentals (23 results) that filters for financial strength before excitement.
- Zero in on value driven opportunities by scanning the 32 high quality undervalued stocks that highlights companies where quality and pricing still appear misaligned.
- Build a cash flow focused watchlist by checking the 6 dividend fortresses that surfaces payout heavy businesses offering higher income potential.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com