


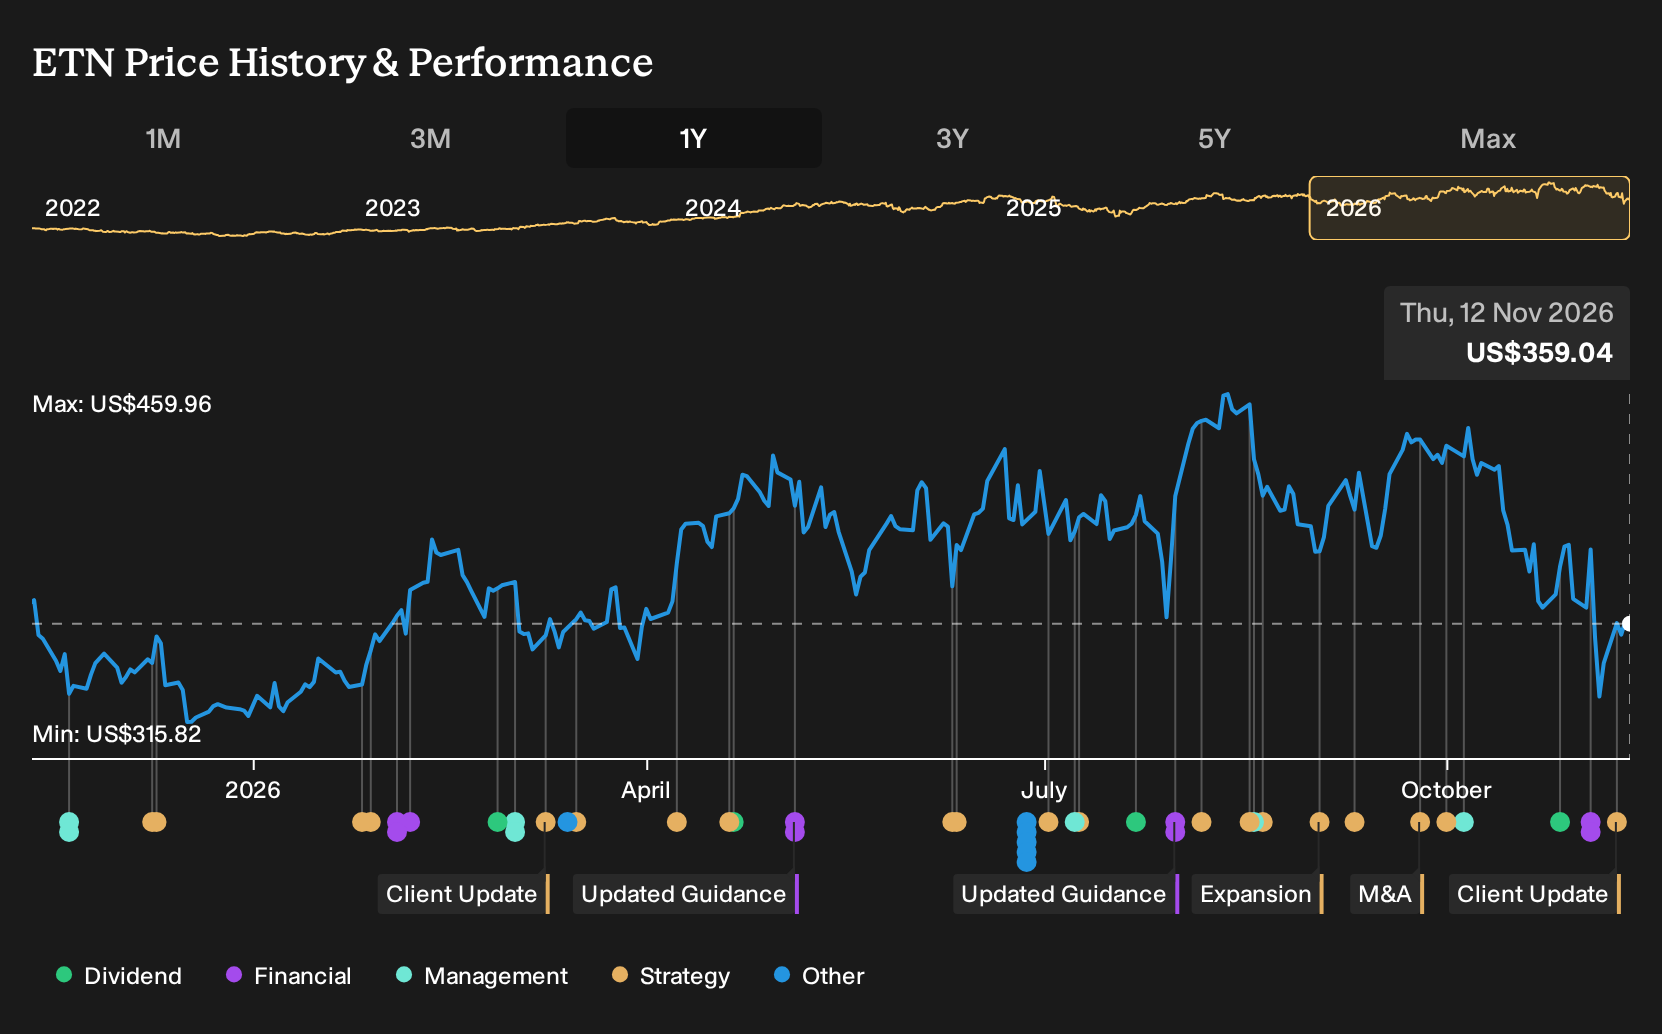
- Eaton reported record third quarter 2026 sales of US$8,947 million and issued higher full year earnings guidance, while addressing recent gross margin pressure from commodity costs and factory expansions.
- Dassault Aviation’s selection of Eaton hydraulic power and fuel systems for the Falcon 10X highlights how the aerospace unit is winning high value roles on next generation platforms.
- The focus now turns to how Eaton's record quarterly sales and guidance update relate to the existing Physical AI infrastructure investment narrative.
Eaton Investment Narrative Recap
To own Eaton, you need to be comfortable with a power and aerospace supplier that is leaning hard into grid, data center and aviation programs, while absorbing short term margin pressure from higher input costs and factory projects. The recent record quarter and higher earnings guidance speak to scale, but the more immediate swing factor is how quickly gross margins rebuild as pricing and capacity actions feed through.
The biggest operational risk right now sits around execution on that expansion program and managing a high debt load while funding Physical AI infrastructure and Boyd Thermal integration, as Composite_Research, an investor in the Simply Wall St Community, highlights. If the current gross margin headwinds prove stickier than management expects, or large projects are delayed, the share price pullback may simply reflect a longer digestion phase rather than a clear catalyst.
The most relevant update for this story is Eaton’s new full year 2026 earnings guidance of US$10.39 to US$10.49 in net income per diluted share and its fourth quarter range of US$3.28 to US$3.38. Those figures provide a concrete yardstick for assessing how the Physical AI and power grid thesis is translating into actual profitability while commodity costs and plant ramps remain in the mix.
Viewed against Composite_Research’s Physical AI narrative, that guidance is where the rubber meets the road. It links the massive order book and Boyd Thermal acquisition back to near term execution, and it also frames how much room Eaton has to keep investing in capacity, service its higher debt and sustain its long dividend track record if industrial demand cools or transformer bottlenecks ease faster than expected.
Composite_Research’s narrative arrives at a fair value of US$517.06 per Eaton share by applying its own weighted DCF and comps model to a scenario that assumes 11.0% annual revenue growth and a future profit margin of 17.9%. This reflects how Physical AI infrastructure and aerospace exposure feed into long term earnings power.
Discover how Eaton's fair value indicates a 44% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bearish twist you should weigh is capacity risk. The lowest analysts worried that Eaton could build too much Electrical Americas and Boyd-related capacity if AI and data center orders slow, and they were only penciling in revenue of about US$40.6b and earnings of US$6.6b by 2029. That is a far more cautious story than Composite_Research’s Physical AI view, and both were written before this Falcon 10X win and the record quarter, so you may see those projections shift as fresh data filters through.
Explore 6 other Eaton fair value estimates, including one that suggests it could be worth just $351.55.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Eaton research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Eaton. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Eaton's overall financial health at a glance.
Looking for more Eaton-adjacent investment ideas?
If Eaton has sharpened your focus on power, infrastructure and dependable cash generation, it can help to widen the lens and compare it with other listed businesses that share some of those qualities. The Simply Wall St Screener lets you quickly filter the market by factors like valuation, balance sheet strength and income profile so you can build a watchlist that actually fits your own risk and return preferences.
- For investors hunting for quality at a reasonable price, start with companies that combine solid fundamentals with undemanding valuations using our curated 32 high quality undervalued stocks.
- If consistent income matters to you as much as Eaton's profile, focus on resilient payers with higher yields by scanning our hand picked 6 dividend fortresses.
- When capital preservation takes priority, look for businesses with stronger finances and lower risk scores through the Simply Wall St 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com