


Target Hospitality (TH) just put fresh numbers on the table, with third quarter results and full year 2026 revenue guidance reaffirmed in a range between US$435 million and US$445 million.
The guidance update lands after a sharp reset in sentiment, with a 30-day share price return of down 36% and a 90-day move of down 31.31%, even though the 1-year total shareholder return of 92.6% and 5-year total shareholder return of 193.63% point to a story that has rewarded patient holders. Recent momentum has faded as investors reassess both growth potential and risk around Target Hospitality.
Spot opportunities around Target Hospitality's reset by scanning a curated 20 high quality undiscovered gems with similar fundamentals that may be flying under most investors' radar.After a slide that wiped a third off Target Hospitality’s value in a month, even as revenue guidance held steady, the real tension now sits in the valuation. Do current prices still compensate you for the risks?
Most Popular Narrative: 52% Undervalued
At a last close of $11.98 against a fair value estimate of $25.20 from the analyst consensus Narrative on Simply Wall St, Target Hospitality screens as heavily discounted on that framework, with the gap resting on how much faith you place in long term Workforce Housing Solutions contracts and the capital being committed to them.
The main thing that has to go right is Target Hospitality successfully executing its pivot toward WHS communities for AI, power, and critical infrastructure customers, while managing transitional costs and maintaining margins during heavy growth capex.
The current valuation implies the market does not fully credit Target Hospitality for its contracted WHS and government revenue base and the capital it is deploying into long-duration workforce housing tied to AI and power infrastructure.
See why 2 investors see Target Hospitality as 52% undervalued.
Result: Fair Value of $25.20 (UNDERVALUED)
Still, heavy WHS focused capex funded by the US$660m credit facility and recent net losses show that execution or utilization missteps could quickly challenge the bullish narrative.
Find out about the key risks to this Target Hospitality narrative.
Another View: Target Hospitality Through The P/S Lens
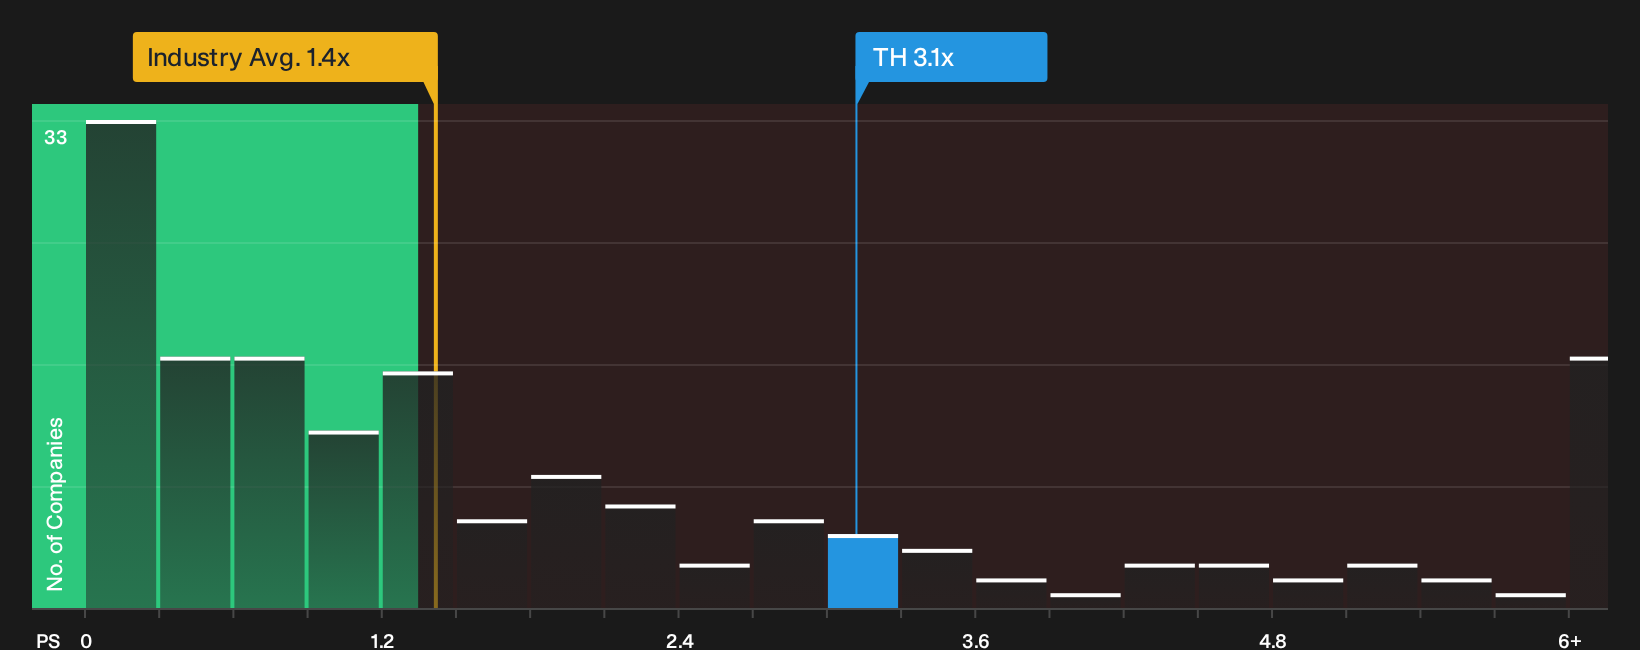
The first fair value story presents Target Hospitality as heavily discounted, yet the simple sales multiple offers a different perspective. The stock trades on a P/S of 3.1x compared with 1.5x for the US Hospitality group and 1.1x for peers, while the fair ratio sits at 3.2x. That gap suggests investors already pay a premium to the sector, even if it roughly aligns with the fair ratio. This raises the question of how comfortable investors are anchoring on a relatively high sales multiple for a business that is still loss making.
For a closer read on how those sales multiples compare with cash flow assumptions and scenario tests, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Target Hospitality is split, with both concern and optimism showing up in the data. Investors may want to move quickly, review the evidence, and weigh the 3 key rewards and 2 important warning signs.
Looking for more Target Hospitality style ideas?
If you stop with Target Hospitality, you miss a wider field of potential opportunities that match different goals, risk levels, and income needs across your portfolio.
- Target potential bargains early by reviewing the 20 high quality undiscovered gems that combine strong fundamentals with limited market attention.
- Strengthen your portfolio’s foundation through a list of solid balance sheet and fundamentals (23 results) that highlights businesses with healthier finances and less stressed capital structures.
- Build a stream of income today by screening for 6 dividend fortresses that pair higher yields with a focus on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com