


Earnings spike puts Astrana Health in focus
Astrana Health (ASTH) is back on investors’ radar after reporting third quarter net income of US$12.95 million, compared with US$0.373 million a year earlier, alongside higher earnings per share from continuing operations.
The strong profit update arrived in a weak overall market. Astrana Health’s share price has fallen 18.6% over the past week and 22.2% over three months, yet the year-to-date share price return is up 26% and the 1-year total shareholder return is 45%. This points to solid long-term gains but fading short-term momentum as investors reassess how sustainable these earnings look at a US$31.77 share price.
Spot 32 high quality undervalued stocks that, like Astrana Health after this earnings jump, pair improving profitability with balance sheets that can support the next leg of their share price story.Astrana Health now appears to be a much more profitable enterprise, yet the share price has pulled back sharply following that earnings release. Is this a strong healthcare platform being offered at a fair valuation, or is the valuation already full?
Most Popular Narrative: 39% Undervalued
Against Astrana Health’s last close at $31.77, the analyst consensus Narrative on Simply Wall St anchors fair value closer to $51.67. This frames this latest earnings jump inside a much bigger cash flow and risk story.
The main thing that has to go right is that Astrana Health continues to convert and manage more members in full-risk arrangements while its AI-enabled operating system keeps driving G&A efficiency, free cash flow generation, and successful integration of deals like Prospect despite ongoing Medicaid churn and cybersecurity scrutiny.
The current valuation implies that the market is discounting the durability of Astrana Health’s AI-native platform, full-risk value-based care mix, and free cash flow profile. This is consistent with this narrative’s view that the stock is undervalued and that execution on these fronts is not fully reflected in the share price.
See why 6 investors see Astrana Health as 39% undervalued.
Result: Fair Value of $51.67 (UNDERVALUED)
Still, that story can unravel quickly if reimbursement on Medicare and Medicaid tightens or if large deals like Prospect fail to deliver expected efficiencies.
Find out about the key risks to this Astrana Health narrative.
Another View: Astrana Health On Earnings Multiples
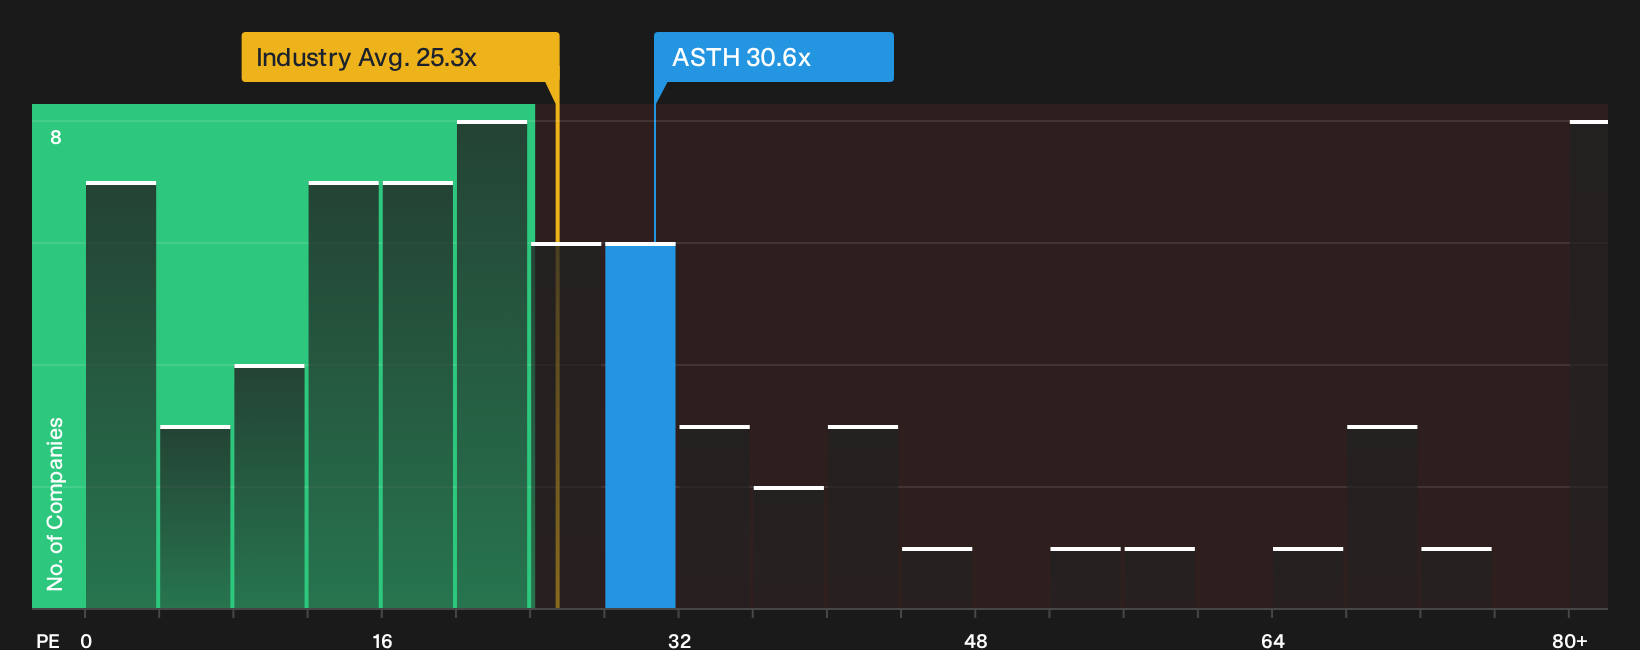
The DCF work suggests Astrana Health looks cheap, trading at about a 75% discount to an estimated future cash flow value of $128.80. On a simpler lens, the P/E ratio of 30.6x is higher than the US Healthcare sector on 25.3x, yet below peers on 40.6x and only slightly under a fair ratio of 34.2x. That mix of signals raises a basic question for you as an investor. Is this a margin-of-safety opportunity or just a full price for a fast improving story?
To pressure test that question against hard numbers rather than headlines, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Astrana Health story so far. Act quickly, look through the data, weigh the upside against the downside, and ground your view in the 4 key rewards and 2 important warning signs.
Looking for more Astrana Health style opportunities?
If Astrana Health has your attention, do not stop here. Broaden your watchlist now with focused idea lists that could surface your next key holding.
- Target improving quality by reviewing a curated 32 high quality undervalued stocks that combine strong fundamentals with prices that may not fully reflect their financial profile.
- Prioritise resilience and sleep better at night by scanning a 29 resilient stocks with low risk scores that screen well on balance sheet strength and risk checks.
- Hunt for future leaders early and sift through a 20 high quality undiscovered gems where solid business performance has not yet attracted broad market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com