


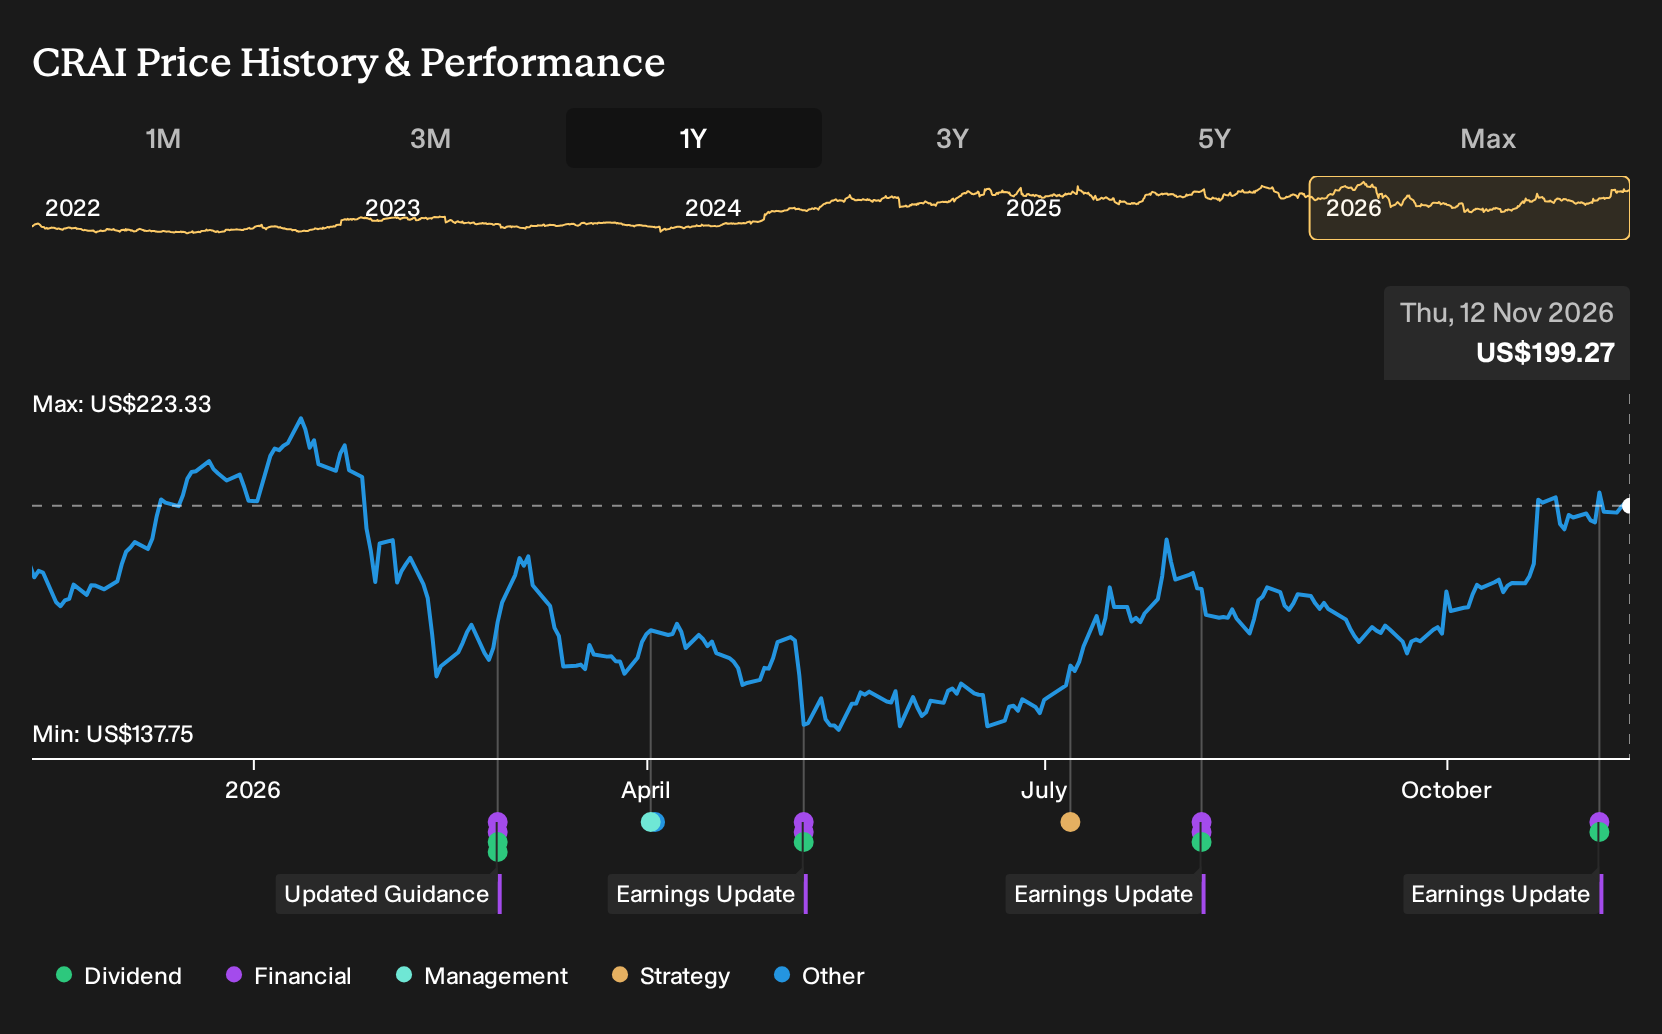
- CRA International, Inc. reported third quarter 2026 sales of US$214.92 million and net income of US$13.91 million, alongside a Board-approved quarterly dividend increase from US$0.57 to US$0.67 per share, payable in December 2026.
- The combination of higher third quarter earnings per share and a larger cash dividend signals management confidence in CRA International’s ongoing consulting demand and cash generation capacity.
- We will now examine how CRA International’s investment narrative could be influenced by strong third quarter earnings and the higher quarterly dividend.
CRA International Investment Narrative Recap
To own CRA International, you need to believe its consulting practices can keep a healthy flow of complex antitrust, M&A and regulatory work while managing a rising cost base and credit facility usage highlighted in the analyst consensus Narrative on Simply Wall St. The latest quarter shows higher sales and EPS, yet nine month earnings and margins still look pressured compared with last year.
That mix leaves the near term catalyst squarely on utilization of senior hires and case volume in key practices. The main operational risk is tied to any slowdown in deal or enforcement activity that could expose the heavier spending and debt. The fresh results and dividend move do not remove that risk, but they help frame it.
The dividend increase to US$0.67 a share is the announcement that matters most for you here because it sits on top of higher quarterly EPS and continues CRA International’s pattern of returning capital while investing in talent. For income focused holders, a higher cash payout supported by current earnings is an immediate, tangible outcome.
This higher distribution also interacts directly with the catalysts and risks already flagged. Stronger advisory activity and utilization need to cover not only senior compensation and international expansion but also a larger recurring dividend alongside debt service. If case flow or pricing weakens, management has fewer easy levers before considering slower hiring, reduced capital returns or balance sheet adjustments.
Analysts currently frame CRA International's outlook around revenues of US$902.9 million and earnings of US$72.1 million by 2029. This implies forecast revenue growth of 4.3% a year and an earnings increase of about US$22.9 million from US$49.2 million today.
Uncover why CRA International's fair value indicates a 26% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$250.5 to US$324.8 a share, so retail opinions on CRA International already cover a wide gap. Treat those pre earnings views as starting points, then weigh them against the reliance on robust M&A and enforcement activity to keep recent profit trends intact.
Explore another CRA International fair value estimate, including one that suggests as much as 63% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your CRA International research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CRA International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake. This makes it easy to evaluate CRA International's overall financial health at a glance.
Looking for more investment ideas beyond CRA International?
If CRA International has sharpened your thinking about earnings quality, cash returns and risk, you can use that same lens across a wider watchlist. The Simply Wall St Screener can help you quickly filter for stocks that better match your own income, value or capital preservation goals.
- For investors who care most about steady income, you can scan a curated set of 6 dividend fortresses that combine payout potential with balance sheet strength.
- If capital preservation ranks higher for you than fast growth, you can focus on 29 resilient stocks with low risk scores that score well on financial health and earnings stability.
- When you want quality but do not want to chase widely followed tickers, you can search through 20 high quality undiscovered gems with solid fundamentals that may not yet be on every investor's radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com