


HUTCHMED (China) (AIM:HCM) has moved back into focus after announcing that regulatory agencies in Europe and Japan accepted filings for ORPATHYS plus TAGRISSO in advanced non small cell lung cancer.
Recent trading suggests investors are reacting to these clinical milestones, with HUTCHMED (China) delivering a 1-day share price return of 1.34%, 8.10% over 7 days and 22.70% over 90 days. However, the 1-year total shareholder return is down 1.73%, and the longer term 3- and 5-year total shareholder returns remain weaker. This indicates that momentum has picked up in the short term, while the longer track record still reflects earlier challenges.
Scan how HUTCHMED (China) compares with other oncology focused plays by reviewing our curated list of 6 high quality undiscovered gems that have strong fundamentals but remain off most investors' radar.
The recent jump in HUTCHMED (China) puts the market price well below both analyst targets and intrinsic value estimates. The spread is wide. The next step is to see where fair value realistically clusters.
Most Popular Narrative: 37% Undervalued
On the analyst consensus Narrative on Simply Wall St, HUTCHMED (China) screens as materially undervalued, with a fair value of about £3.62 against the last close of £2.27. That gap rests on a detailed set of revenue, margin and earnings assumptions that investors can test for themselves.
Launches and global expansion of FRUZAQLA, including strong growth outside China (notably in Japan and anticipation of further global rollouts), position the company to capture rising healthcare spending and broader reimbursement coverage, supporting robust top-line growth.
Acceleration of the ATTC platform (Antibody-Targeted Therapy Conjugates), with imminent clinical trial initiations and a novel approach integrating small molecule and antibody expertise, is likely to boost R&D productivity and support long-term earnings growth if clinical proof-of-concept succeeds.
See why 6 investors see HUTCHMED (China) as 37% undervalued.
Result: Fair Value of £3.62 (UNDERVALUED)
Still, the HUTCHMED (China) narrative can break if key drugs face tougher pricing pressure in China, or if newer platforms fail to deliver convincing trial data.
Find out about the key risks to this HUTCHMED (China) narrative.
Another View: What HUTCHMED (China)'s P/E Is Telling You
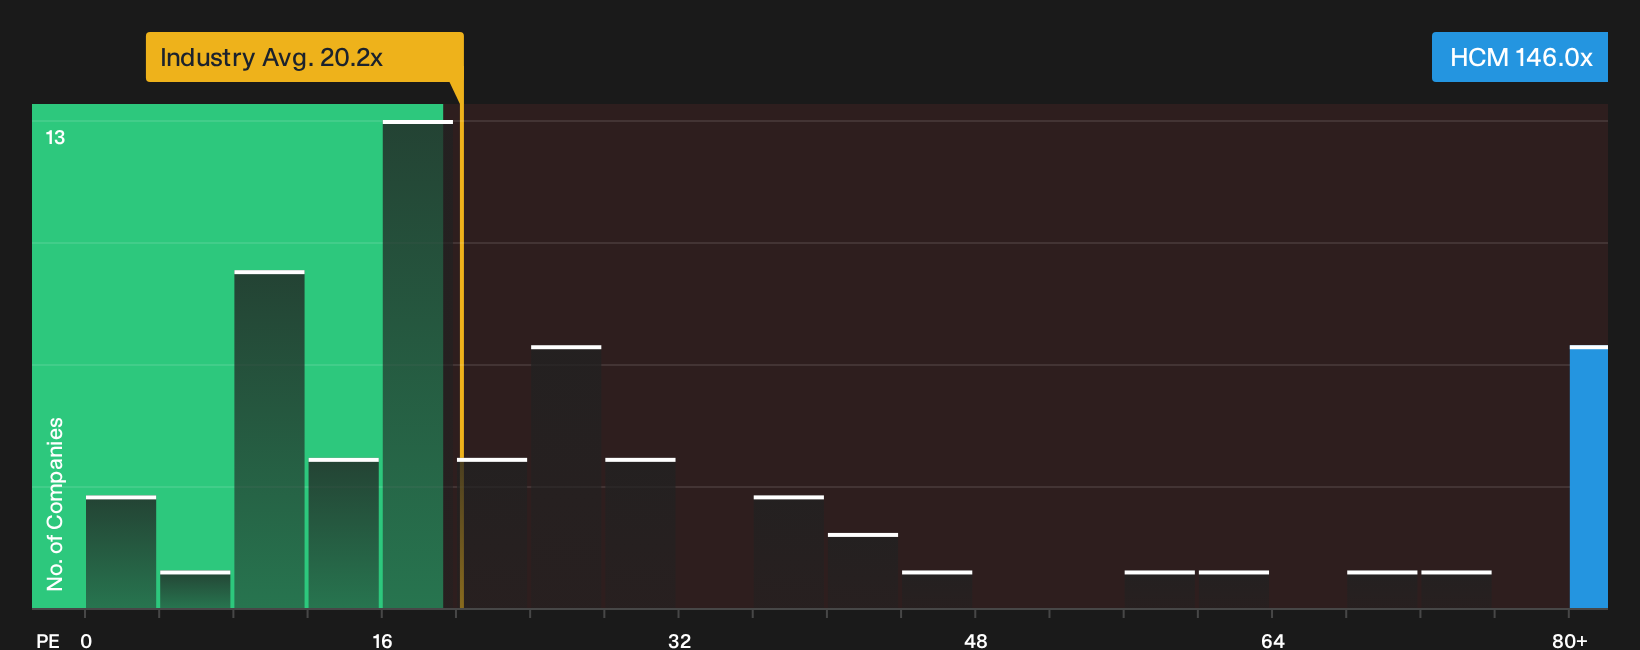
The DCF story presents HUTCHMED (China) as undervalued, yet the earnings multiple suggests a very different picture. The stock trades on a P/E of 146x, while the fair ratio is 29.6x and peers are around 18.4x. That is a steep premium. Is the market overpaying for the growth narrative?
See what the numbers indicate about this price in more detail in our valuation breakdown, starting with See what the numbers say about this price — find out in our valuation breakdown..
For a visual sense of how this earnings multiple compares with the wider sector, review the latest ratio comparison here
Next Steps
If this mix of optimism and concern around HUTCHMED (China) leaves you undecided, act promptly, examine the data yourself, and then consider 2 key rewards and 2 important warning signs carefully.
Looking for more investment ideas beyond HUTCHMED (China)?
Round out your view on HUTCHMED (China) by stress testing your thinking against other opportunities, so you are not relying on a single story or sector.
- Target resilient income by reviewing 5 dividend fortresses that aim to balance higher yields with staying power through different market conditions.
- Hunt for quality at a discount with 15 high quality undervalued stocks that pair solid fundamentals with price tags that still look reasonable.
- Prioritise capital protection by scanning 5 resilient stocks with low risk scores built to help keep volatility in check while still allowing for potential returns.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com