


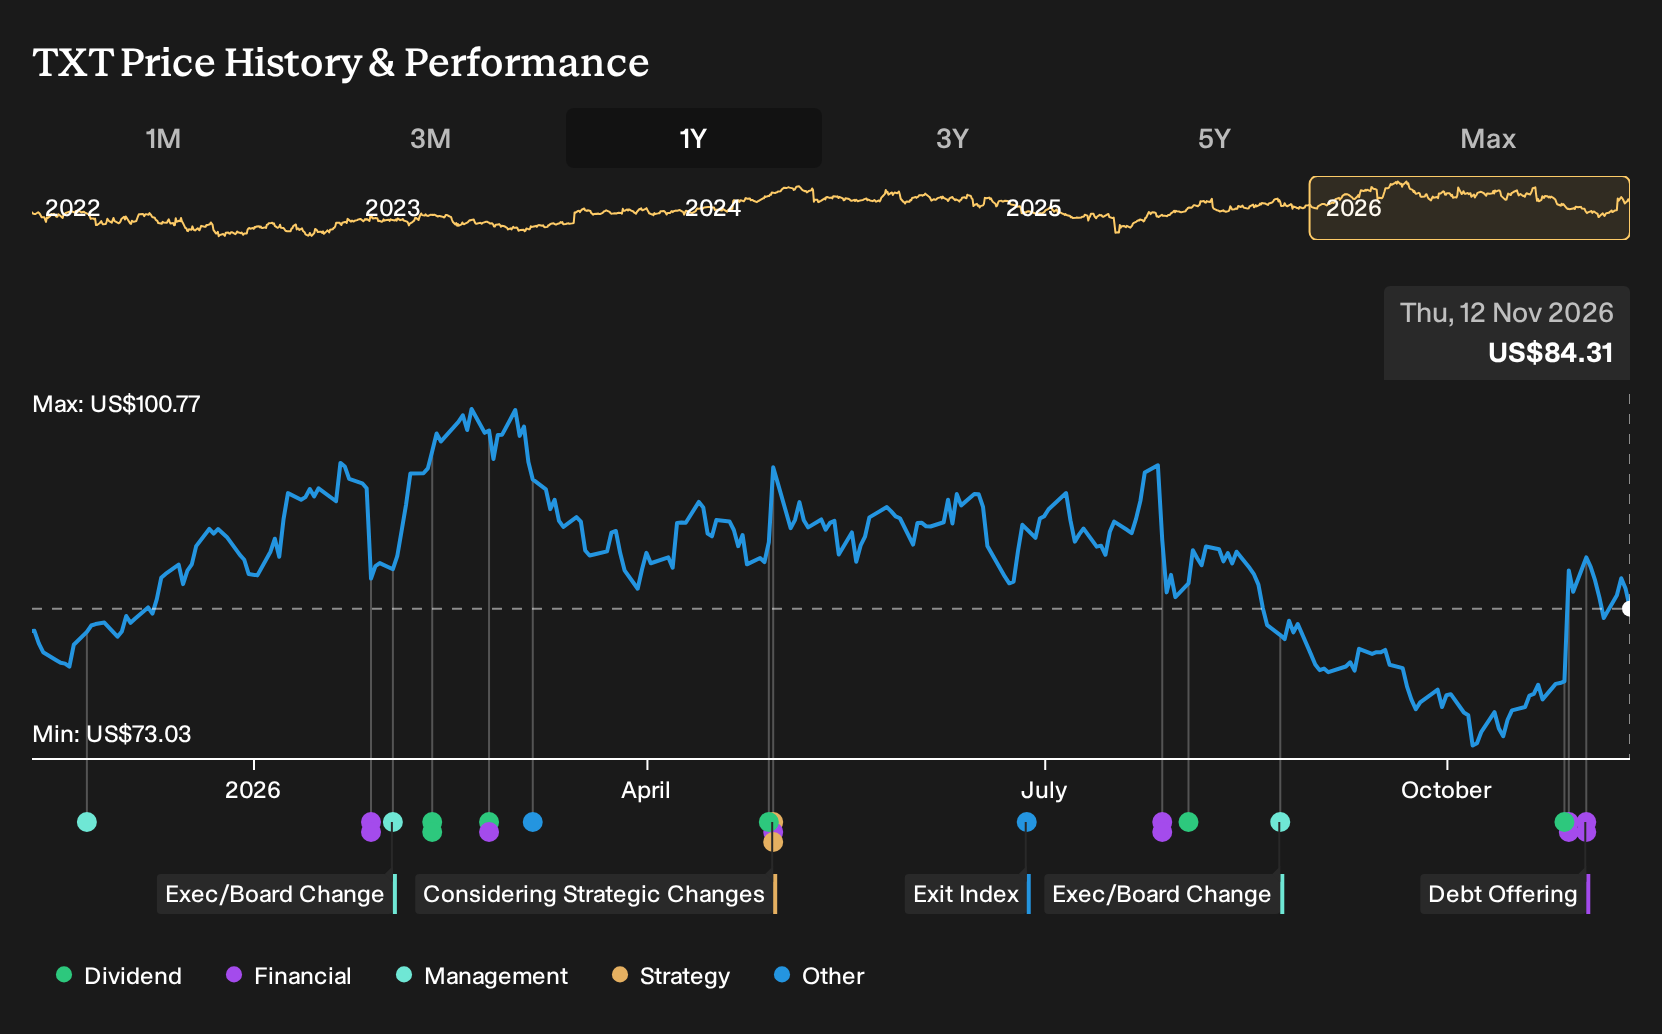
- Textron has recently completed a US$349.3 million offering of 5.500% senior unsecured fixed rate notes due March 15, 2032, adding to earlier fixed income activity that includes callable features and ongoing share repurchases.
- The combination of higher full year 2026 GAAP EPS guidance, fresh bond financing, and the planned separation of the more than US$3b Industrial segment signals a clear shift in how Textron is aligning its balance sheet with its aerospace and defense focus.
- This article will examine how Textron's investment narrative is being reshaped by higher earnings guidance supported by the new 2032 fixed rate notes.
Scan beyond Textron and compare how other capital intensive companies are repositioning for potential breakouts with our hand picked 32 high quality undervalued stocks.
Textron Investment Narrative Recap
To own Textron, you need to believe the aviation and Bell businesses can translate backlog and program wins into cleaner execution and better margins while the Industrial separation simplifies the story. The fresh 5.500% 2032 notes do not change that core requirement. They mainly clarify how the balance sheet is being shaped to support the aerospace and defense focus.
In the near term, the key catalyst is progress on aviation margin recovery and MV-75 Cheyenne funding, which links directly to earnings quality and cash generation. The biggest risk is that manufacturing inefficiencies and funding delays persist, which could compress margins and leave guidance harder to achieve even with higher EPS targets.
The most relevant recent announcement is Textron lifting full year 2026 GAAP EPS guidance to US$5.64 to US$5.74 alongside the US$349.3 million fixed rate bond issue and US$521.89 million share buyback. That combination, described in the analyst consensus Narrative on Simply Wall St, frames the new 2032 notes as one more tool to support the capital plan rather than a standalone turning point.
For catalysts, the higher guidance leans on Aviation and Bell progress, as well as expected benefits from the Industrial separation and margin work, including the targeted roughly US$150 million aviation profit opportunity. Against that, execution on MV-75 Cheyenne funding and the eventual catch up charge still sit as meaningful swing factors for short term earnings and cash flow delivery.
Textron's narrative projects US$16.8b revenue and US$1.2b earnings by 2029. That path assumes 3.1% yearly revenue growth and an earnings increase of about US$261m from the current US$939.0m level.
Uncover why Textron's fair value indicates a 20% potential upside to its current price before the discount begins to close.
Exploring Other Perspectives
One alternate Textron story puts far more weight on the Aviation backlog as a potential upside swing factor. Those bullish analysts were already pencilling in about US$18.1b of revenue and US$1.3b of earnings by 2029 before this new bond deal. That more optimistic view could shift again once the fresh funding move is fully digested.
Explore 4 other Textron fair value estimates, including one that suggests as much as 58% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Textron research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Textron. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Textron's overall financial health at a glance.
Looking For More Investment Ideas Beyond Textron?
Once you have a working view on Textron, it often helps to widen the lens and compare it with other opportunities that share similar financial traits or risk profiles. The Simply Wall St Screener can narrow that universe quickly so you spend time assessing candidates, not just hunting for them.
- If you want balance sheet strength to be non negotiable, start with companies that feature a list of solid balance sheet and fundamentals (23 results) and see which ones line up with your risk tolerance.
- For investors who care most about durable income, focus on steady payers by reviewing our hand picked 6 dividend fortresses that match your yield and stability preferences.
- If you are hunting for underappreciated opportunities with quality fundamentals, filter the market using our curated 20 high quality undiscovered gems and build a watchlist for your next round of research.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com