


Sputtering targets are core consumables for thin film deposition processes such as semiconductors, displays, and photovoltaics. In recent years, benefiting from the wide application of sputtering film materials in semiconductor integrated circuits, information storage, etc., market demand for sputtering targets has continued to expand. Zhitong Finance notes that judging from the competitive pattern, the global sputtering target industry shows typical characteristics of high concentration. Japanese companies such as Tosoh and Honeywell have dominated the position for a long time, and Jiang Feng Electronics (300666.SZ), which has just submitted a listing application to the Hong Kong Stock Exchange, is one of the few Chinese manufacturers that have squeezed into the first tier of the industry. According to the company's prospectus, based on revenue in 2025, Jiang Feng Electronics ranked second among global suppliers of ultra-high purity metal sputtering targets, with a global market share of 10.3%.
Looking at the current time point, Jiang Feng Electronics can be said to have broken through the Hong Kong Stock Exchange with excellent performance. The data shows that over the past few years, Jiang Feng Electronics' revenue and profit have maintained a rapid growth trend. In the first 9 months of this year, the company's revenue was 4.465 billion yuan, up 35.67% year on year; net profit to the mother was 811 million yuan, up 102.38% year on year; in the Q3 single quarter, the company's revenue was 1,728 million yuan, up 44.42% year on month; net profit surged 83.2% year on year; during the same period, the company's net profit without return to mother was 227 million yuan, and the year-on-year increase was as high as 94.23% and 182.11%.
Steady performance is undoubtedly the strongest motivation for Jiang Feng Electronics to sprint to the Hong Kong Stock Exchange, and once the Hong Kong stock listing is completed in the future, the A+H dual platform layout may open up a new level of narrative. At that time, the company's investment value is expected to be more fully appreciated by international investors.
The resonance between the main industries of targets and components stimulates growth momentum
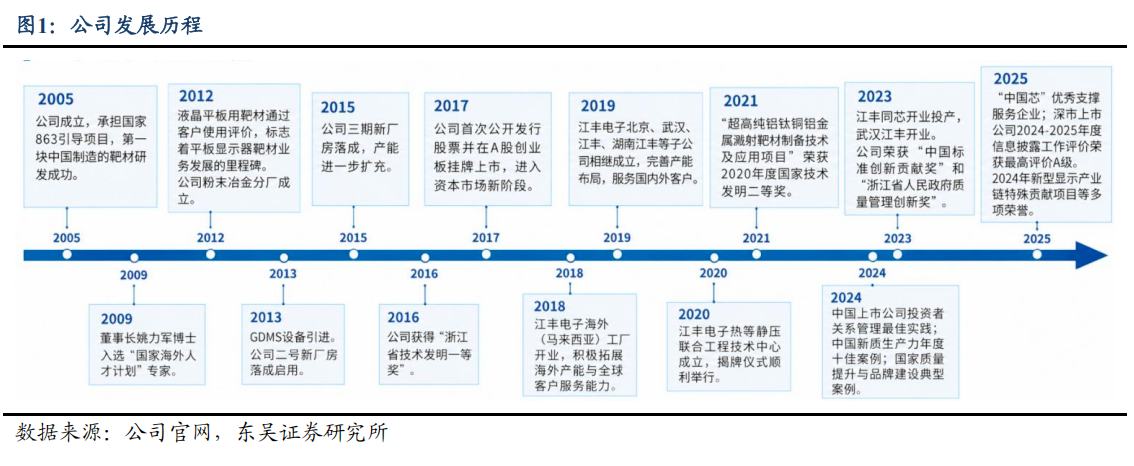
The history of Jiang Feng Electronics can be traced back to 2005. According to information, at the beginning of its establishment, the company undertook projects related to the national “863 Plan” and achieved breakthroughs in independent research and development of domestic sputtering targets. After more than 20 years of development, the company has grown from a single target supplier to a semiconductor material platform enterprise with the dual main business of “target materials+components”.
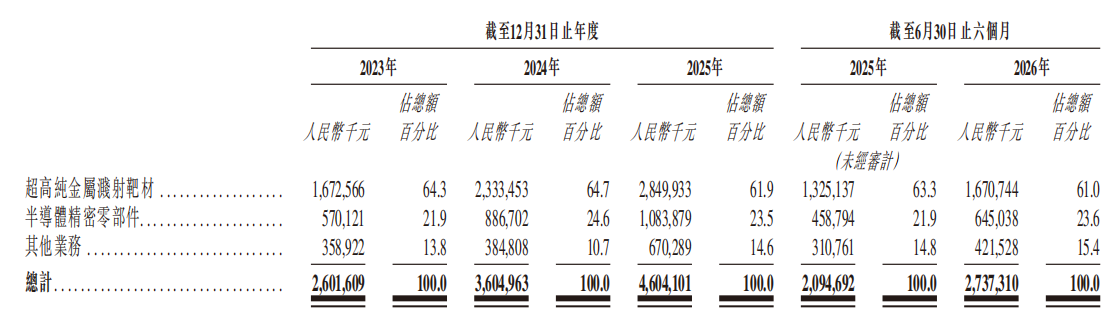
Looking back on the track record, Jiang Feng Electronics' revenue has continued to grow rapidly over the years. In 2023-2025, Jiang Feng Electronics' revenue was 2,602 billion yuan, 3.65 billion yuan, and 4.604 billion yuan respectively, with a compound annual growth rate of 33% during the corresponding period.
Looking at the split revenue structure, ultra-high purity targets have always been the basic market for Jiang Feng Electronics. In 2023-2025, the business's revenue share stabilized at more than 60%, and achieved revenue of 2,850 billion yuan in 2025, an increase of 22.1% over the previous year. According to reports, Jiang Feng Electronics' product line covers the five major metal systems of aluminum, titanium, tantalum, copper, and tungsten. Among them, high-end categories such as tantalum targets and copper-manganese alloy targets have been applied in batches to advanced process nodes, and customers cover many of the world's leading fabs.
As the second growth curve for components, the pace of volume release is also clear. According to the data, Jiang Feng Electronics' semiconductor precision components business revenue increased from 570 million yuan in 2023 to 1,084 billion yuan in 2025, and further achieved revenue of 645 million yuan in the first half of 2026, an increase of 40.59% over the previous year, accounting for an increase of 23.6%. On the basis of continuous release of core products such as Showerhead, Neijiang Feng Electronics also completed the acquisition of Capitol Quartz this year. Since then, the company has further expanded its layout to quartz components. In September, the first electrostatic chuck (ESC) trial production of the wholly-owned subsidiary Jingpan Electronics went offline, opening up new space for localized replacement of high-end components.
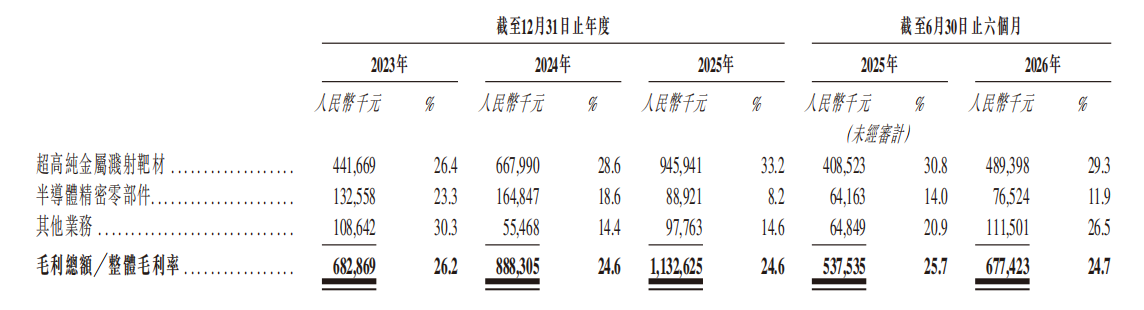
In terms of profitability, from 2023 to the first half of 2026, Jiang Feng Electronics' gross profit was 683 million yuan, 888 million yuan, 1,133 million yuan, and 677 million yuan respectively. The overall gross margin remained within the range of 25% for a long time. In the same period, the company's net profit increased continuously from 217 million yuan in 2023 to 441 million yuan in 2025, reaching 452 million yuan in the first half of 2026, exceeding the full year level of 2025. From a structural perspective, the improvement in gross margin brought about by the upgrading of the target product structure to advanced manufacturing processes is the core support for the profit side to continue to climb. In 2025, the gross margin of Jiang Feng Electronics' ultra-high purity metal sputtering targets reached 33.2%, an overall increase of 6.8 percentage points over 2023.
The Q3 data can be said to further confirm the upward trend in Jiang Feng Electronics' performance. Quarterly revenue of 1,728 billion yuan, up 44.42% year on year; net profit after deducting non-return to mother was 227 million yuan, up 94.23% year on year, up 182.11% month on month; gross margin recovered to 31.93%, up 4.39 percentage points year on year. The scale effect brought about by the increase in the price of target materials and the release of parts in some customer orders is forming a synergy, driving the company's profit center steadily upward.
The boom in the industry continues, and the logic of a double rise in volume and price strengthens expectations?
Currently, AI is reshaping semiconductor chip demand and expanding market opportunities for ultra-high purity metal sputtering targets and semiconductor precision components. On the one hand, the training and reasoning of large AI models requires more powerful computing power. At the same time, logic, storage, and advanced packaging are evolving towards more advanced technology and architecture, supporting product category expansion and technology upgrading.
According to Frost & Sullivan's report, the global ultra-high purity metal sputtering target market will increase from 19.3 billion yuan in 2021 to 27.7 billion yuan in 2025, and is expected to reach 60 billion yuan in 2030 and a compound growth rate of 16.0% in 2026-2030. Among them, targets for semiconductor chips are growing faster, with a compound growth rate of 20.1% in 2026-2030, and a scale of 45.8 billion yuan in 2030. China's semiconductor precision parts market increased from 32.8 billion yuan to 74 billion yuan during the same period, and is expected to reach 166.4 billion yuan in 2030, with a compound growth rate of 16.8%. Both tracks for target materials and components have quantifiable room for expansion on the demand side. Against the backdrop of “both volume and price increases,” the boom in the industry is bound to continue.
Facing this market opportunity, Jiang Feng Electronics' strategic choice is centered around platformization capabilities. The prospectus clearly extends the three capabilities of materials, equipment, and process to more core materials and key components: the target end consolidates advanced process categories and lays out next-generation systems such as tungsten targets and molybdenum targets in advance; the component end concentrates on high-barrier categories such as electrostatic chucks, quartz parts, and ceramic parts; and at the same time promotes the construction of the Huanghu Smart Factory and Korea base to strengthen global delivery resilience.
All in all, Jiang Feng Electronics has now submitted a listing application to the Hong Kong Stock Exchange, which means that it has officially embarked on the journey of building an A+H dual capital platform. Relying on the leading position of target materials and the highly elastic second curve of semiconductor precision components, the company is on the cusp of AI computing power driving the expansion of global semiconductor materials and the continuous acceleration of domestic substitution. The Hong Kong stock platform is expected to not only help it connect with a wider range of international capital, but also make it easier for overseas customers and industry partners to more intuitively understand its blueprint for technological iteration and capacity expansion. If it successfully lands on the Hong Kong Stock Exchange in the future, it is likely that it will add fuel to Jiang Feng Electronics' global expansion; as to whether the company's two-wheel investment story can continue to be realized in the future, this must also be worth maintaining optimistic expectations in the capital market.