


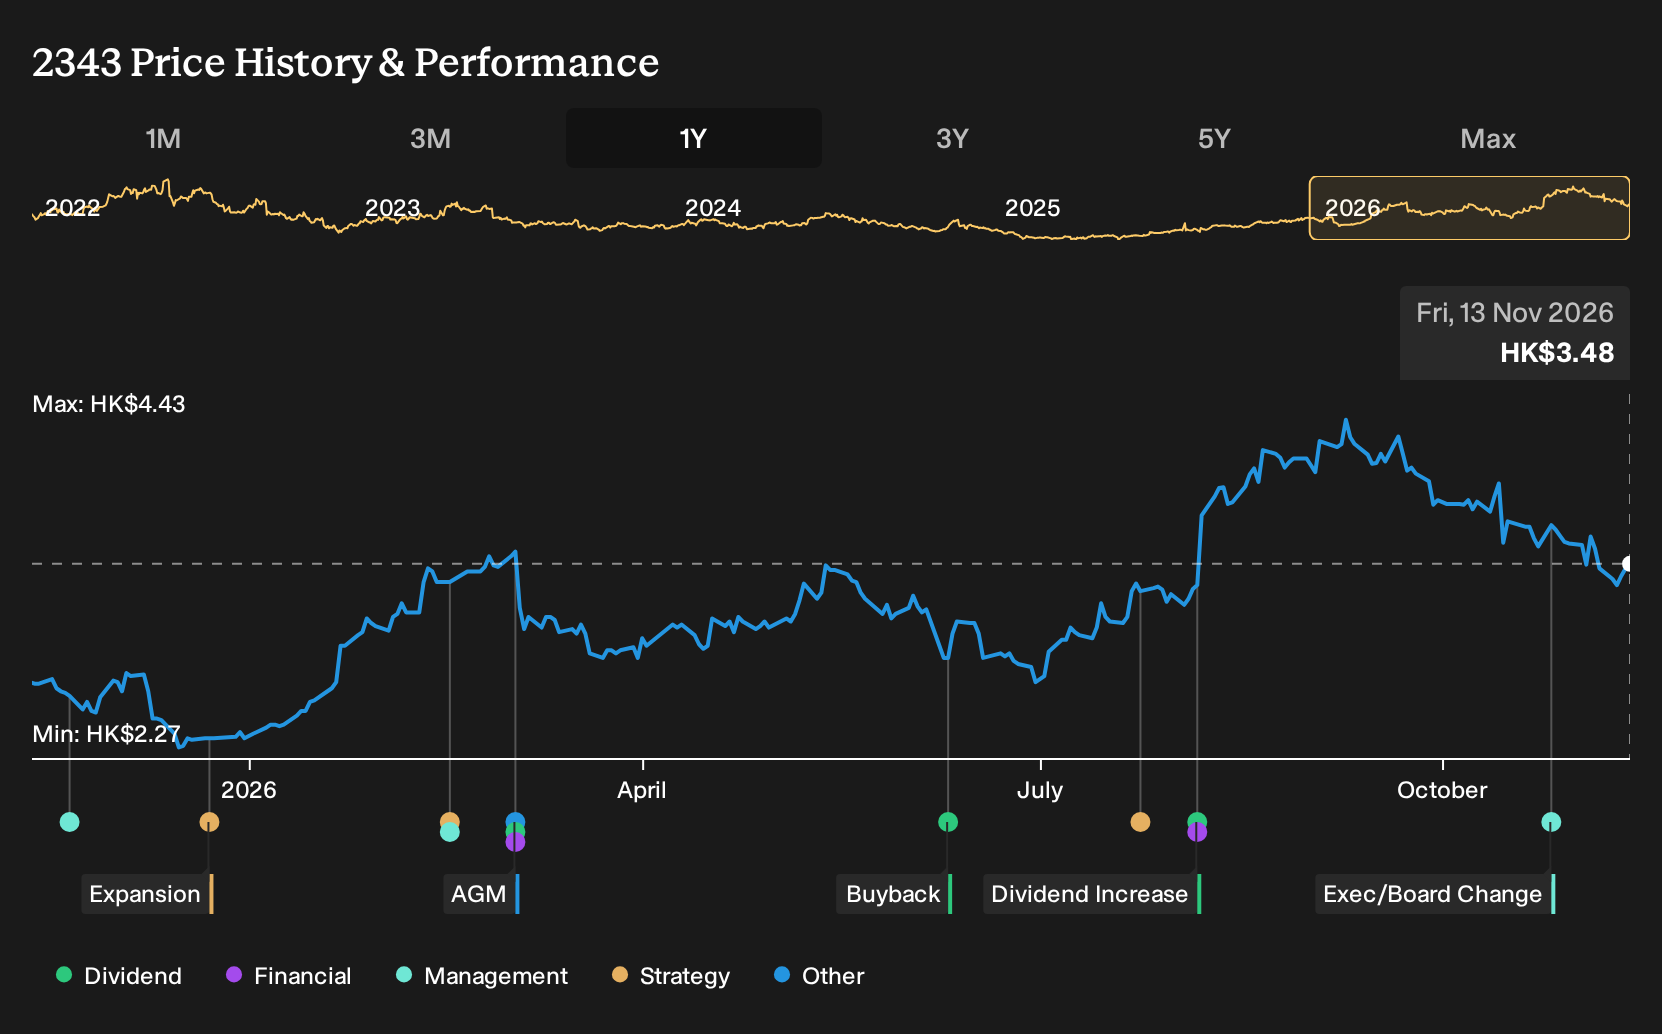
Holding Pacific Basin Shipping over the past year would have returned 37.1%, including dividends. If you had been weighing a purchase back on 13 November 2025, you were looking at a dry bulk operator caught between analyst concern about oversupply and earlier bullish arguments about disciplined management and net cash. With hindsight, the return is easy to see. The real question is what information at that time justified taking, or passing on, that risk.
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The easy part of this move is behind Pacific Basin Shipping. Zero in on 193 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing Up On Pacific Basin Shipping
The shares cost HK$2.69 at the start of the period, and anyone looking at Pacific Basin Shipping then faced two very different but plausible stories.
On the bullish side, User’s August 2025 Narrative put Fair Value at HK$3.01, assuming revenue would fall 11.4% while a 4.3% profit margin and a future P/E of 47.0x might still reward early investment in green methanol vessels.
The November 2025 bear case set Fair Value at HK$2.46, anchored on modest 0.9% revenue growth, a 9.1% profit margin assumption and concern that oversupply and new regulations could weigh on earnings.
What The Results Changed For Pacific Basin Shipping
The sharp move in Pacific Basin Shipping’s H1 2026 profitability, with net income at US$105.05m and net margin at 9.5% versus 2.5% a year earlier, leaned toward the bullish thesis that management discipline could support higher earnings quality. The later article arguing the stock might be fully priced on current earnings pushed back, so the evidence cut both ways.
The hinge assumption here was margin power. When you see a story built on better economics, track reported net margin and earnings revisions side by side at each result before taking the narrative at face value.
What Pacific Basin’s 37% Run Already Prices In
Pacific Basin Shipping now trades at HK$3.48, which is above the Fair Value in the current cautious Narrative. That view treats the recent re-rating as leaving less obvious mispricing while still respecting the business case.
According to cchan3330, an investor in the Simply Wall St Community who wrote the Narrative, the live question is whether board alignment and management discipline keep paying off through a volatile dry bulk cycle.
"The Caravel overhang has been resolved in a way that I think benefits shareholders. The methanol reversal was handled decisively, reinforcing my confidence in management. As ever with this stock, patience is the operative word."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Looking Beyond Pacific Basin Shipping
Pacific Basin Shipping is a story about moving physical cargo. Your next step could be thinking about how people and goods move within cities.
One transport platform now generates sizeable cash while handling rides, deliveries and freight. The twist is that its future economics may hinge on vehicles that drive themselves.
This business is spending heavily to work with autonomous fleets and related technology. Management is effectively paying today so the platform remains relevant if human drivers fade.
If self-driving transport scales, someone will sit between riders, parcels and many different fleets. The open question is how much of that value this marketplace keeps.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 68% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com