


Palo Alto Networks (PANW) is back in focus after reports that it is in talks to buy AI security startup Clutch Security for about US$500 million, highlighting investor attention on its AI driven platforms.
The recent pullback, with a 1 day share price return showing a decline of 3.53% and a 30 day share price return down 18.73% to US$322.66, comes after a strong year to date share price return of 79.89% and a 1 year total shareholder return of 57.57%. This indicates that momentum has cooled in the short term, even as longer term holders, with a 5 year total shareholder return of 272.31%, still sit on sizeable gains.
Scan for other cybersecurity players riding the same AI security wave as Palo Alto Networks with our hand picked list of 53 AI infrastructure stocks.
Palo Alto Networks now trades at a clear discount to both intrinsic estimates and analyst targets after that sharp pullback. Is this healthy caution on AI execution risks, or has the market pushed the valuation too far down?
Most Popular Narrative: 18.5% Undervalued
On the analyst consensus Narrative on Simply Wall St, Palo Alto Networks carries a fair value estimate of $396.12, which sits above the last close of $322.66 and frames the current pullback against long term AI driven expectations.
The main requirement is that Palo Alto Networks continues to turn platformization, recent acquisitions such as Idira and Chronosphere, and AI-driven offerings like Prisma AIRS and Unit 42 Frontier AI Defense into durable multi-billion dollar ARR pillars, while avoiding margin pressure from higher cloud and hardware costs or stock-based compensation.
The view that Palo Alto Networks is fairly valued and bullish indicates that the current share price already reflects strong guidance for revenue, NGS ARR, RPO and free cash flow margins through FY27, as well as an eventual move toward a 40% adjusted free cash flow margin by FY28, which leaves limited room for execution shortfalls.
See why 396 investors see Palo Alto Networks as 19% undervalued.
Result: Fair Value of $396.12 (UNDERVALUED)
Still, gross margin pressure from higher cloud and hardware costs, along with elevated stock based compensation dilution, could quickly weaken the bullish Palo Alto Networks narrative.
Find out about the key risks to this Palo Alto Networks narrative.
Another View: Palo Alto Networks Looks Expensive On Sales
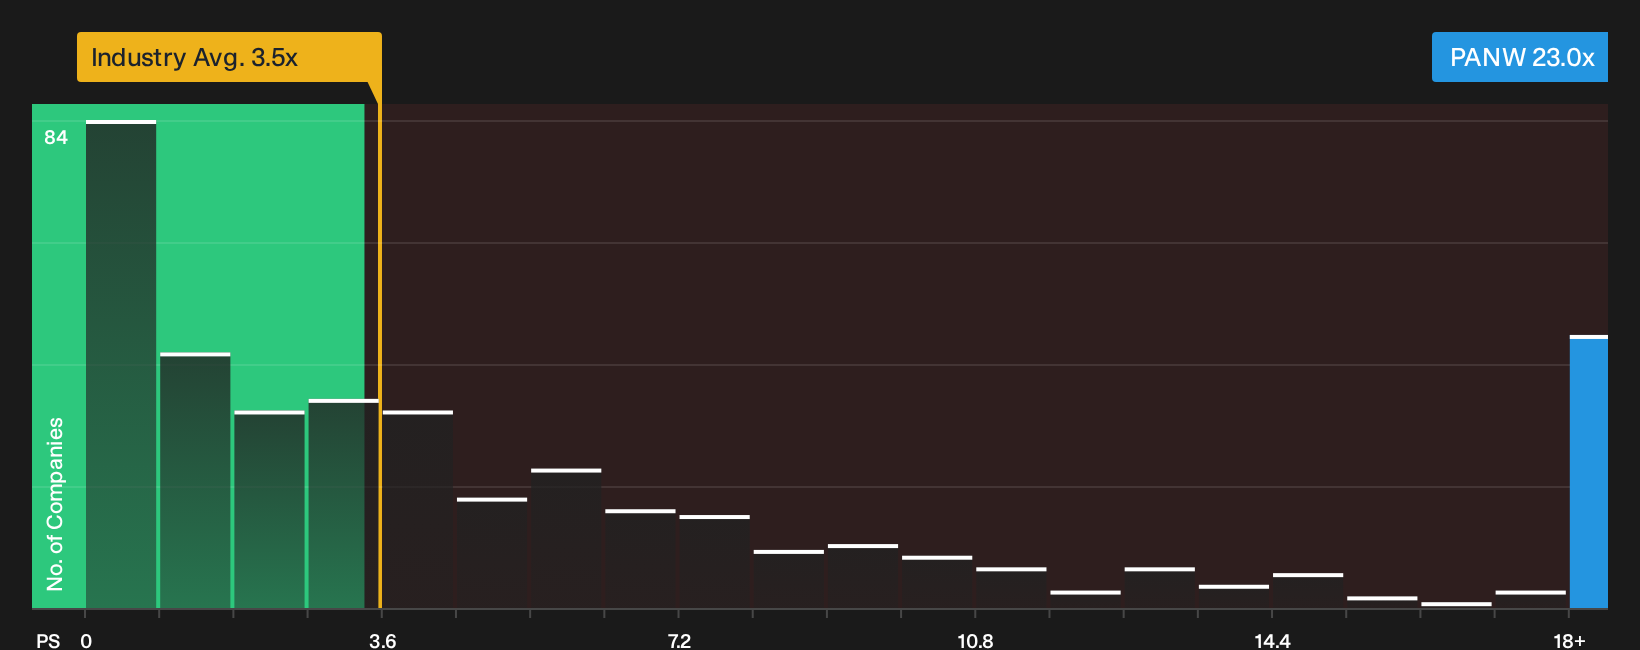
The fair value narrative for Palo Alto Networks leans on future cash flows and analyst targets. A different picture appears when using today’s P/S ratio. The stock trades at 23x sales versus 17x for peers and 3.5x for the wider US Software group, while the fair ratio is 14.9x. That gap points to valuation risk if sentiment cools, even with an 18.5% discount to fair value on cash flows in play.
For a closer look at how that gap could close over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone on Palo Alto Networks so far feels unresolved, treat that as a signal to move quickly to review the figures independently. After that, evaluate the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Palo Alto Networks?
If Palo Alto Networks has sharpened your interest in focused opportunities, broaden your watchlist now or you risk missing other compelling setups across quality, value and income.
- Target resilient balance sheets by scanning a curated list of solid balance sheet and fundamentals (23 results) that filters for companies with financial strength front and center.
- Hunt for potential mispriced opportunities using the 32 high quality undervalued stocks and sort through businesses where fundamentals and valuation work harder together.
- Build a cash flow stream by reviewing a focused 6 dividend fortresses that highlights higher yielding payouts with an eye on staying power.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com