


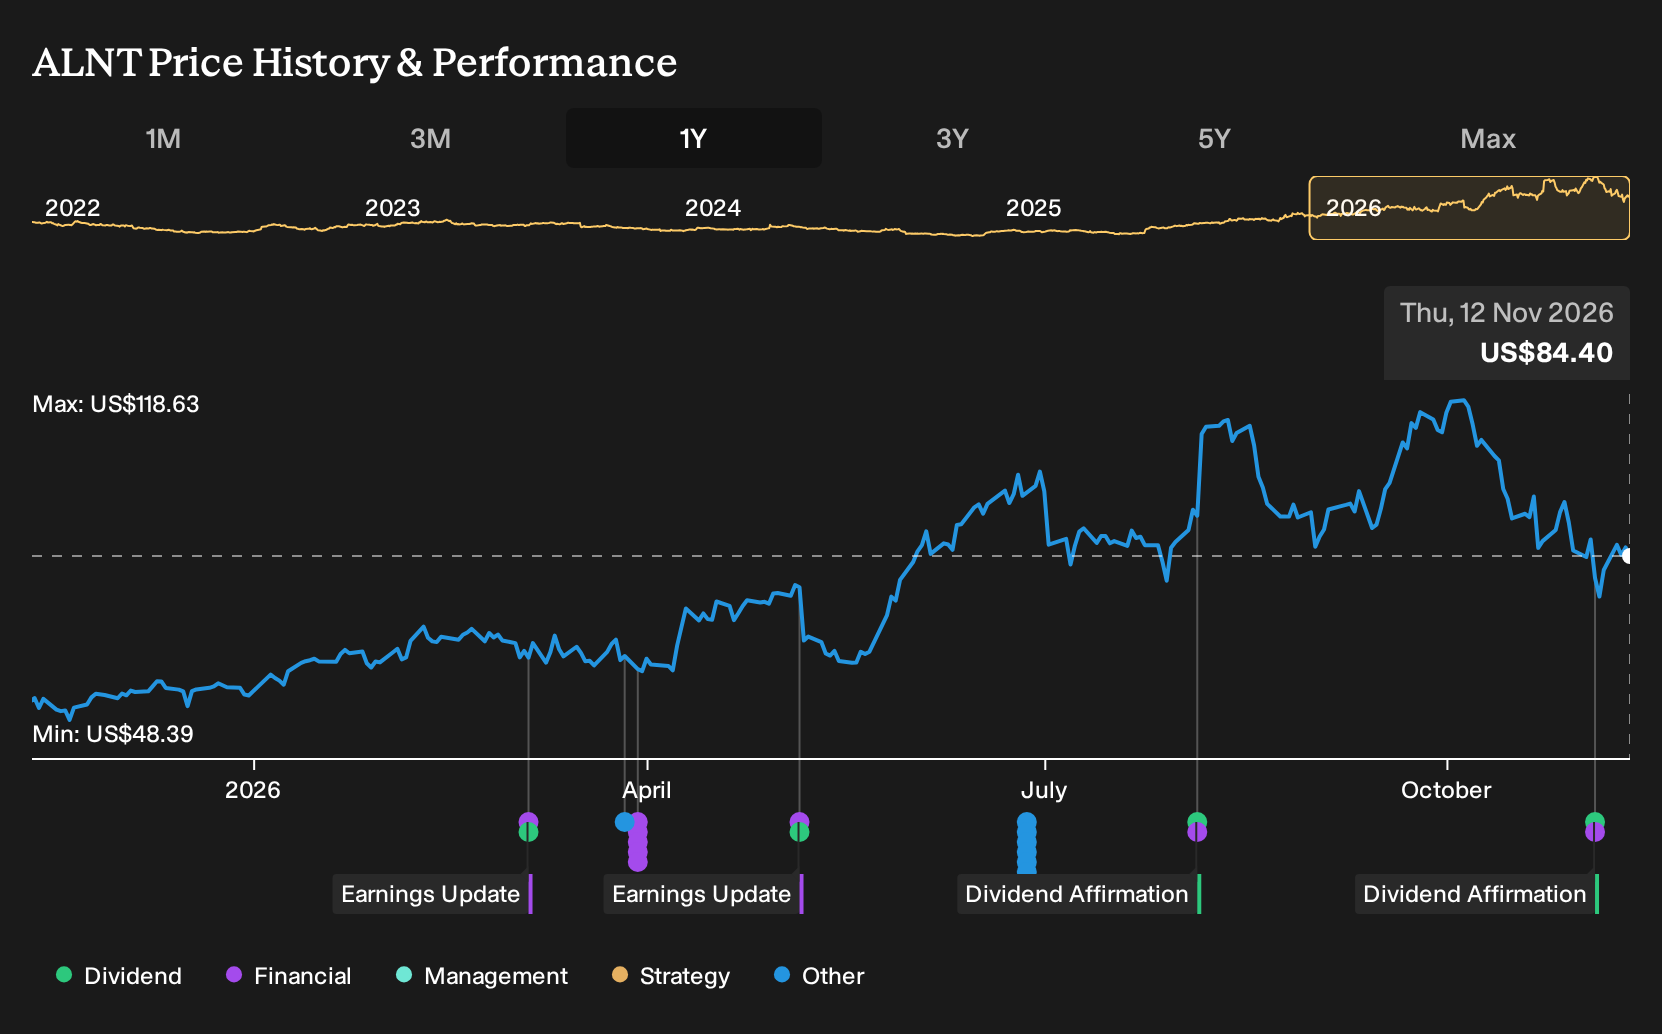
- Allient reported third quarter 2026 sales of US$164.4 million and net income of US$15.33 million, alongside a US$0.04 per share quarterly dividend payable on December 2, 2026, to holders of roughly 17.0 million shares as of November 18, 2026.
- The combination of higher earnings per share from continuing operations and a maintained cash dividend indicates that Allient is pairing profit improvement with ongoing cash distributions to shareholders. This highlights management’s focus on both operational performance and capital return discipline.
- This context helps frame how Allient's stronger earnings per share and maintained dividend may influence the broader investment narrative for investors.
Scan beyond Allient's latest earnings and dividend update by comparing it with 6 dividend fortresses, a tool built for investors who care about steady cash payouts backed by underlying financial strength.
Allient Investment Narrative Recap
Owning Allient means believing its shift toward higher value industrial, medical, aerospace and defense work can continue to translate into resilient orders and margins. The analyst consensus narrative on Simply Wall St links that view to strong bookings, a solid backlog and ongoing benefits from STAN cost savings. The latest quarter shows higher sales and net income, which supports that thesis rather than changing it.
The more immediate swing factor is execution on restructuring and productivity initiatives such as the Dothan transition, since elevated realignment costs could pressure net margins. Valuation is another active risk, with commentary pointing to a rich P/E and cash flow models that sit below the current share price.
The standout update is Allient’s third quarter 2026 earnings, with US$164.4 million in sales and US$15.33 million in net income. Basic and diluted earnings per share from continuing operations were US$0.91, compared with US$0.39 a year earlier. For the first nine months, sales were US$457.08 million and net income was US$31.07 million.
Those results matter because the current catalysts rely on record bookings and backlog converting into earnings, while STAN cost savings and mix changes support margins. Stronger year on year EPS from continuing operations gives investors more evidence on execution, though it does not remove risks around future restructuring costs or a valuation that some models already flag as demanding.
Allient's narrative projects US$727.9 million revenue and US$56.3 million earnings by 2029. This assumes 8.2% yearly revenue growth and an earnings increase of about US$27.7 million from US$28.6 million today.
Uncover how Allient's fair value indicates a 40% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
One bullish twist on Allient focuses on upside from stronger long term earnings power. The most optimistic analysts were pencilling in US$768.4 million of revenue and US$62.1 million of earnings by 2029 before this dividend affirmation and earnings release. You can use those higher forecasts as a reference point to test how your own view might change after the latest results.
Explore 2 other Allient fair value estimates, including one that suggests as much as 54% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Allient research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Allient. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Allient's overall financial health at a glance.
Looking for more ideas beyond Allient?
If Allient's latest update has sharpened your focus on earnings quality and dividends, it can be useful to line that up against other opportunities using clear, rules-based stock lists.
- If you prize resilience and capital preservation, run your eye over a group of companies screened as 29 resilient stocks with low risk scores that may help smooth out portfolio volatility.
- For investors who want a stronger balance sheet behind every position, filter the market using a list of solid balance sheet and fundamentals (23 results) and compare how those businesses stack up next to Allient.
- If you enjoy finding stories earlier in their journey, broaden your watchlist with a 20 high quality undiscovered gems that already show solid fundamentals but attract less attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com