


Core Scientific has surged over the past week as investors react to its rapid pivot from Bitcoin mining to AI focused colocation, which puts fresh scrutiny on whether the current share price lines up with what its sales can reasonably support. With the business now leaning heavily on contracted data center capacity and long term agreements, the question becomes how much of that revenue profile is already reflected in today's valuation.
- The stock has gained 26.4% over the past seven days, which puts recent enthusiasm squarely up against the harder question of what buyers are paying for each dollar of sales.
- The shift toward AI and high performance computing colocation, backed by a contracted portfolio tied to large tenants and sizable projected revenue, may support higher and more visible future sales but also requires meaningful capital investment and execution to fully translate into cash generation.
- There is a second opinion on Core Scientific worth weighing. See what analysts think Core Scientific's shares could be worth.
For investors, the debate is whether Core Scientific's current share price is justified by its sales given the recent run in the stock and the scale of its AI colocation transition.
If you are weighing Core Scientific against other AI infrastructure plays, it can help to compare it with a broader set of 53 AI infrastructure stocks.
Is Core Scientific Getting Expensive on Sales?
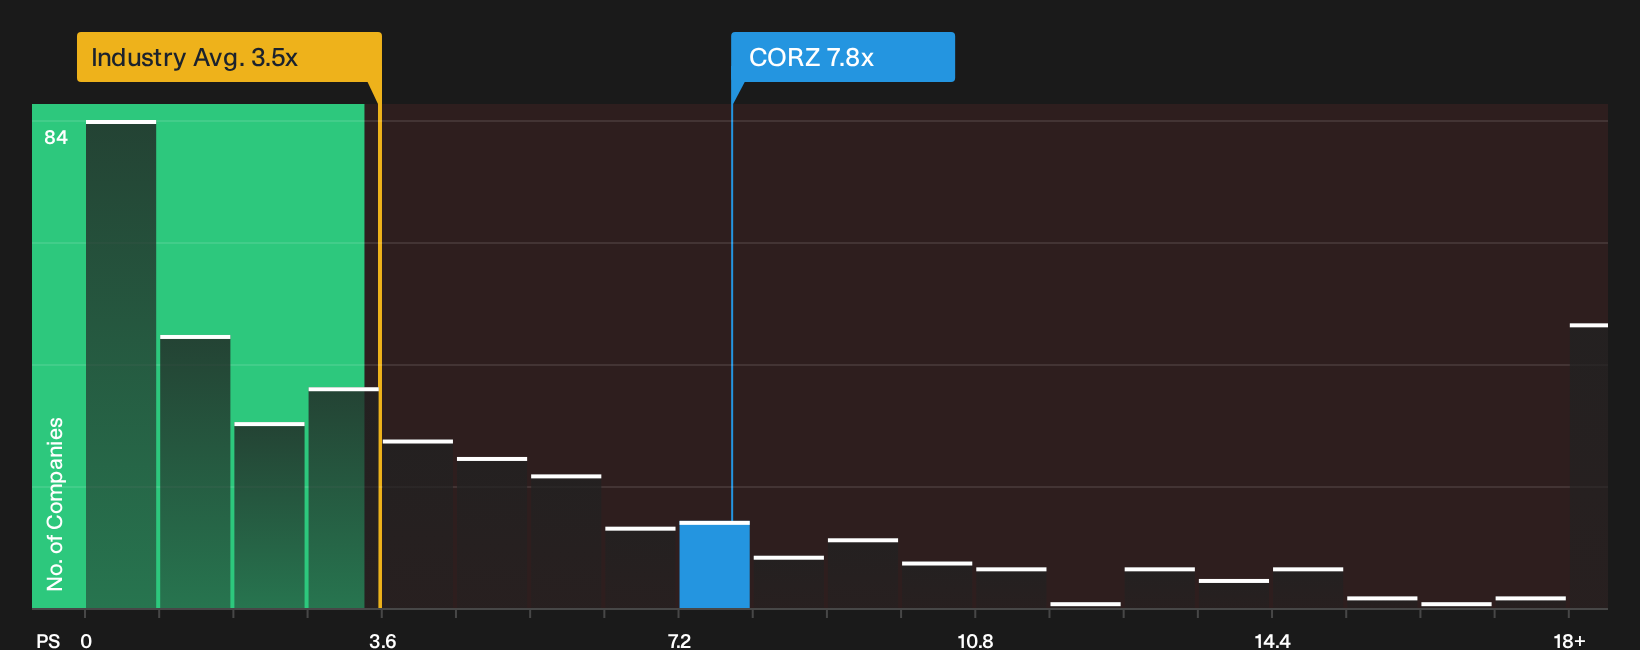
P/S fits Core Scientific because the business is being valued heavily on revenue tied to long term AI colocation contracts rather than current profits. On this yardstick, the stock trades at about 7.8x sales, which is more than double the software industry average of roughly 3.5x and also above the peer group at about 3.2x.
That gap is larger than the tailored fair multiple implied by its fundamentals, so on this framework the market is pricing Core Scientific as overvalued. Because the AI colocation pivot is already backed by sizeable contracted capacity and projected revenue, the current P/S suggests investors are paying up for that pipeline well ahead of full cash conversion. Despite management flagging a revenue run rate of about US$1.8b and sizeable projected net operating income once the portfolio is fully operational, the valuation still assumes a lot of that journey goes to plan. Explore the numbers behind Core Scientific's P/S valuation.
The Core Scientific Narrative: What Would Justify Today's Price?
Core Scientific's valuation puzzle leads straight into Simply Wall St Narratives. These spell out what would need to happen to the firm's growth, margins and earnings for the stock to look much cheaper or more expensive than it does today on the Community page. Each Narrative ties a fair value to a specific version of Core Scientific's possible catalysts and risks so you can track over time which story the actual results appear to match.
Views on Core Scientific now split between long term contract optimism and concern over how much Texas risk is already baked into the share price.
Bull case: 53% undervalued
According to the analyst consensus Narrative on Simply Wall St, Core Scientific’s long dated contracts are the main reason the upside case exists.
"The current valuation suggests that the market is heavily discounting the long dated, contracted revenue and NOI from roughly 1.1 GW of AI colocation capacity..."
Discover why this Narrative puts Core Scientific at 53% undervalued.
Bear case: 13% overvalued
DanielOliveira, a Simply Wall St Community investor who wrote the Narrative, focuses on how much rides on Texas approvals and timing.
"My call: the next re-rating depends less on the next revenue beat and more on what ERCOT finalizes for Pecos and Hunt..."
Explore why this Narrative puts Core Scientific at 13% overvalued.
One more Core Scientific angle that deserves a closer look
Before forming a view on Core Scientific, it is worth checking the underlying risk checks, where the research has already flagged specific concerns that sit alongside the valuation story. Take a closer look at 3 warning signs (2 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com