


- In November 2026, Entegris expanded its partnership with Kioxia to co develop materials for future BiCS FLASH 3D memory using AI, digital twins and joint work at the Geino Technology Center in Japan.
- This deeper tie in with a leading memory producer gives Entegris earlier line of sight into future device needs and could shape where it focuses materials R&D spending and new capacity.
- We will look at how Entegris’ investment narrative could shift as this AI driven Kioxia collaboration reframes its materials roadmap.
Scan beyond Entegris and this Kioxia tie up by reviewing a curated set of 53 AI infrastructure stocks that could also be positioned for AI heavy chip manufacturing demand shifts.
Entegris Investment Narrative Recap
To own Entegris, you need to believe the analyst consensus Narrative on Simply Wall St that higher AI related wafer complexity and new fabs can support rising materials content, better margins and solid free cash flow. The near term swing factor is execution on capacity optimization and cost discipline while demand across logic and memory stays healthy enough to keep factories efficiently utilized.
The biggest risk is that rich valuation multiples and prior insider selling leave the stock sensitive to any stumble, especially if revenue or free cash flow soften or sector sentiment cools. The fresh Kioxia collaboration refines the technology roadmap but does not materially change that near term risk reward skew today.
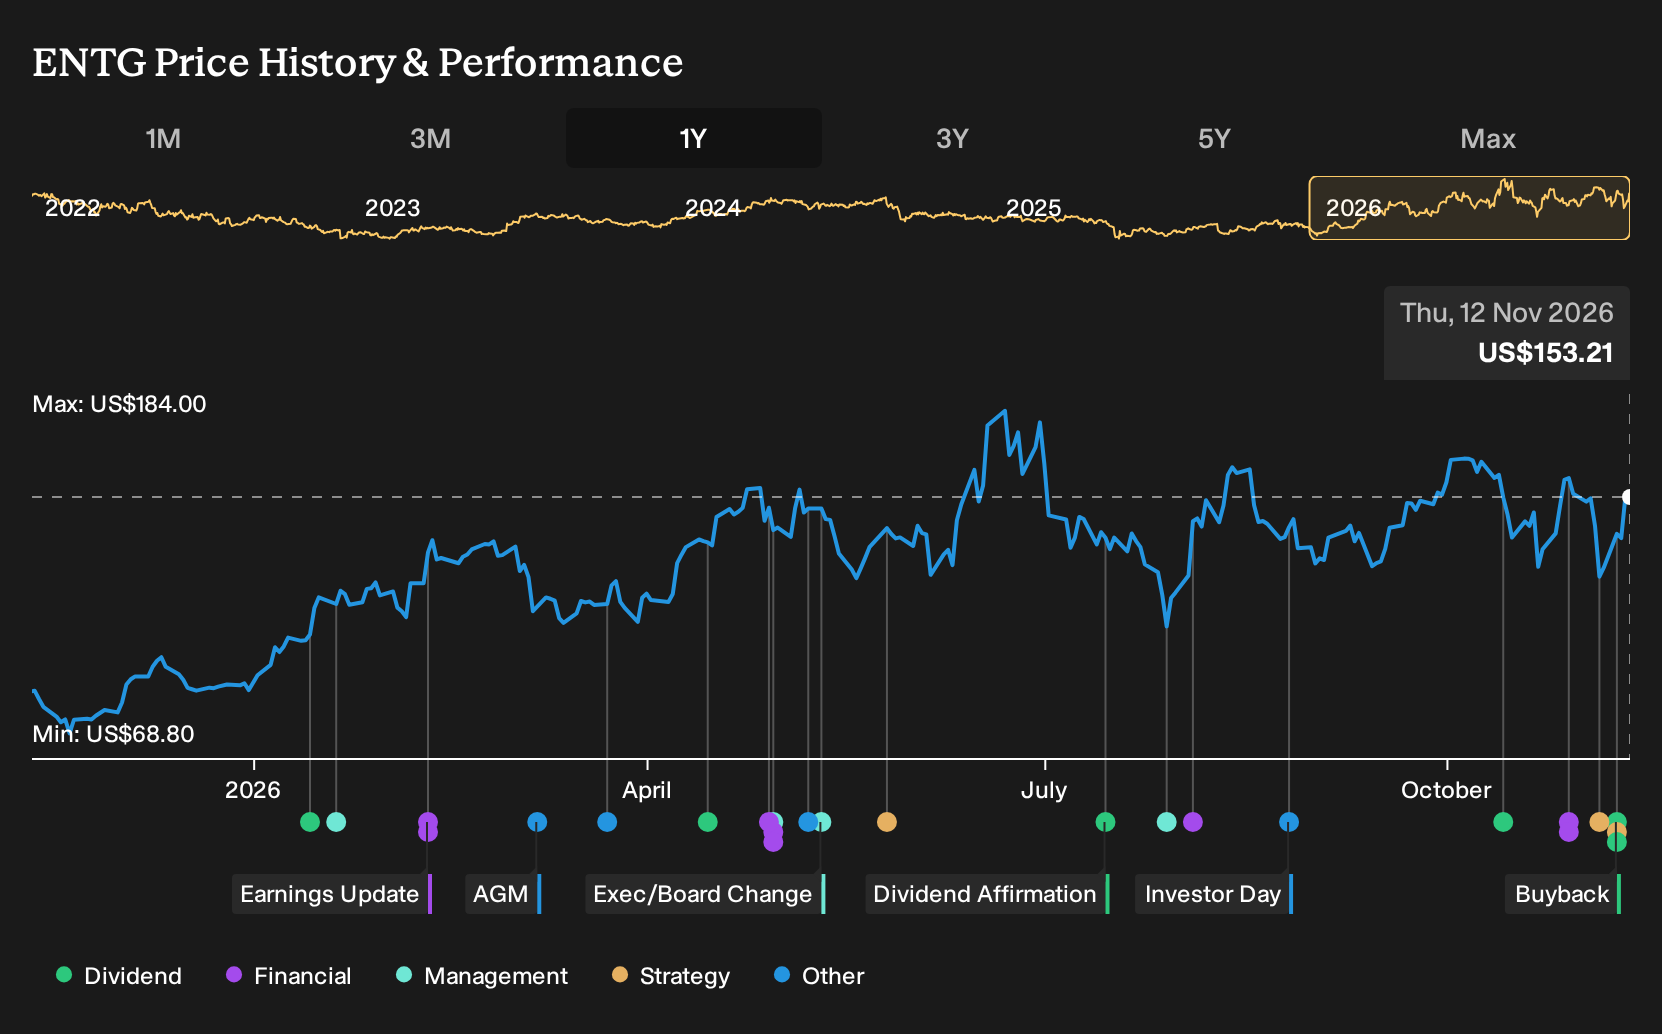
The new US$500m share repurchase authorization is the announcement that most directly intersects with this AI driven Kioxia work. Management signaled a more balanced capital framework, with buybacks now sharing the stage with capex and M&A. That makes future cash generation and balance sheet progress even more important for your thesis.
For catalysts, the program can tighten the share count over time, which matters if earnings track the growth profile analysts expect. On the flip side, Entegris still carries meaningful debt and the stock trades at what some describe as a demanding P/E, so sustained buybacks rely on consistent execution, robust semiconductor materials demand and disciplined use of leverage.
Entegris' narrative points to US$4.9b in revenue and US$807.5m in earnings by 2029, based on analysts' assumptions. That path reflects 11.4% yearly top line growth and an earnings increase of about US$414.7m from US$392.8m today to the 2029 consensus figure.
Uncover why Entegris' fair value indicates a 23% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle you might consider focuses on M&A risk. The most optimistic Entegris analysts were already penciling in about US$5.8b of revenue and US$1.5b of earnings by 2029 before this Kioxia partnership and new deal appetite. That is a far more ambitious story, and this fresh news could push those narratives to shift again.
Explore 4 other Entegris fair value estimates, including one that suggests as much as 46% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Entegris research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Entegris. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Entegris' overall financial health at a glance.
Looking for more Entegris style investment ideas?
If this Entegris and Kioxia story has sharpened your interest in AI heavy manufacturing, it can help to widen the watchlist using the Simply Wall St Screener so you can compare other businesses on the same set of fundamentals.
- For investors who want potential mispriced quality with room for sentiment to shift, scan a curated group of 32 high quality undervalued stocks that combine fundamentals with a discount to fair value models.
- If resilience matters more than rapid swings, filter for companies with lower risk profiles using a focused set of 29 resilient stocks with low risk scores that screen for balance sheet strength and earnings stability.
- When the goal is to spot underfollowed opportunities before they become crowded, broaden your research with a tailored list of 20 high quality undiscovered gems that highlight strong fundamentals with less market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com