


Pursuit Attractions and Hospitality has delivered a strong share price run in recent years, so the live question now is whether that move is adequately backed by its earnings power. With fresh news around record revenue and a business refocus into attractions and hospitality, investors are increasingly asking if the current valuation fairly reflects what the company is actually earning today.
- The stock is up 70.5% over the past 3 years, which puts real pressure on the earnings profile to justify how far the share price has already come.
- Record revenue, higher effective ticket prices and a shift into a pure-play attractions and hospitality model can shape expectations for future profitability and the durability of earnings growth.
- The analysts covering Pursuit Attractions and Hospitality have run their own numbers. See what analysts think Pursuit Attractions and Hospitality's shares could be worth.
The issue now is whether Pursuit Attractions and Hospitality's current share price is appropriately aligned with the earnings investors are paying for today.
If you are weighing Pursuit Attractions and Hospitality's recent earnings against its share price, it can help to compare that setup with 32 high quality undervalued stocks.
Has Pursuit Attractions and Hospitality Run Too Far on Earnings?
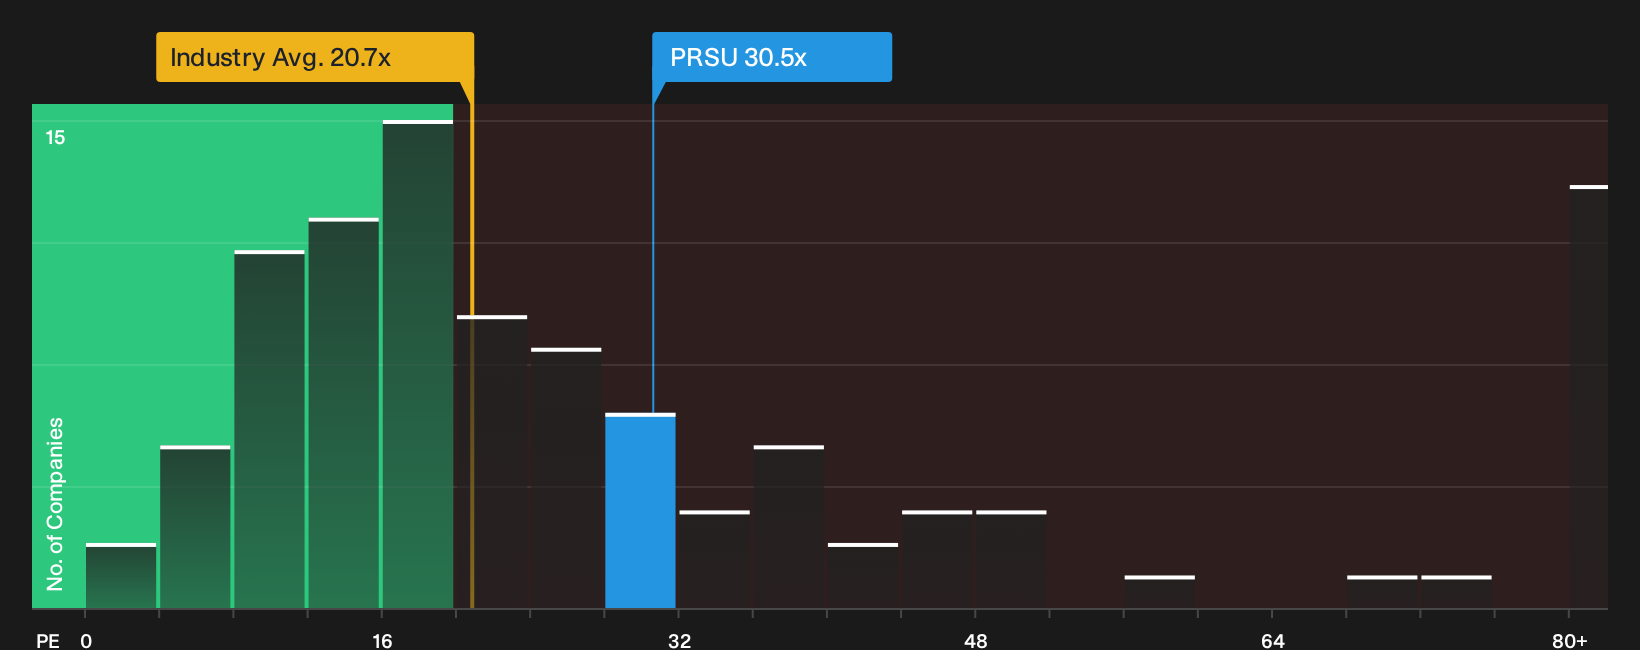
P/E fits Pursuit Attractions and Hospitality because earnings are now a key focus metric after the switch to a pure-play attractions and hospitality model. The stock trades on a P/E of 30.5x, which is higher than the Hospitality industry average of 20.7x and above the peer group on 23.7x. Because the in-house model that blends growth, profitability, size and risk points to a lower multiple as a better fit, this gap suggests investors are already paying up for the current earnings profile rather than getting it at a discount.
Record Q3 2026 revenue and firmer effective ticket pricing help explain why the market is willing to attach a richer earnings tag to Pursuit Attractions and Hospitality, even with visitation softness and weather disruption in the mix. To judge whether that premium is acceptable, you would need to weigh how durable those earnings are now that the FlyOver business has been sold at a 14.5x multiple and the balance sheet holds US$64.3m of unrestricted cash with no buybacks in play. Explore the numbers behind Pursuit Attractions and Hospitality's P/E valuation.
The Pursuit Attractions and Hospitality Narrative: What Would Justify Today's Price?
Simply Wall St Narratives picks up where the current valuation debate for Pursuit Attractions and Hospitality's stock leaves off by spelling out which growth, margin and earnings paths would need to hold for the shares to be worth meaningfully more or less than they trade for today on the market. Rather than leaning on a single multiple or one model output, each narrative lays out the assumptions driving its fair value view so you can track those against Pursuit Attractions and Hospitality's actual results over time.
One of the top narratives on Pursuit Attractions and Hospitality: 13% undervalued
This is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Disciplined acquisitions of high margin, scarce assets such as Tabacón and Eagle Wing Tours, typically at 6x to 9x EBITDA with targeted returns above 15%..."
Discover why this Narrative puts Pursuit Attractions and Hospitality at 13% undervalued.
An unresolved piece of the Pursuit Attractions and Hospitality puzzle
Price and profits tell only part of the story for Pursuit Attractions and Hospitality, because the people setting priorities and how they are rewarded can heavily shape what happens next for shareholders. See who runs Pursuit Attractions and Hospitality and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com