


Dividend decision and upgraded outlook put Urban Edge Properties in focus
Urban Edge Properties (UE) caught investor attention after management raised full-year guidance for adjusted funds from operations and affirmed capital recycling into higher growth retail centers.
The move comes alongside a regular quarterly dividend of $0.21 per share, declared on November 6, 2026, payable December 31 to shareholders of record on December 15.
Urban Edge Properties shares trade at $21.04, with a 30-day share price return of 8.68% and year-to-date share price gain of 10.16%, while total shareholder return of 14.60% over one year and 41.53% over three years points to momentum that has been building rather than fading.
Spot opportunity by comparing Urban Edge Properties with a curated 32 high quality undervalued stocks that share a focus on income, real assets, and disciplined capital allocation.After that guidance lift and a share price sitting at $21.04, Urban Edge Properties now asks a simple question of investors: Does the current valuation still leave more upside than downside from here?
Most Popular Narrative: 11% Undervalued
On the Simply Wall St analyst consensus Narrative, Urban Edge Properties screens as undervalued, with a fair value of $23.71 against the latest $21.04 close and a discount rate of 8.21% shaping that view.
Active capital recycling, selling lower-growth assets at low cap rates and acquiring higher-yielding shopping centers, positions the company for outsized NOI and earnings growth as proceeds are reinvested into more productive properties. Redevelopment projects and the S&O (signed-not-open) pipeline represent visible, near-term NOI gains (8% of current NOI), while also increasing property values and supporting longer-term revenue and earnings growth.
See why 1 investors see Urban Edge Properties as 11% undervalued.
Result: Fair Value of $23.71 (UNDERVALUED)
Still, the bullish Urban Edge Properties story could be knocked off course if tenant distress in big box retail accelerates or if its Northeast heavy footprint encounters a local slowdown.
Find out about the key risks to this Urban Edge Properties narrative.
Another View: Urban Edge Properties Through Earnings Multiples
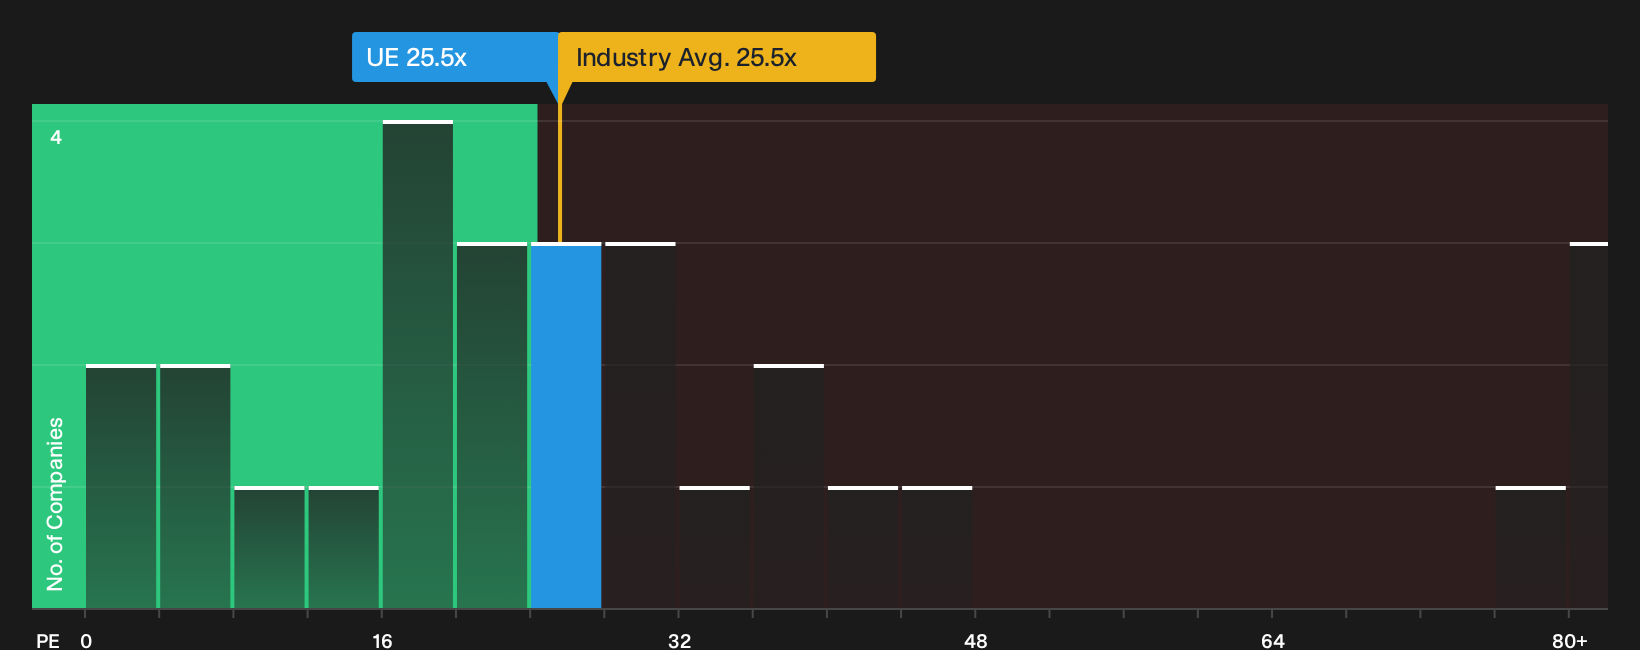
That discounted cash flow story presents Urban Edge Properties as undervalued. A quick look at the P/E picture appears less generous. UE trades on a P/E of 25.5x, which is slightly higher than both its 22.5x fair ratio and the 25.2x US Retail REITs average, so investors are already paying a small premium while forecasts call for earnings to decline over the next few years. Is that a margin of safety or a margin for disappointment?
To see how that earnings multiple could re-rate if sentiment or assumptions shift, take a closer look at the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Urban Edge Properties so far. If that blend of risks and rewards feels finely balanced, consider moving quickly and stress test the thesis for yourself with 1 key reward and 4 important warning signs.
Looking for more investment ideas beyond Urban Edge Properties?
If Urban Edge Properties has sharpened your focus on valuation, income, and resilience, broaden your watchlist now so you are not late to the next opportunity.
- Target reliable income streams by reviewing a curated 6 dividend fortresses that filters for companies aiming to pair strong yields with staying power.
- Hunt for quality at a discount through the 20 high quality undiscovered gems that highlights under-followed businesses with fundamentals that may not be fully appreciated yet.
- Prioritise resilience first and return second by screening a 29 resilient stocks with low risk scores that focuses on sturdier balance sheets and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com