


Nvidia’s shock leadership scandal, a US$550b value hit and fresh political scrutiny on AI chips have handed investors a rare moment of reset. When a giant stumbles, attention swings to other players exposed to the same headlines, and pricing can move faster than the story. This article walks through three stocks from our Non Nvidia AI hardware screener that appear positively exposed to this turmoil and explains what that might mean for your portfolio approach.
The three stocks below are just a sample of what this shock has thrown into focus, with the full screen surfacing 66 more large, liquid AI hardware companies with equally compelling stories that are not covered here. To go straight to the wider opportunity set, use the Non-Nvidia AI Chip and Data-Center Hardware Leaders screener to identify, analyze and focus on the highest conviction ideas for your own watchlist.
Samsung Electronics (KOSE:A005930)
Samsung Electronics slots into this AI hardware screen as a huge supplier of chips and equipment used in data centers, with memory heavy exposure that keeps it tightly linked to how AI compute is financed and priced. According to FundamentalFlow, an investor in the Simply Wall St Community, the real debate now is not whether the business participates in AI demand, but how long current conditions in its key memory markets can realistically last.
"CXMT is a 2027 to 2028 pricing-power risk, not a Q4 2026 earnings risk. It is the main reason I would not give memory a “supercycle” multiple in the base case."
What happens to Samsung Electronics’ future margins depends heavily on how that still unresolved competitive pressure in memory unfolds.
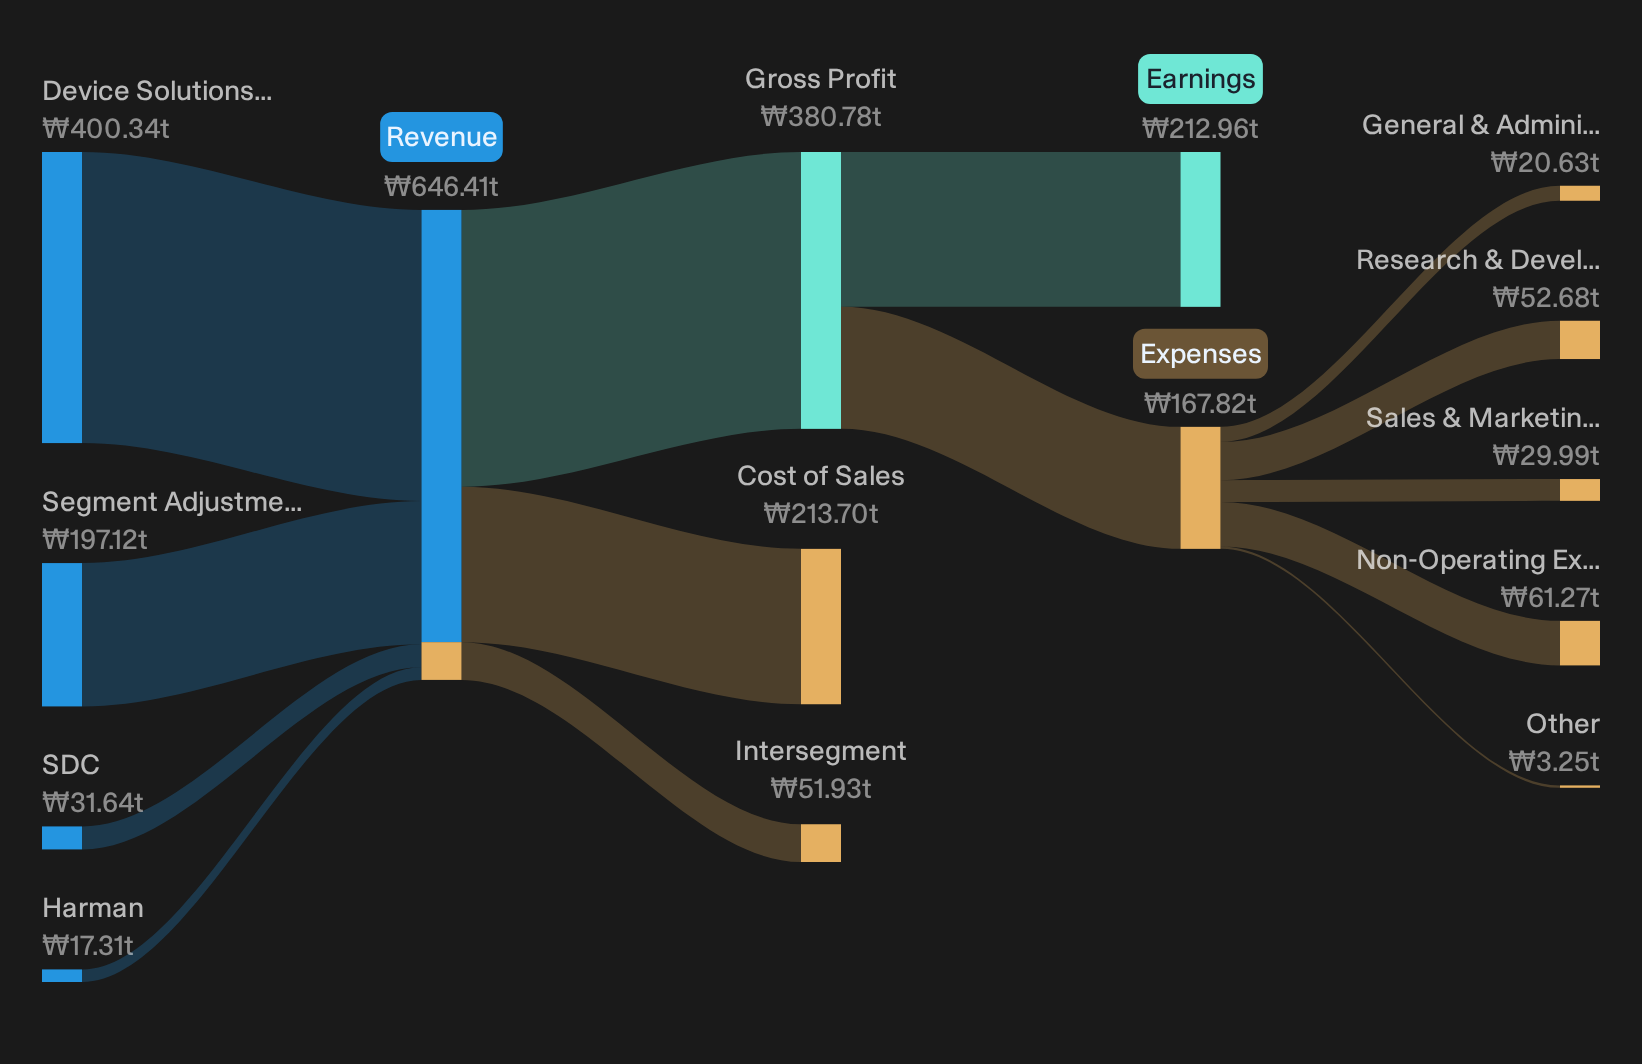
Samsung Electronics runs a broad hardware and services empire across phones, TVs, appliances and chips, yet the Device Solutions segment, at about ₩400,344b revenue, remains the main engine, alongside smaller units like SDC and Harman, underpinned by a roughly ₩1,334,216b market cap that fits this large cap AI compute hardware theme.
That margin question is exactly what sits at the center of the full narrative for Samsung Electronics, where AI demand, memory pricing power and long term returns intersect.
MiTAC Holdings (TWSE:3706)
MiTAC Holdings is a Taiwan based hardware group in the Non Nvidia AI Chip and Data Center Hardware Leaders screen, building AI and cloud servers, storage and industrial devices. Cloud computing products generate about NT$115.9b, Automotive Electronics and AIoT around NT$9.2b, with a market value near NT$95.3b.
MiTAC Holdings provides direct exposure to AI ready servers and storage that enterprises can use as they spread data center spending beyond Nvidia. This is backed by forecast revenue and earnings growth and a P/E below the Taiwan market. However, the key issue is how one less visible pressure may shape future cash generation.
That cash flow overhang is exactly what you are weighing with MiTAC Holdings, so use the 3 key rewards and 2 important warning signs (1 is major!) for a clearer read on how growth and risk are really lining up.

Camtek (CAMT)
Camtek sits in this Non Nvidia AI hardware group as a pick-and-shovel supplier, with the bullish analyst Narrative on Simply Wall St arguing that its inspection and metrology tools could be a direct beneficiary of shifting AI chip capex away from a single vendor.
"Accelerating deployment of Camtek’s Hawk and Eagle G5 platforms into new inspection and metrology steps at key HBM and chiplet customers, including additional 2D and 3D control points around HBM4 and CoWoS flows, can push tool counts per line higher and lift systems revenue and gross margin mix as these higher value configurations take a larger share of shipments."
What happens if one key assumption about how quickly those AI focused inspection steps expand across customer lines proves too optimistic will matter a lot for future margins.
Camtek generates about US$544 million from electronic test and measurement instruments and, with a roughly US$5 billion market cap, gives investors a pure play on inspection and metrology equipment that sits squarely in the AI chip production toolchain.
If that adoption curve plays out differently, the full narrative for Camtek shows how Camtek’s inspection footprint, pricing power and AI exposure could still accelerate or stall in surprising ways.

Seeking Fresh Alternatives Beyond Nvidia?
New themes can gain breakout momentum quickly, while the best entry points quietly drop away under the radar for now. Scan these fresh idea lists before the crowd and consider them early.
- Target robust cash generators and reduce weak balance sheet risk by screening a curated list of solid balance sheet and fundamentals (199 results) while that quality edge still flies under most investors’ radar.
- Track structural demand for secure power as AI and electrification reshape grids by following the curated 43 power grid technology and infrastructure stocks before infrastructure leaders are more widely owned by index funds.
- Review hand picked 85 robotics and automation stocks that could benefit as manufacturers upgrade factories and logistics while it still matters.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com