


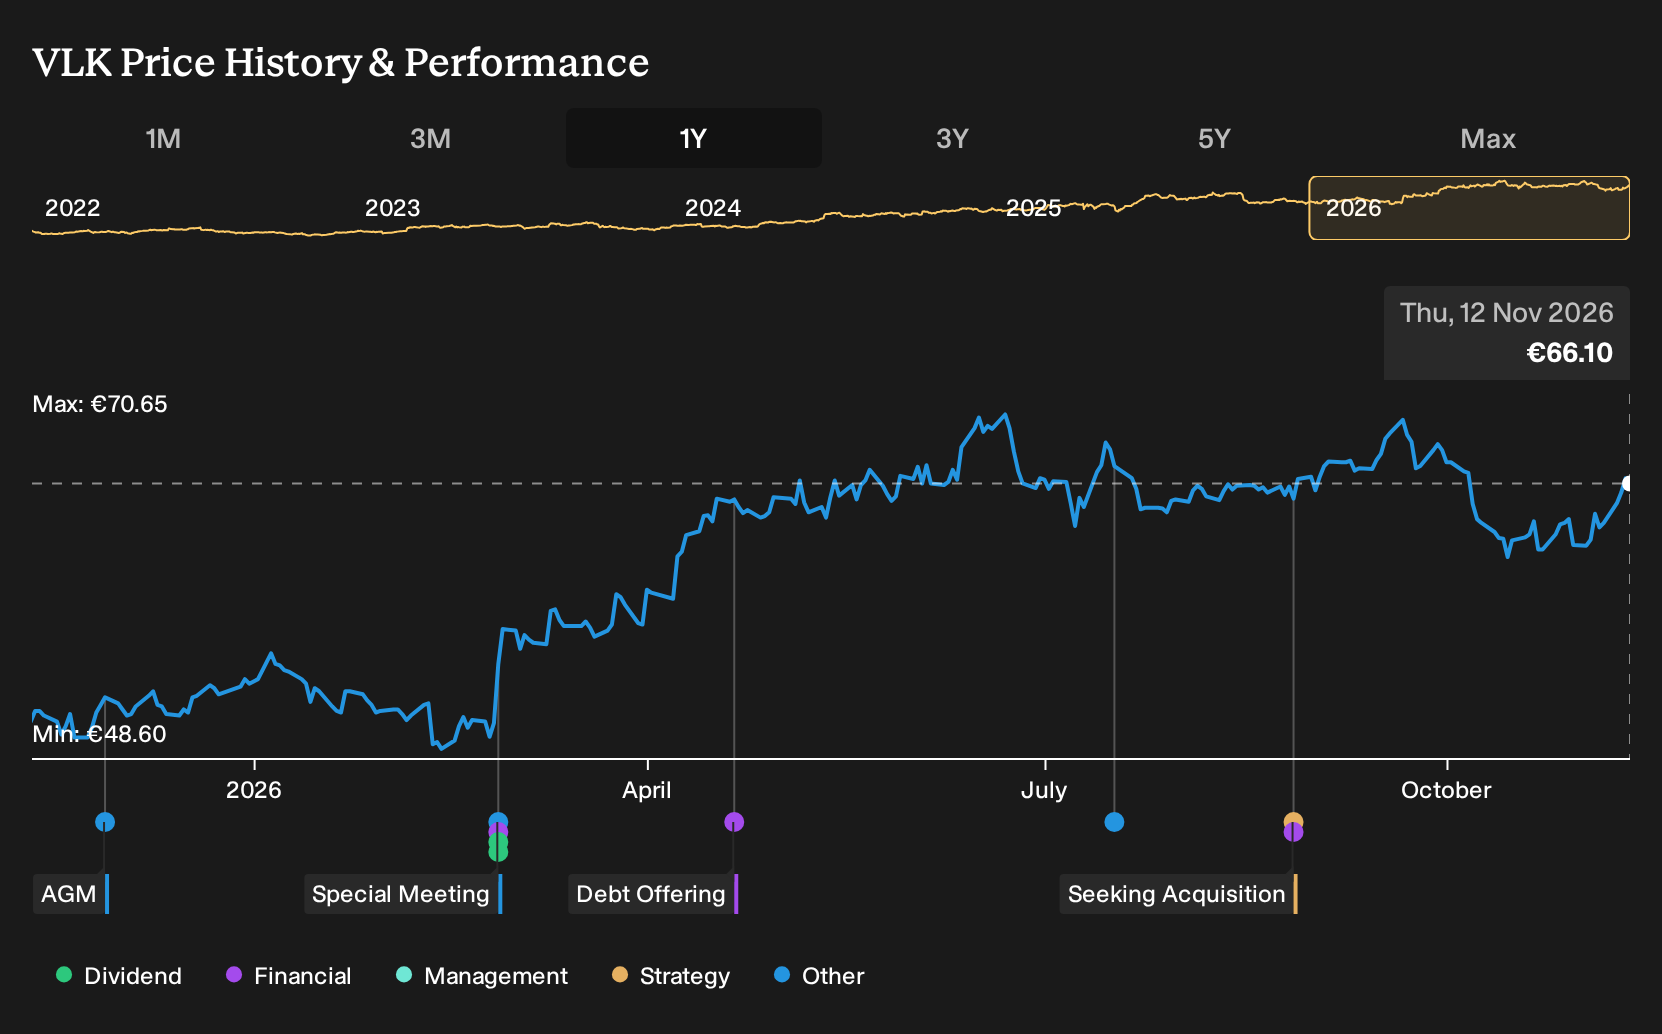
If Van Lanschot Kempen sat on your watchlist instead of in your account, the past year probably feels expensive. Investors who held Van Lanschot Kempen over the past year are up 37.0%, including dividends. That outcome arrived after years of debate about whether Europe’s wealth transfer and ESG tilt could genuinely support higher quality fee income and better profitability. The real puzzle is straightforward. Which early assumptions about scalable private banking and digital advice would have signalled that this surge was more than wishful thinking?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
If the move has made Van Lanschot Kempen harder to judge, start where the gap is still open and scan 194 high quality undervalued stocks.
The Two Van Lanschot Kempen Stories Investors Were Arguing Over
The shares cost €51.1 at the start of the period, and anyone looking at Van Lanschot Kempen then had to choose between two very different stories about the same private banking platform.
On the bullish side, the Fair Value of €57 rested on the idea that Europe's wealth transfer would support scalable private banking, with digital tools like the Evi Robeco platform helping to lift recurring fee income and operating leverage.
The bearish Narrative pointed to a Fair Value of €44.5 and stressed that rising fintech competition, heavier European regulation, and ongoing legacy IT costs could keep margins under pressure and limit long term earnings progress.
What The Results Changed For The Van Lanschot Kempen Debate
Van Lanschot Kempen reported H1 2026 revenue of €411.456m and net income of €83.693m, with net margin at 20.3% versus 17.1% a year earlier. That mix of higher profit and wider margin supported the optimistic story about scalable wealth management economics, although bears still had room to argue that heavier regulation and competition remained untested by this single period.
The hinge assumption was profitability from a more scalable model. When you look at other wealth managers, track net margin and earnings per share together, and compare those figures with earlier claims about operating leverage, rather than taking revenue growth alone as proof.
What Van Lanschot Kempen's Run Has Priced In
With Van Lanschot Kempen now trading at €66.1, the analyst consensus Narrative on Simply Wall St still places its Fair Value above the current price.
That view leans on an AUM focused, capital light wealth model that uses AI and higher margin private markets. The question is whether strong net AUM inflows and operating leverage really persist at recent levels.
"The main requirement for this thesis is that Van Lanschot Kempen maintains strong net AUM inflows and operating leverage, including continued adoption of AI tools and expansion in private markets and fiduciary mandates, while keeping the cost/income ratio close to current levels."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Before The Next Story Makes Headlines
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 28% below our estimate - focuses on opening quick payback boutiques while scaling higher margin digital and app sales.
- Company 2 - 29% below our estimate - uses a single tech stack and AI tools to capture more platform inflows.
- Company 3 - 32% below our estimate - expands fee earning access to renewable projects and tax efficient private capital vehicles.
That is three of the list. See the full list of 199 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com