


AI focused electronics trade is surging across Asia, and that ripple is reaching smaller corners of the UK market where early stage shares still trade under £5. When heavyweight capital chases AI infrastructure and supply chains, attention can spill into financially healthier low priced stocks that many investors overlook. This article walks through three UK penny stocks screened for stronger balance sheets and cash discipline.
The three stocks highlighted here offer a compelling starting point if you want exposure to lower risk early-stage businesses built on stronger financial footing. However, if you want the pick of this theme, these 19 elite penny stocks are the best of the best.
Ashmore Group (LSE:ASHM)
Overview: Ashmore Group is a London based asset manager running pooled funds and mandates focused on emerging market bonds and equities for global clients.
Operations: Ashmore generates about £139 million from investment management services, with roughly £88 million from the UK and Ireland, £30 million from Asia and the Middle East, and £26 million from the Americas.
Market Cap: £1.4 billion
Ashmore Group brings the Financially Fit Penny Stocks theme to life by giving you access to diversified emerging market debt and equity portfolios, and the analyst consensus Narrative on Simply Wall St frames how current client activity is shaping that story.
"Client activity levels at Ashmore Group are now reflected in rising subscriptions of about $12.5b for FY 2026 and the lowest redemptions in over 10 years. Any further improvement in net flows could add to management fee revenue, while a reversal would quickly pressure fee income and keep the stock grounded."
What happens if one quiet shift in fee pressure and product mix tilts the balance between resilient earnings and a far thinner margin cushion?
That margin question is exactly what the full narrative for Ashmore Group tackles head on, showing where fee trends, flows and product mix could quietly reshape Ashmore Group’s earnings profile.

IntegraFin Holdings (LSE:IHP)
Overview: IntegraFin Holdings runs the Transact wrap platform and adviser software that help UK financial advisers administer and consolidate client investments efficiently.
Operations: The group generates about £82 million from Investment Administration Services, £79 million from Insurance and Life Assurance, and £5 million from Adviser Back-Office Technology, mostly in the UK.
Market Cap: £1.3 billion
IntegraFin Holdings fits the Financially Fit Penny Stocks theme because Transact is built to handle real client money in a controlled, tax-efficient wrapper, giving advisers cleaner administration when they include smaller, higher risk holdings in diversified portfolios, according to the analyst consensus Narrative on Simply Wall St.
"Strong Transact net inflows and client growth remain a live driver, with recent periods showing record gross inflows and funds under direction above £80b, which expands IntegraFin Holdings’ recurring fee base and supports revenue."
One unresolved pressure on costs and pricing could quietly influence how much of that inflow growth ultimately turns into lasting profitability.
That cost question is exactly where the IntegraFin Holdings story gets interesting, and the full narrative for IntegraFin Holdings shows how pricing power and platform scale could keep earnings momentum accelerating.

Currys (LSE:CURY)
Overview: Currys runs an omnichannel chain of Currys and Elkjøp stores and websites selling budget friendly consumer electronics, mobile plans and repair services across Northern Europe.
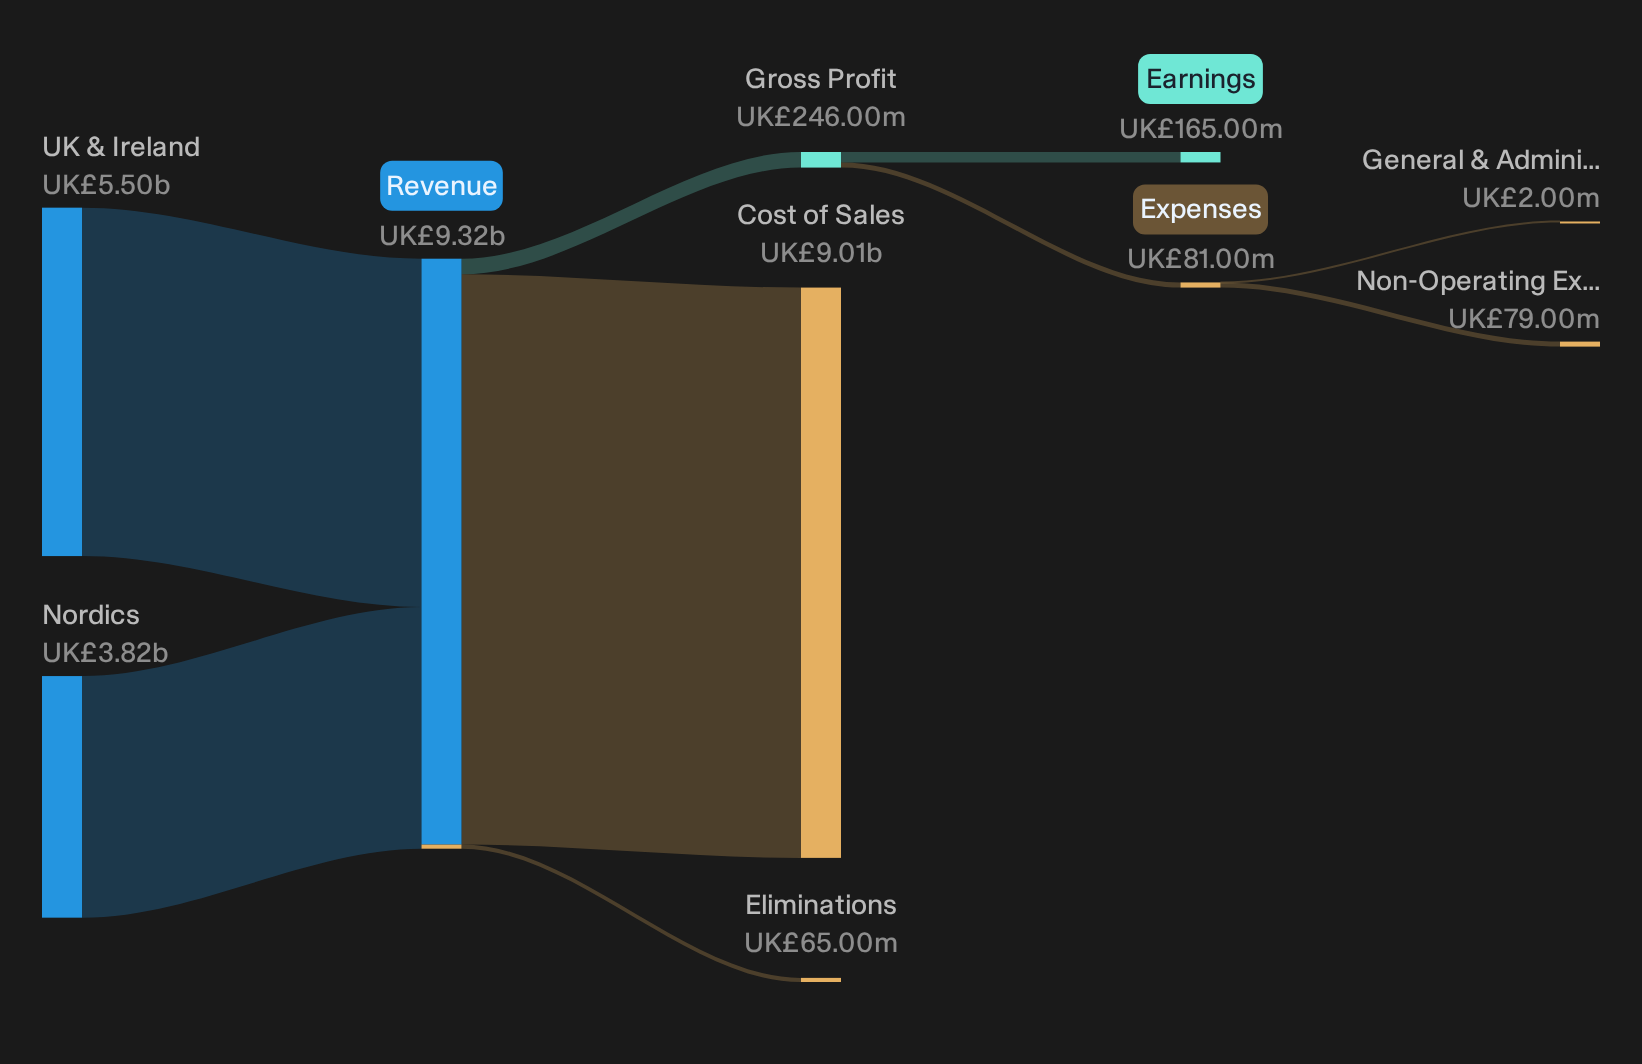
Operations: Currys generates about £5.5b from the UK and Ireland and £3.8b from the Nordics, with smaller eliminations in group reporting.
Market Cap: £1.5b
Currys matters for the Financially Fit Penny Stocks theme because iD Mobile and its value electronics ranges target budget focused shoppers, while the analyst consensus Narrative on Simply Wall St highlights how recurring services and credit could reshape the quality of those earnings.
"Expansion of higher margin recurring services such as credit, installations, connectivity and repair, which now account for over 30% of UK revenue and have been growing faster than product sales, can keep lifting Currys group revenue quality and EBIT margins as more customers shift into these offers."
The real test is how one subtle shift in customer behaviour toward these recurring offers eventually feeds through to cash flow and valuation resilience.
That shift in behaviour is exactly where the Currys story starts to accelerate, and the full narrative for Currys shows how recurring services could decouple earnings quality from pure hardware cycles.
Seeking Fresh Alternatives Before Others?
Some of the most interesting stories start moving quietly, then break out once momentum is obvious. Scan these fresh ideas before the crowd catches on and consider your options early.
- Spot potential breakout value by running a tight filter on quality and price using the 15 high quality undervalued stocks while the list still flies under most radars.
- Track where real earnings power meets AI momentum by scanning the 43 profitable AI stocks that aren't just burning cash before these cash generative stories become more widely recognized.
- Build a watchlist of sturdier balance sheets with the curated list of solid balance sheet and fundamentals (9 results) to help reduce exposure to more fragile businesses when sentiment drops.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com