


Wholesale inflation in the US recently hit its highest annual rate in nearly four years, reminding investors that rising prices and interest rates can punish cash sitting on the sidelines. Reliable income from mature British dividend stocks can feel far more useful in that setting. This article highlights three high-yield UK companies from a focused screener that targets dividends above 3% that look well covered, growing and relatively steady.
The three stocks highlighted here offer a compelling starting point if you want exposure to higher-yielding dividend payers that aim for well covered, growing and relatively steady payouts. However, if you want the standouts, these 4 dividend aristocrats stocks are the most outstanding.
RHI Magnesita (LSE:RHIM)
Overview: RHI Magnesita supplies refractory linings and related engineering services for high temperature industrial processes, a recurring, contract driven business that supports its role in a 3%+ dividend yield screen.
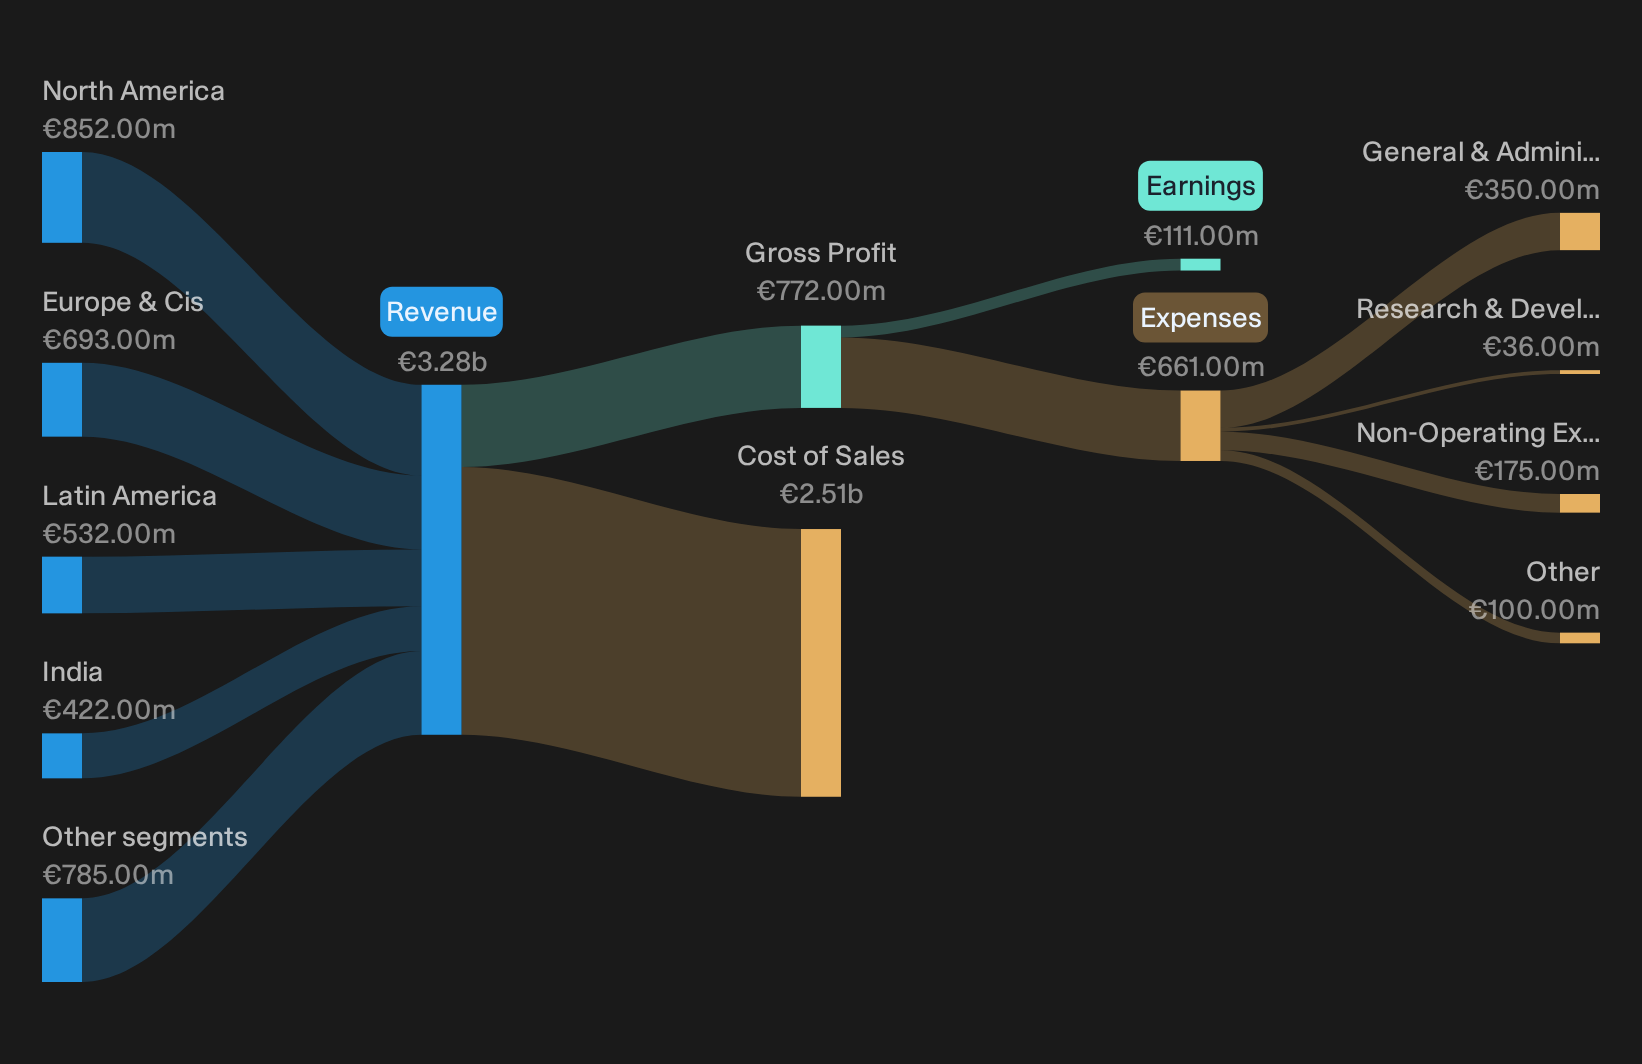
Operations: The group generates around €3.3b of revenue, led by North America (€852 million), Europe & CIS (€693 million) and Latin America (€532 million), with additional contributions from India, China & East Asia, Minerals and Middle East, Türkiye & Africa.
Market Cap: £1.3b
RHI Magnesita fits this Dividend Powerhouses theme because its refractory linings and services are tied to recurring work at steel and cement plants. The analyst consensus Narrative on Simply Wall St now focuses on how that industrial backbone interacts with its cost and recycling moves.
"The company's leadership in developing circular economy solutions via new recycling infrastructure is still intended to attract more ESG focused customers and reduce raw material cost exposure. This can support both sales volumes and gross margins as recycling usage increases."
What matters next is how one pressure point in its cost base settles, because that could reshape the trajectory of future profitability.
That cost reset is the real swing factor, and the full narrative for RHI Magnesita shows how recycling gains, contract structure and capital plans could accelerate or cap the next phase for RHI Magnesita.
Man Group (LSE:EMG)
Overview: Man Group runs global investment strategies across equities and alternatives, earning recurring management and performance fees that support its dividend profile.
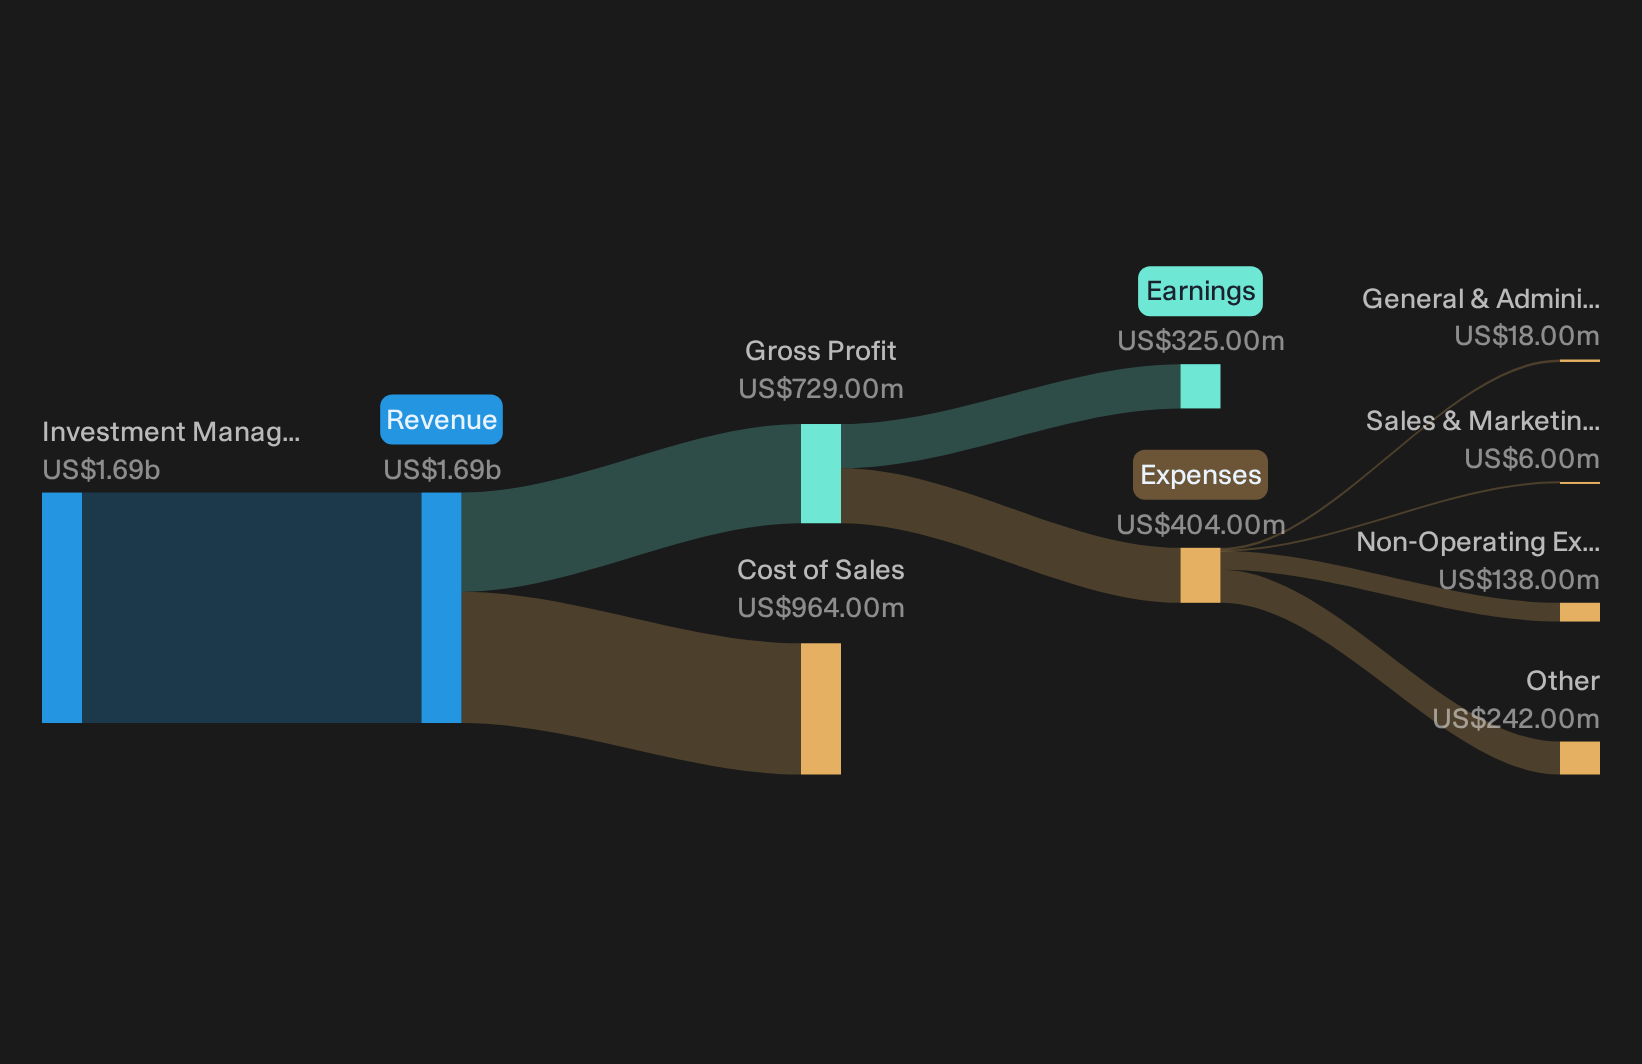
Operations: The investment manager generates about $1.7b of revenue from its Investment Management Business, which provides fee income from managing client assets.
Market Cap: £3.5b
Man Group matters for a dividend focused screen because its fee based investment engine can convert client assets into regular cash flows. The analyst consensus Narrative on Simply Wall St frames how that fee pool might evolve as the product mix and client base shift.
"Continued build out of the credit and private credit platform, including over $60b of credit AUM and $17.6b in private credit by mid 2026 plus $4.9b of uncalled committed capital, gives scope for further deployment that can support fee revenue and diversify profit drivers."
What really shapes the appeal of Man Group’s dividend from here is how one underappreciated pressure on its fee margins ultimately resolves.
That margin pressure is the crux, and the full narrative for Man Group shows how fee rates, capital returns and overlooked optionality could still accelerate Man Group’s income story.
Grafton Group (LSE:GFTU)
Overview: Grafton Group runs a broad building materials and merchanting network across Ireland, the UK and continental Europe, supplying trade professionals and homeowners with construction products, plumbing and heating lines, tools and home improvement ranges that underpin its covered, growing dividend.
Operations: The group generates about £2.6b of revenue, led by the Island of Ireland at roughly £1.1b, Great Britain at £746 million, Northern Europe at £478 million and Iberia at £254 million.
Market Cap: £1.9b
Grafton Group matters for the Dividend Powerhouses screen because its trade and merchanting arm turns everyday building and refurbishment demand into repeat cash flows that support a 3%+ yield. The analyst consensus Narrative on Simply Wall St now focuses on how expansion in Iberian heating and ventilation could reinforce that income story.
"Grafton Group's continued build out of its Iberian HVAC platform, now including both Salvador Escoda and Mercaluz with around 120 branches and a shared focus on own brand products, allows further branch openings, new customer channels and exports to support higher revenue and EBITA margins in the region."
What really matters for dividend investors is how one unresolved margin pressure across parts of the wider network ultimately shapes that Iberian opportunity.
That margin question is the hinge, and the full narrative for Grafton Group maps how Grafton Group’s Iberian build out, pricing power and capital choices could be quietly accelerating the whole dividend story.

Seeking Fresh Alternatives Beyond Dividends
Fresh ideas move first. When the next breakout list starts gaining momentum, late arrivals get caught chasing what is already flying. Scan these picks while it matters and get in early.
- Spot under the radar income plays and review 4 dividend fortresses that aim to keep yields flowing even when prices drop or headlines turn noisy.
- Track where real AI momentum could build and scan 43 profitable AI stocks that aren't just burning cash that already pair revenue with cash generation instead of burning capital.
- Position ahead of critical infrastructure shifts and sift through 44 power grid technology and infrastructure stocks before grid upgrade spending moves from planning slides to full speed execution.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com