


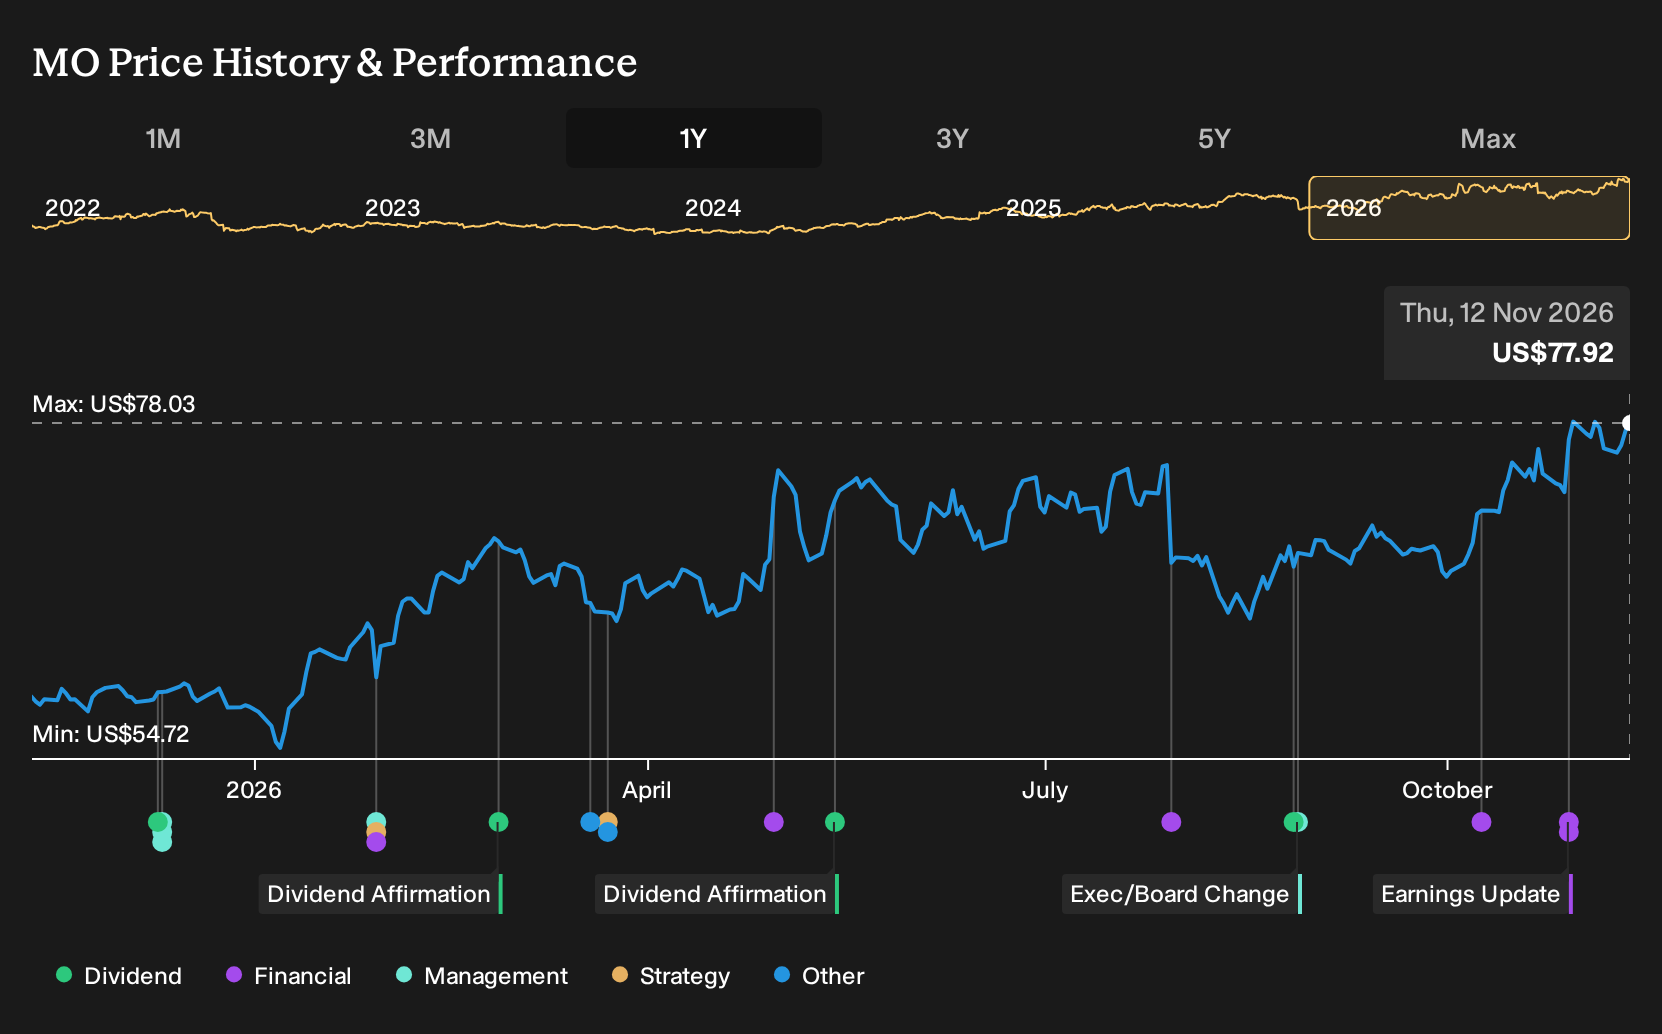
If you only glanced at headlines about cigarette declines and regulatory probes, Altria Group might have looked like a stock to avoid. For Altria Group shareholders, the return over the past year was 43.9%, including dividends. That is a striking outcome for a business facing falling volumes, FDA scrutiny and competition from smoke free rivals. If you had been weighing those risks back in November 2025, what information really mattered?
If the move has made Altria Group harder to judge, start where the gap is still open and scan 32 high quality undervalued stocks.
The Two Altria Group Stories Investors Had To Weigh
The shares cost US$58.05 at the start of the period, and the debate around Altria Group was about which story on earnings and regulation would prove closer to reality.
The bullish narrative saw a Fair Value of US$62.88. This was a price implied by assumptions such as a future P/E of 13.8x and a profit margin of 45.2%, supported by confidence in tobacco profitability and dividends.
The cautious view pointed to a Fair Value of US$49.58. This was based on concerns that illicit e vapor, regulatory hurdles, and cigarette declines could pressure margins and smoke free goals.
What The Results Changed For The Altria Group Debate
The clearest new fact was Altria Group lifting Q3 revenue from US$5,251m in 2025 to US$5,441m in 2026, while net income also rose, taking net margin from 45.1% to 46.2%. That outcome leaned toward the bullish story that assumed resilient profitability. Investigations into disclosures around on! PLUS and lowered 2026 guidance pulled the other way. Overall, the evidence cut both ways.
The single assumption that really got tested was earnings durability. For a different stock, check whether revenue, absolute profit and margin are all moving in the direction the original thesis required, not just one of them.
What Altria Group’s Price Already Assumes
Today Altria Group changes hands at US$77.92. The bearish analyst Narrative on Simply Wall St puts its Fair Value below that level, based on a view that the current quote builds in generous assumptions about earnings resilience.
That storyline leans on concerns that smoke free profits and legal risks could strain the business that funds those expectations. Anyone paying today’s price is effectively betting that high margin combustibles and on! earnings can keep supporting that outlook despite those pressures.
"The current numbers imply a share price that treats Altria Group as if resilient EPS guidance, high smokeable margins and large cash returns to shareholders can continue without material disruption from regulatory actions, litigation or mix shifts inside the smoke-free portfolio."
The price and this Narrative do not agree. → Uncover what this Narrative says Altria Group is actually worth
Beyond Altria Group’s Cigarettes
Watching Altria Group means watching one type of long-lived cash flow, based on products facing rising regulatory questions.
One step away, a very different business also leans on long contracts, centered on complex infrastructure and nuclear projects.
The work moves slowly, remains highly specialized and follows client spending plans rather than consumer demand swings.
Execution quality, not shipment volumes, determines how and when value appears.
Your question narrows and deepens together: how should tobacco cash flows sit alongside nuclear and infrastructure projects still unfolding?
The argument comes with a number attached. → Uncover the nuclear energy company trading 22% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com