


- Globalstar secured long term French government approvals for its third generation C 3 mobile satellite system, covering Big LEO spectrum usage, launch, and operation of a 48 satellite LEO constellation plus in orbit spares supported by a global ground antenna network.
- The French and broader multi country authorizations, now spanning more than 20 jurisdictions and over one billion people, materially expand Globalstar's addressable footprint for direct to device services and future IoT connectivity contracts.
- Attention now shifts to what this wider C 3 regulatory footprint could mean for Globalstar's investment narrative and capital heavy execution.
Scan other potential beneficiaries of the satellite and direct to device shift by checking our curated list of 53 AI infrastructure stocks alongside Globalstar today.
Globalstar Investment Narrative Recap
To own Globalstar, you need to believe the C 3 constellation, D2D services and IoT modules can turn heavy satellite and ground spend into durable service revenue, not just headlines. The French C 3 approvals widen the regulatory runway, but the immediate operating story still hinges on filling that capacity with paying users.
The analyst consensus Narrative on Simply Wall St highlights high capex and deployment timing as key pressure points. Recent quarterly numbers showed revenue at US$70.9 million and a net loss of US$15.68 million, so in the near term the biggest swing factor is whether management can fund the buildout without stretching the balance sheet.
The most relevant recent announcement is the French authorization for Globalstar’s C 3 system across the Big LEO band for 20 years and for the constellation’s 13 year design life. That cements regulatory backing for 48 operational LEO satellites plus in orbit spares and 89 ground antennas, which directly underpins the C 3 rollout described in the analyst consensus Narrative on Simply Wall St.
For you as an investor, this matters because many of the cited catalysts, from government connectivity contracts to higher IoT usage, rely on that C 3 capacity actually being available and compliant. The approval does not reduce capex intensity or execution risk by itself, but it removes an important regulatory doubt and shifts attention back to launch timing, commercialization and cash burn.
Globalstar Forecasts and What Needs To Go Right
Globalstar's narrative projects US$469.8 million in revenue and US$136.4 million in earnings by 2029. This is based on an assumption of 19.2% yearly revenue growth and a projected earnings swing of about US$215.7 million from a current earnings loss of US$79.3 million.
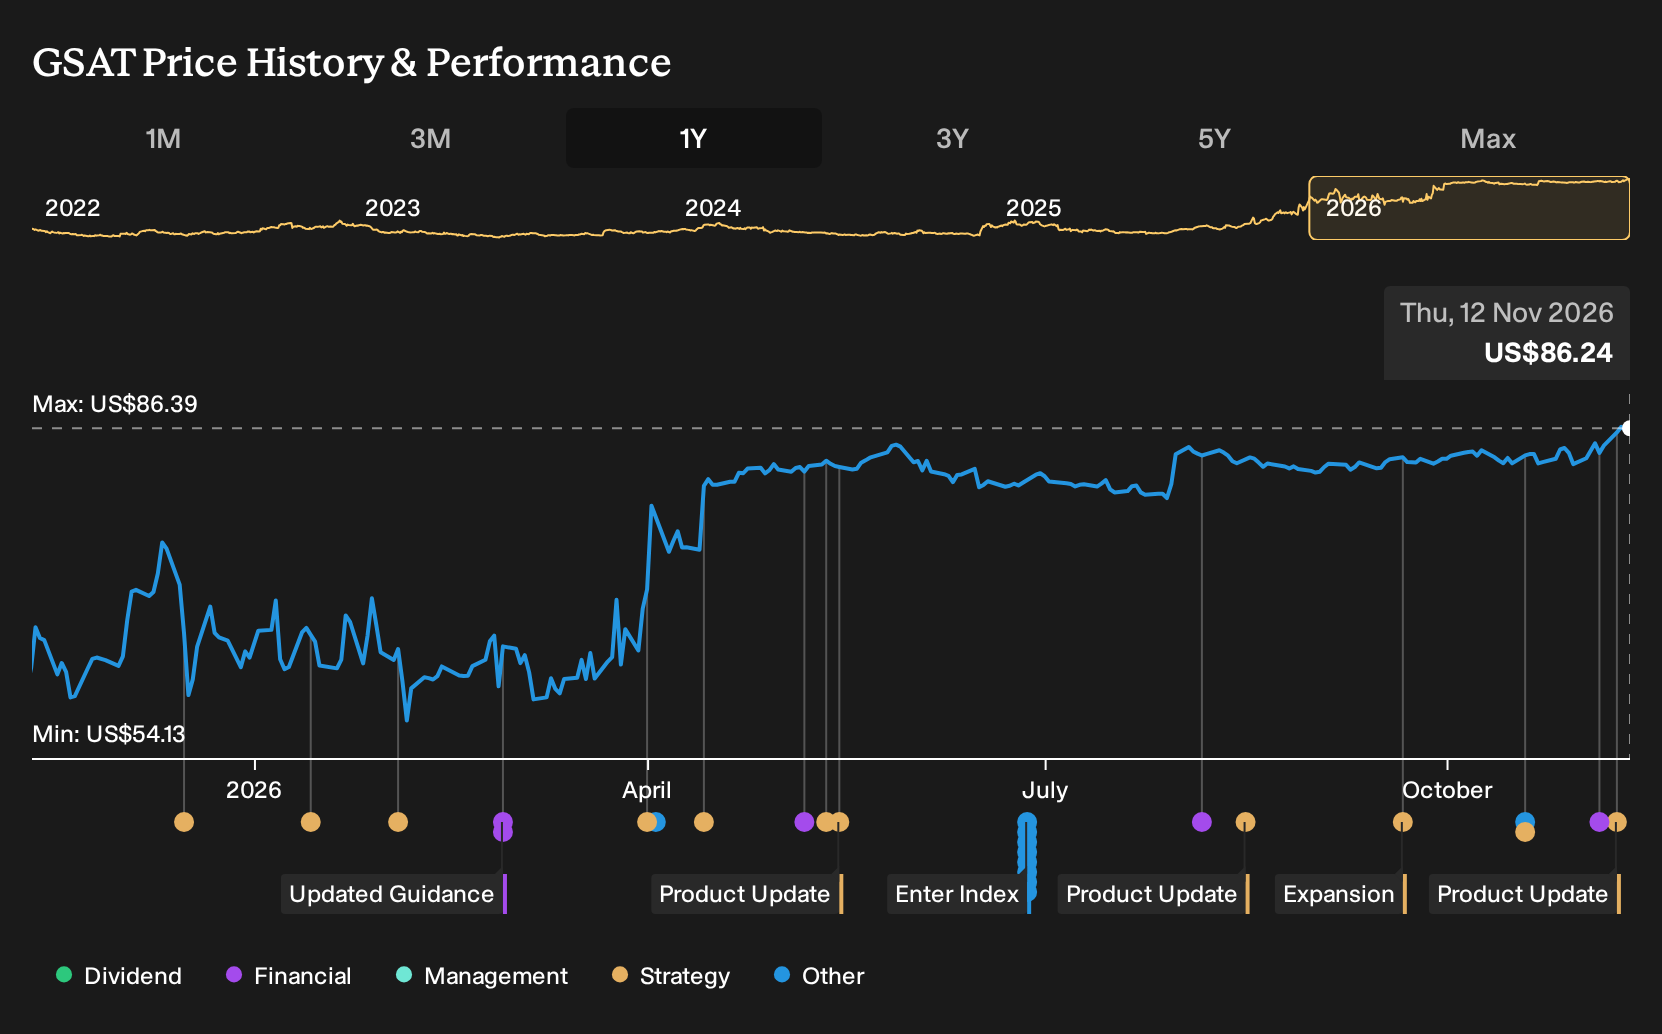
Uncover how Globalstar's fair value suggests a 4% potential upside to its current price before the market closes the gap.
Exploring Other Perspectives
The most cautious analysts focus on Globalstar's risk that heavy C 3 spending may never translate into strong free cash flow. Before this French approval, the lowest forecasts still indicated about US$465.2 million of revenue and US$130.6 million of earnings by 2029, yet described that as optimistic given ongoing losses. Use that range of opinions as a prompt to compare several narratives yourself, especially now that fresh regulatory news could reshape them.
Explore 5 other Globalstar fair value estimates, including one that suggests as much as 94% downside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Globalstar research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Globalstar. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Globalstar's overall financial health at a glance.
Looking for more investment ideas beyond Globalstar?
Once you have a view on Globalstar, it can help to compare it against other opportunities that fit different risk and income profiles using the Simply Wall St Screener.
- If you prefer lower volatility and steadier business models, scan a curated group of 29 resilient stocks with low risk scores that might suit a more defensive approach.
- For investors focused on quality at a reasonable price, line up potential candidates from a 32 high quality undervalued stocks and see how their metrics stack up against Globalstar.
- If you want to back resilient balance sheets and durable fundamentals, test your thesis across a list of solid balance sheet and fundamentals (23 results) to round out your watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com