


Madrigal Pharmaceuticals has produced very strong long term returns, and recent headlines around its liver drug Rezdiffra and related whistleblower allegations have pushed the valuation debate back to center stage. With the share price around US$425, investors are asking whether the current market tag can be grounded in the company’s sales profile.
- Over the past 5 years the stock has delivered a gain of about 416.0%, which puts a lot of weight on whether the present price still lines up with the underlying revenue base.
- Rezdiffra crossing a US$1b year to date sales milestone and helping Madrigal turn profitable brings the timing and durability of future product revenue into sharp focus for anyone thinking about what multiple of sales is sensible.
- There is a second opinion on Madrigal Pharmaceuticals worth weighing. See what analysts think Madrigal Pharmaceuticals's shares could be worth.
The issue now is whether Madrigal Pharmaceuticals’ current share price is adequately supported by its sales when judged against the Fair Ratio benchmark.
If you are weighing whether Madrigal Pharmaceuticals’ current tag around US$425 is reasonable for its sales profile, it can help to compare that theme against a basket of 32 high quality undervalued stocks.
Is Madrigal Pharmaceuticals a Bargain on Sales?
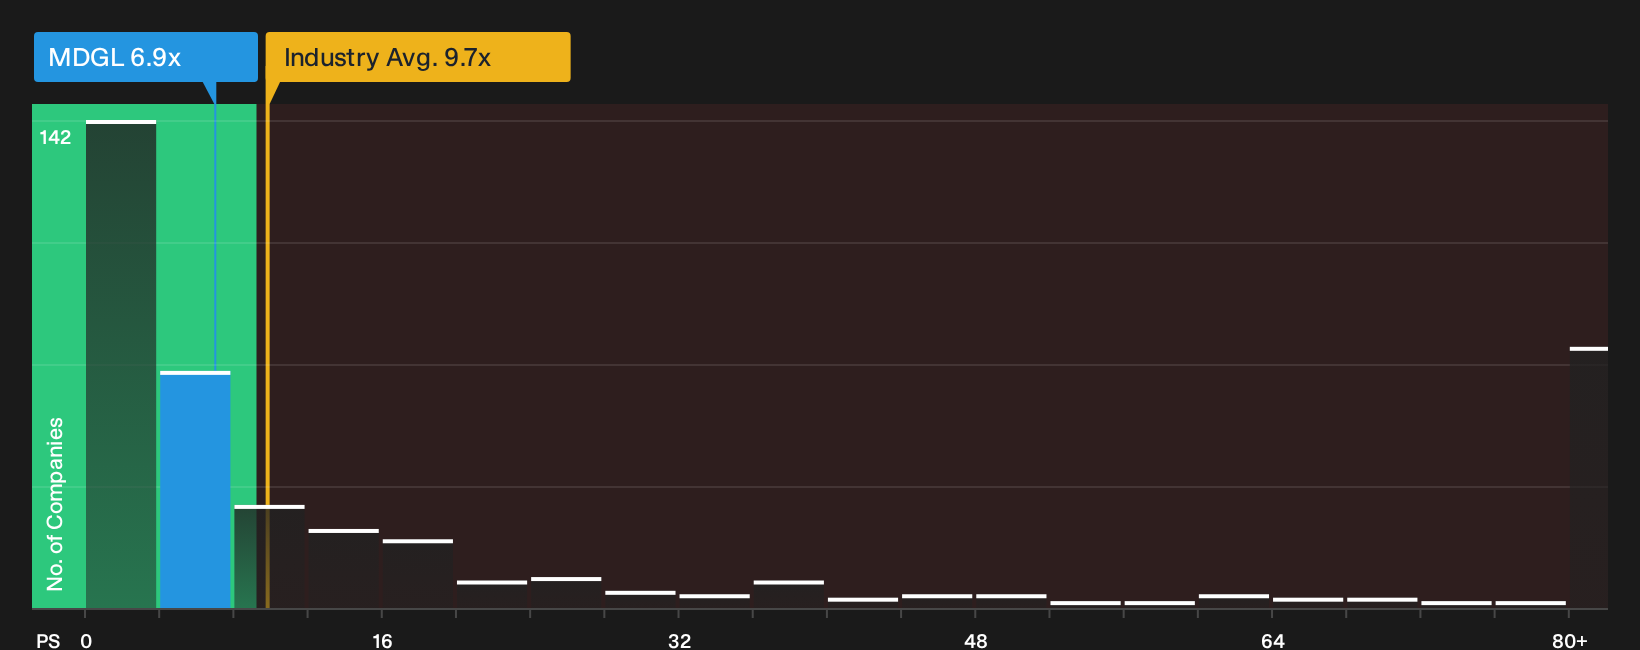
P/S is usually the cleanest yardstick for a biotech like Madrigal Pharmaceuticals because revenue is more stable than earnings while investment in trials and launches runs high. On this measure, the stock trades on a P/S of about 6.9x, compared with roughly 9.7x for the broader biotechs industry and about 20.2x for its closer peer group.
The Fair Ratio framework, which aims to capture a valuation level that fits Madrigal Pharmaceuticals’ growth profile, margins, size and risks, points to the current sales multiple as being below what that model would imply. Because the whistleblower investigations have put a spotlight on Rezdiffra and potential legal or regulatory outcomes, the gap to that Fair Ratio will matter most to readers who think long term commercial and compliance risks are already reflected in the P/S tag. Explore the numbers behind Madrigal Pharmaceuticals's P/S valuation.
The Madrigal Pharmaceuticals Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Madrigal Pharmaceuticals pick up where the P/S puzzle leaves off. They spell out which combinations of future growth, profitability and earnings power would need to hold for the stock to look meaningfully richer or cheaper than today’s share price on the Community page. Each scenario attaches a fair value estimate to a particular mix of potential catalysts and risks so you can see over time which version of Madrigal Pharmaceuticals' story is actually unfolding.
One of the top narratives on Madrigal Pharmaceuticals: 38% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The rapid uptake and long term patent protection of Rezdiffra, now supported by additional Orange Book listed patents and guidance that coverage is expected into 2045…"
Discover why this Narrative puts Madrigal Pharmaceuticals at 38% undervalued.
One more angle on Madrigal Pharmaceuticals that could change the story
Numbers only tell part of what you own with Madrigal Pharmaceuticals, because the people setting priorities and how they are rewarded can tilt the whole risk and reward balance for years. See who runs Madrigal Pharmaceuticals and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com