


Lindblad Expeditions Holdings has delivered a very strong share price run in recent years, which naturally puts the focus on whether the current US$34.13 level can be backed up by its sales base. With the stock now far higher than it was a few years ago, the key issue for you is how the business it runs across expeditions and experiential travel lines up against that market value.
- Over the past 3 years the stock has returned about 3.5x, so a lot of optimism is already embedded and that puts more weight on what its sales can reasonably support.
- Record recent revenue performance and the acquisitions of White Desert and Echo Charlie point to a broader platform that can influence future sales growth, margin mix and the scale needed to service its current equity valuation.
- Your read on Lindblad Expeditions Holdings is one view; the desks covering it have another. See what analysts think Lindblad Expeditions Holdings's shares could be worth.
The issue now is whether the current Lindblad Expeditions Holdings share price is justified by the sales the business is generating today and what investors are assuming those sales will look like over time.
If you are questioning whether Lindblad Expeditions Holdings at US$34.13 is fairly reflected in its sales, it can help to compare that same sales lens across solid balance sheet and fundamentals stocks screener (23 results).
Does Lindblad Expeditions Holdings Look Pricey on Sales?
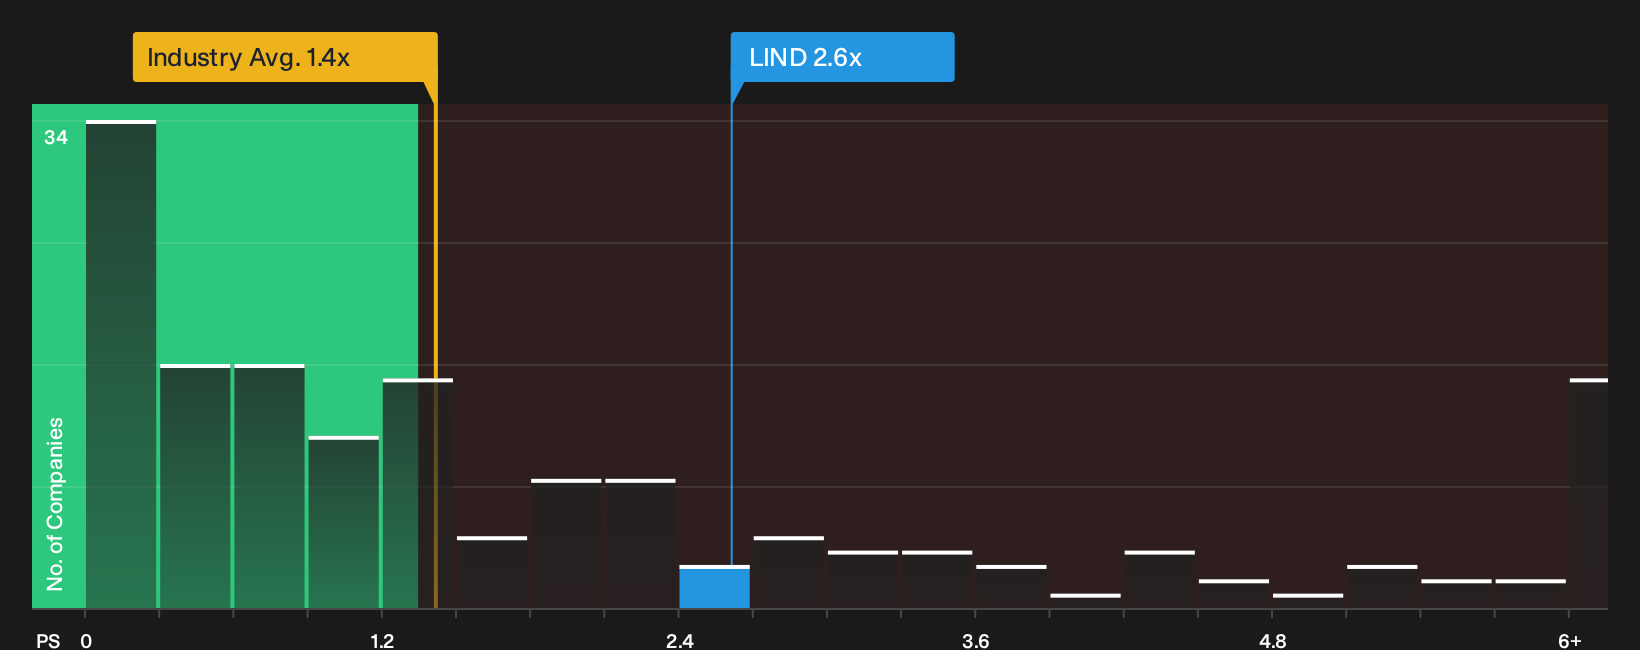
P/S fits Lindblad Expeditions Holdings quite well because investors often focus on revenue for travel operators that reinvest heavily and can show volatile earnings. The stock trades on a P/S ratio of 2.6x, which is higher than both the hospitality industry average of 1.4x and the peer group at 1.8x. That gap suggests buyers today are paying a richer price for each dollar of Lindblad Expeditions Holdings revenue than for many comparable businesses.
The Fair Ratio, which blends the company’s growth profile, margins, size and risk into a tailored benchmark, points to the current 2.6x P/S being above the level implied by those fundamentals. Because record Q3 2026 results and the White Desert and Echo Charlie deals have already lifted expectations, this premium multiple assumes that the recent momentum in Lindblad Expeditions Holdings is worth paying extra for on a sales basis. Explore the numbers behind Lindblad Expeditions Holdings's P/S valuation.
The Lindblad Expeditions Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle for Lindblad Expeditions Holdings leaves off, by spelling out what kind of future revenue, margin and earnings profile would need to unfold for the stock to be worth materially more or less than it trades for today on the market. Each narrative sets out Lindblad Expeditions Holdings' implied fair value as a thesis about the business that you can track over time instead of treating it as a one-off snapshot.
Bullish and bearish narratives on Lindblad Expeditions Holdings are closely aligned on the business itself, but they disagree on how much the current optimism should be reflected in the share price.
Bull case: 21% undervalued
The bullish analyst narrative on Simply Wall St focuses on how added capacity and cost initiatives could reshape Lindblad Expeditions Holdings over time.
"The company’s growing pipeline of 20 to 30 plus cost initiatives, including fuel efficiency programs and contract renegotiations, creates room for a second phase of margin improvement…"
Discover why this Narrative puts Lindblad Expeditions Holdings at 21% undervalued.
Bear case: 14% overvalued
The bearish analyst narrative on Simply Wall St emphasizes the risk that higher running costs could eat into that improving sales base.
"Although bookings into 2027 and 2028 are pacing ahead and occupancy is high, sales and marketing expenses rising more than 20% year over year across early 2026…"
Explore why this Narrative puts Lindblad Expeditions Holdings at 14% overvalued.
Lindblad Expeditions Holdings still leaves one crucial piece of the puzzle unanswered
Everything here has focused on what Lindblad Expeditions Holdings looks like today, yet analyst models sketch a very different picture of where the business might be a few years from now. Explore where analysts expect Lindblad Expeditions Holdings to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com