


- United Utilities Group reported half year sales of £1,462 million and net income of £400.3 million to September 30, 2026, with basic earnings per share of £0.547 from continuing operations.
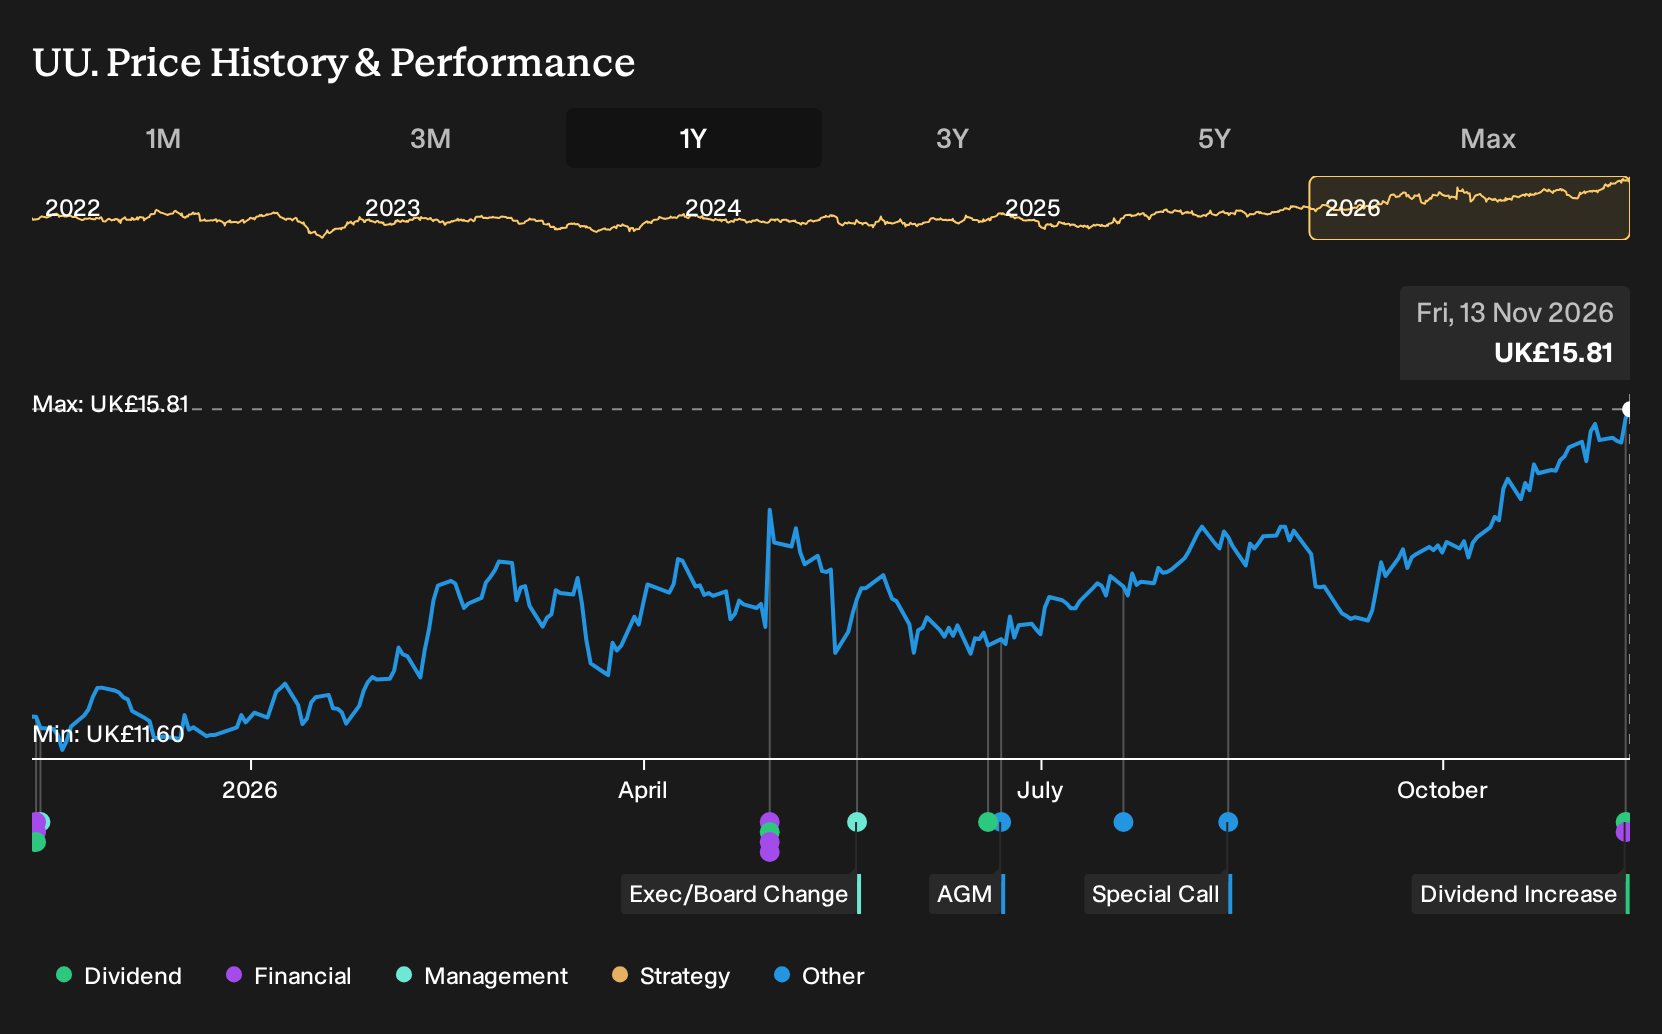
- The board raised the interim dividend by 3.5% to 18.51 pence per share, in line with its inflation linked dividend policy and substantial regulated capital investment programme.
- This article examines how United Utilities Group's reported half year earnings relate to its investment narrative and capital plans.
Scan beyond United Utilities Group and compare this earnings and dividend story with a hand picked 4 dividend fortresses that also focuses on income resilience and balance sheet strength.
United Utilities Group Investment Narrative Recap
To own United Utilities Group, an investor needs to be comfortable with a regulated utility that is leaning heavily into a very large capital programme while keeping cash returns flowing. The analyst consensus Narrative on Simply Wall St hinges on AMP8 spending, regulatory support and delivery on projects like the Big North West Upgrade. The latest half year, with £1,462 million of sales and £400.3 million of net income, shows the earnings base that is helping fund this.
The near term swing factor remains how rising operating costs and higher depreciation interact with allowed revenues and any credit rating pressure. Management flags around £100 million of extra operating expense and £50 million to £60 million more depreciation next year. If these outpace regulatory allowances, the risk is margin pressure rather than a fundamental break in the thesis.
The dividend announcement is central to this update. United Utilities Group lifted the interim payout by 3.5% to 18.51p per share, keeping to its CPIH linked policy while running what it calls its largest ever five year investment programme. That signals management is still aligning the income story with a capital intensive plan that includes more than £2b of expected investment this year.
For you as a shareholder, the key question is whether that distribution level sits comfortably alongside high gearing, capital commitments and ratings on a negative outlook. Debt is described as not well covered by operating cash flow, and free cash flows do not fully cover the dividend, so the raised interim payment makes the execution and funding of the AMP8 plan an even more important catalyst to watch.
United Utilities Group's current analyst narrative points to revenues of £3.1b and earnings of £774.7 million by 2029, based on an assumed 5.9% yearly top line expansion and an earnings increase of about £188 million from £586.8 million today.
Uncover why United Utilities Group's fair value indicates a 4% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span a wide band, from about £7.04 to £15.12 per share, which already shows how far private investors can disagree on United Utilities Group. Set that against ongoing credit rating pressure and a multi year AMP8 build out, and you are looking at opinions that can diverge sharply. Exploring more community viewpoints can help you stress test your own thesis.
Explore another United Utilities Group fair value estimate, including one that suggests as much as 55% downside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your United Utilities Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for United Utilities Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate United Utilities Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond United Utilities Group?
If the United Utilities Group story has sharpened your thinking on income, risk and capital intensity, it can help to contrast it with very different types of opportunities using the Simply Wall St Screener.
- For investors who want potential upside but still care about business quality and valuation, review a hand picked 6 high quality undiscovered gems that may not yet be widely followed by the market.
- If capital preservation and smoother portfolio behaviour matter most to you, focus on a curated 5 resilient stocks with low risk scores that screens for resilient balance sheets and lower volatility profiles.
- When reliable finances are your starting point rather than an afterthought, scan a targeted list of solid balance sheet and fundamentals (9 results) that filters for companies with stronger fundamentals supporting their future plans.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com