


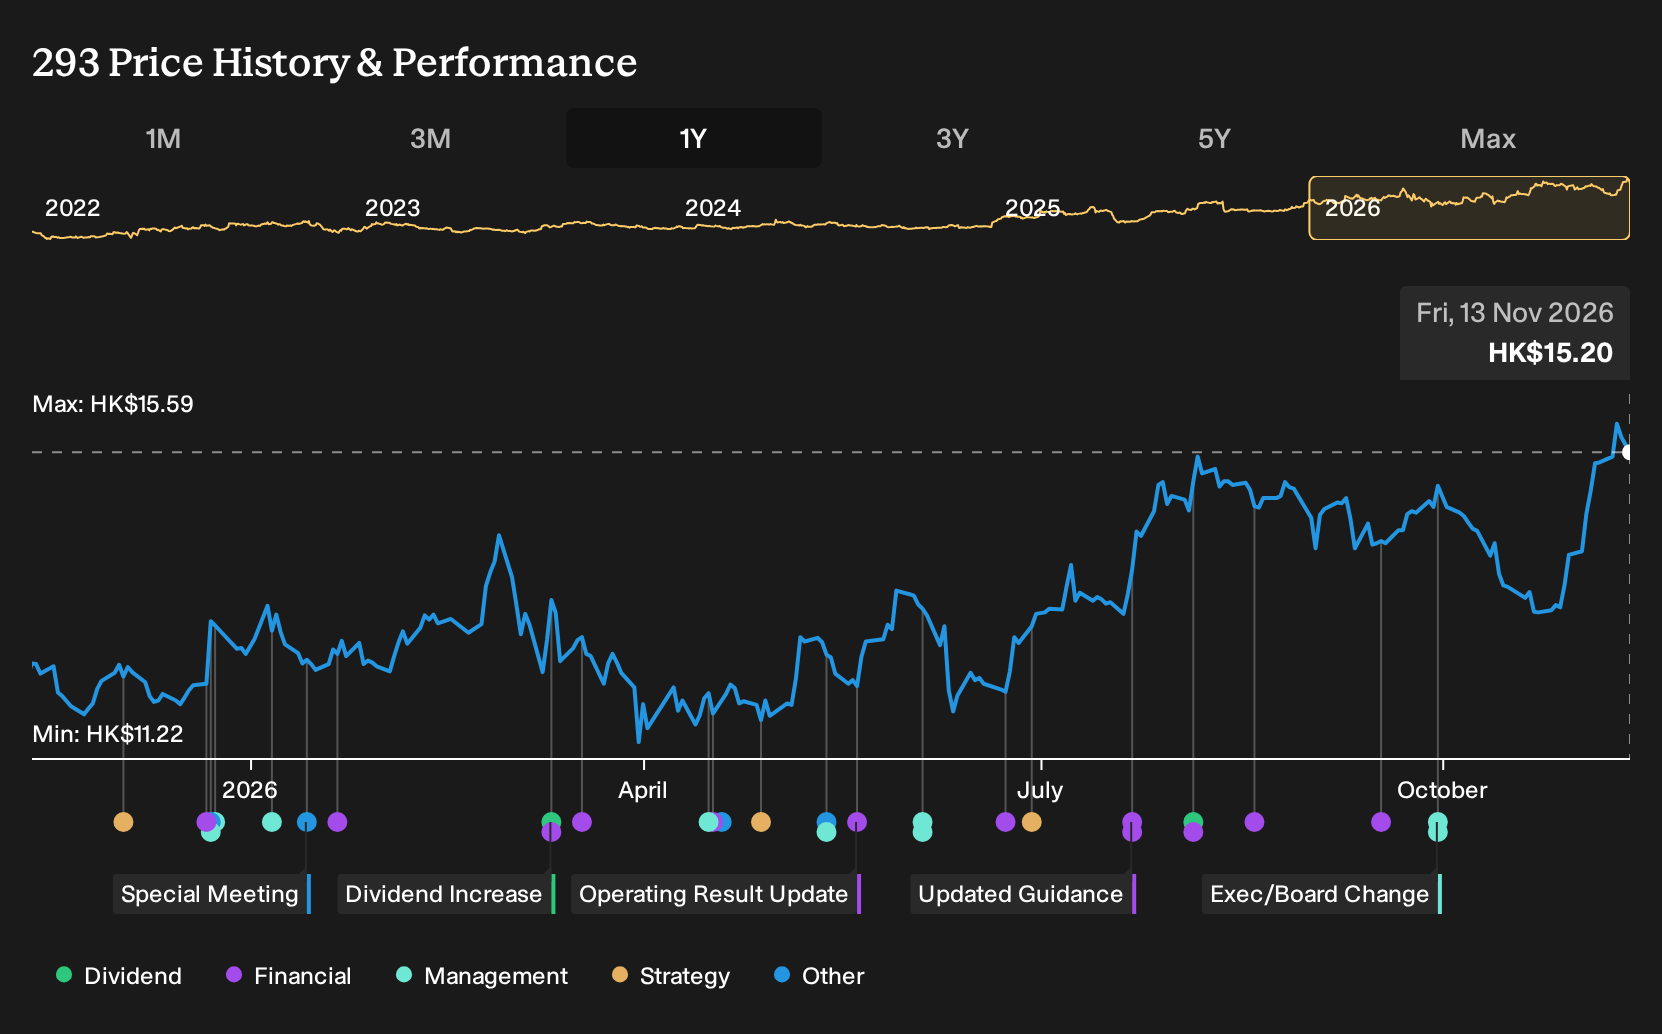
If you only skimmed the headlines about war-disrupted fuel supplies and suspended Middle East routes, Cathay Pacific Airways might have looked like one more airline stuck in the crossfire. For Cathay Pacific Airways shareholders, the return over the past year was 34.5%, including dividends. If you had been weighing those analyst debates about aggressive expansion, yield risk and fair value back in November 2025, what exactly did the subsequent year prove about this business?
The easy part of this move is behind Cathay Pacific Airways. Zero in on 195 high quality undervalued stocks for companies trading below our estimates.
The Two Stories Investors Were Choosing Between On Cathay Pacific Airways
The shares cost HK$12.29 at the start of the period, and anyone looking at Cathay Pacific Airways then had to decide which of two very different stories felt more convincing.
On the optimistic side, one narrative put a Fair Value of HK$13.1. This meant that price was implied if its assumptions played out, built around an expectation that a large aircraft order book and premium service focus would support faster route expansion than rivals.
The cautious view pointed to a Fair Value of HK$10.59. This was framed as the price implied by slower revenue growth assumptions and concern that aggressive capacity increases could pressure yields in the face of geopolitical risks.
What The Results Changed For The Cathay Pacific Airways Debate
Cathay Pacific Airways reported H1 2026 revenue of HK$68,061 million and net income of HK$6,243 million, with net margin at 9.2% versus 6.7% a year earlier. That profitability shift lent weight to the optimistic story that the aircraft order book and premium focus could support higher earnings. The halt to Middle East cargo and passenger flights, plus war driven fuel costs, gave the cautious case fresh evidence on route and cost risk. Overall, the data cut both ways.
The hinge assumption here was whether capacity and product investment would show up in richer profit quality. When you test a similar claim elsewhere, track net margin alongside top line and watch how management responds when routes or input costs are hit by geopolitics.
What Cathay Pacific Airways' Price Now Assumes
Today Cathay Pacific Airways trades at HK$15.2, with the one year return at 34.5%. The referenced Narrative’s Fair Value view sits below that level, so it treats the current quote as already baking in a lot of the recent progress.
According to PittTheYounger, a Simply Wall St Community investor who wrote the Narrative, the key angle is a strong cargo and passenger franchise that could still be exposed if fuel costs stay elevated for a long stretch. Anyone paying today’s price has to judge whether Cathay’s earnings can absorb a prolonged period of higher fuel without eroding that appeal.
"Yet should the Strait of Hormuz remain more or less closed for weeks and possibly months to come (a few escorted convoys won't change the maths here, mind), elevated fuel cost will have a negative impact on the whole industry's margins, and Cathay won't be an exception to the rule here."
The price and this Narrative do not agree. → Uncover what this Narrative says Cathay Pacific Airways is actually worth
Looking Beyond Cathay Pacific Airways
Cathay Pacific shows how established airlines juggle fuel costs and route exposure. Your next question might be who is rethinking short haul flying entirely.
One air mobility developer is working on electric aircraft that lift off vertically. It is spending heavily to build factories, secure certification and prepare commercial routes.
The same business is tying part of its future to autonomous systems and new propulsion. That depends on regulators and infrastructure that are still taking shape.
It is also stretching into defense work, software and passenger services. That wider scope could create more ways to earn, or more ways to stumble.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 66% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com