


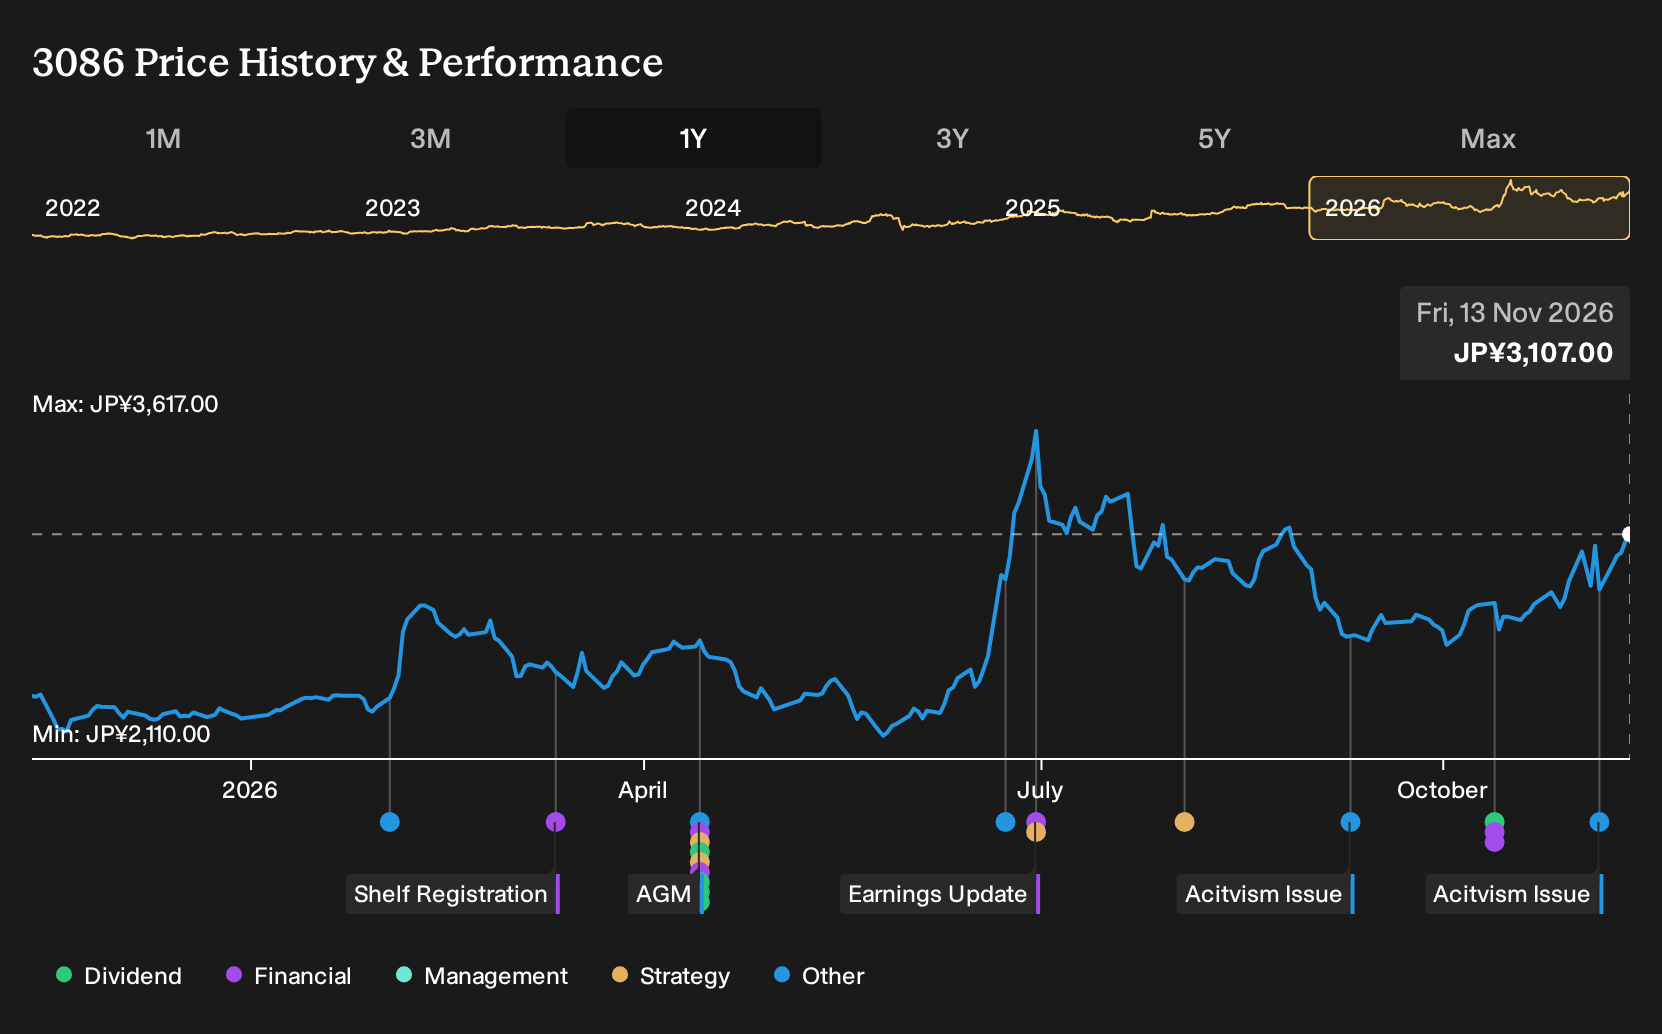
- On 6 November 2026, 3D Investment Partners increased its stake in J. Front Retailing to 13.84% and publicly outlined plans to work with management on portfolio optimization, capital allocation, asset use and capital policy.
- The activist investor is explicitly targeting what it views as low capital efficiency and an over-capitalized balance sheet, which directly intersects with J. Front Retailing's ongoing shift toward higher return projects, payments and content driven businesses.
- This development is reshaping J. Front Retailing's investment narrative as 3D Investment Partners takes a larger stake and emphasizes capital efficiency.
Scan other capital efficient plays facing similar balance sheet pressure by checking our hand picked 20 resilient stocks with low risk scores, which is aligned with the themes now in focus at J. Front Retailing.
J. Front Retailing Investment Narrative Recap
To stay invested in J. Front Retailing, you need to buy into a multi year shift away from pure department store reliance toward content, payments and developer earnings, while heavy renovations and upfront spending weigh on reported profitability. The analyst consensus Narrative on Simply Wall St expects earnings to grow 7.33% a year from this reset, but recent net margin compression and low current and forecast return on equity keep execution in the spotlight.
The sharpest short term swing factor remains how renovation related disruption and inbound luxury softness interact with rising structural costs and front loaded investments. 3D Investment Partners pushing on capital efficiency and balance sheet usage may influence payout and buyback decisions, yet it does not directly change operational risks around tourism demand, cost inflation or the pace at which newer content and payment businesses scale.
There have been no other major company announcements disclosed alongside this activist update. The engagement with 3D Investment Partners is therefore the key incremental data point around J. Front Retailing right now. Their focus on portfolio optimization, asset use and capital policy intersects with existing analyst concerns that the group is over capitalized and running low P/E justified returns compared with the broader JP Multiline Retail industry.
For you, the practical question is whether a more assertive capital discussion can coexist with a multi year capex and renovation cycle without squeezing flexibility. The business is already dealing with slower forecast revenue growth than the Japanese market, cost inflation and construction related earnings drag. Any shift in capital allocation that tightens the buffer for those risks, or alters the pace of buybacks and dividends, now sits firmly inside the short term catalyst set.
What the current J. Front Retailing forecasts assume
J. Front Retailing's current analyst storyline leans on relatively modest expansion rather than a big step change. Forecasts point to annual revenue growth of 2.6% over the next few years, with profit margins projected to move from 6.2% today to 7.5% by around 2029. On those assumptions, earnings are expected to reach ¥35.8 billion by the 2029 financial year, compared with earnings today of ¥27.5 billion, which is an increase of roughly ¥8.3 billion. The consensus view also anchors that outcome to a 2029 P/E of 20.6x, higher than the current JP Multiline Retail sector multiple of 14.6x and lower than J. Front Retailing's present 23.6x, and assumes the share count drifts down by about 1.39% a year as buybacks continue.
Those headline numbers frame the trade off that 3D Investment Partners is pushing on. The investor pressure is focused on capital efficiency at a time when analysts already build in higher margins and steady top line growth. Put differently, the existing model gives the business some credit for better profitability and slightly leaner equity. This means any activist driven shift in asset use, payouts or disposals needs to be weighed against forecasts that already bake in improvement rather than a static picture.
On the valuation side, the consensus price target sits at ¥2,465 per share, with individual analyst views spread between ¥2,000 and ¥2,800. That midpoint is about 7.9% below the current ¥2,660.5 price, which implies analysts as a group see the stock as roughly in line with their central scenario rather than obviously cheap or expensive. To line up with that stance, you would be assuming 2029 revenue of ¥476.0 billion, earnings of ¥35.8 billion and a 20.6x P/E, discounted back using a rate in the 8.4% range. The activist engagement does not rewrite those numbers overnight, but it does put more attention on whether the existing balance sheet and capital plans support or dilute that earnings path.
J. Front Retailing's narrative projects ¥476.0 billion in revenue and ¥35.8 billion in earnings by 2029. This builds on a 2.6% yearly revenue growth rate and an earnings increase of roughly ¥8.3 billion from current earnings of ¥27.5 billion.
Uncover why J. Front Retailing's fair value indicates a 21% potential downside to its current price, suggesting that the premium may not hold.
Exploring Other Perspectives
One alternate view focuses on J. Front Retailing's earnings path rather than capital efficiency. The most optimistic analysts were already pencilling in revenue of ¥501.3 billion and earnings of ¥38.3 billion by 2029, comfortably above the consensus track. You can now ask whether this activism accelerates that upbeat scenario or forces those projections to be revisited.
Explore another J. Front Retailing fair value estimate, including one that suggests it could be worth as much as ¥2465!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your J. Front Retailing research is our analysis highlighting 1 key reward that could impact your investment decision.
- See our latest analysis for J. Front Retailing. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate J. Front Retailing's overall financial health at a glance.
Looking for more investment ideas beyond J. Front Retailing?
If the J. Front Retailing story has sharpened your focus on capital efficiency, risk and payout discipline, it can be useful to line it up against peers facing very different pressures and balance sheet profiles using the Simply Wall St Screener.
- For investors who want potential upside without stretching risk tolerance too far, scan a curated set of resilient opportunities through our 20 resilient stocks with low risk scores.
- If value is your starting point, narrow in on companies combining quality fundamentals with prices that look more forgiving by checking the 19 high quality undervalued stocks.
- For income focused portfolios where cash flow and resilience matter, filter for payout candidates with stronger balance sheets using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com