


Why Imperial Brands’ upcoming results matter
Imperial Brands (LSE:IMB) is about to report full year results on 17 November, and the update will test whether recent pricing, market share gains and capital returns can continue to offset weaker cigarette volumes.
Recent trading has been mixed. The share price is up 6.8% over the past month and 13.7% over the last quarter, yet still sits lower year to date. At the same time, the 3 year total shareholder return of 95.96% and 5 year total shareholder return of 166.70% show how powerful reinvested dividends and buybacks have been for long term holders of Imperial Brands.
Scan how Imperial Brands stacks up on income and valuation against a hand picked 4 dividend fortresses that share a focus on hefty cash returns to shareholders.
After a strong run over the past quarter but a weaker year to date, the real puzzle now is whether to buy Imperial Brands on this rebound or wait for a cheaper entry as the valuation case unfolds next.
Most Popular Narrative: 7% Undervalued
On the analyst consensus Narrative on Simply Wall St, Imperial Brands has a fair value of £31.81 per share versus the last close at £29.67. This frames the upcoming results against a view that the market price sits below that valuation and puts execution squarely in focus.
The multi year factory and digital transformation program, including targeted annual savings of £320m by 2030, confirmed closures or exits of large facilities in Langenhagen and Taiwan and manufacturing excellence initiatives that are expected to deliver £25m of annual savings in FY26, is designed to lower the cost base and support adjusted operating profit margins.
See why 98 investors see Imperial Brands as 7% undervalued.
Result: Fair Value of £31.81 (UNDERVALUED)
Still, German excise tax hikes and tougher U.S. next generation product competition could both challenge Imperial Brands and force investors to rethink that undervalued narrative.
Find out about the key risks to this Imperial Brands narrative.
Another View: What Imperial Brands’ P/E Is Telling You
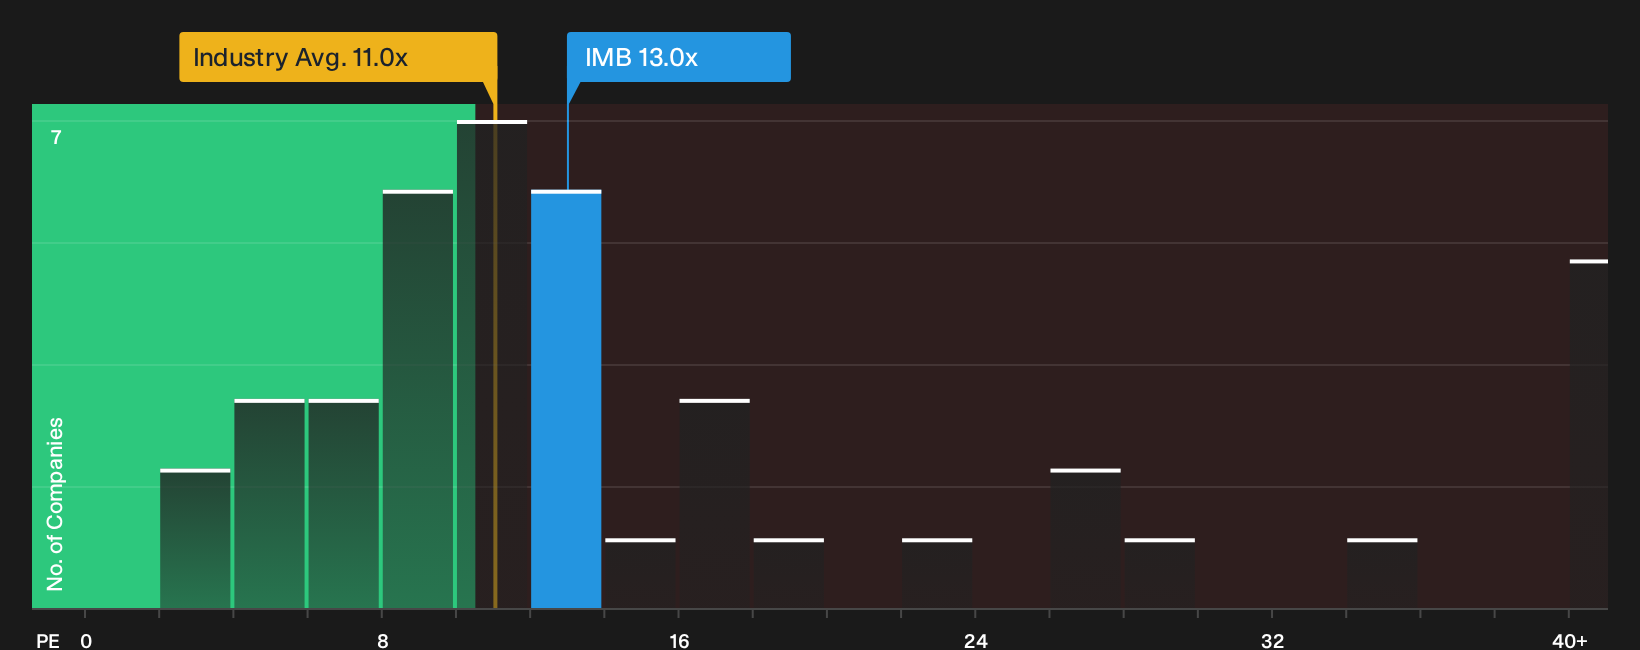
A different lens on Imperial Brands comes from the P/E ratio. The shares trade at 13x earnings, which is higher than the global tobacco group on 11x, but below peers on 20.6x and the fair ratio of 22.9x. That mix hints at both valuation risk and potential opportunity. Which side do you think matters more?
Our valuation breakdown unpacks how those P/E gaps could close over time and what that might mean for future returns compared with other tobacco stocks and the fair ratio the market could move towards, so it is worth reading See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
There are mixed views on Imperial Brands so far. If you want to form your own view, move quickly, consider both the potential upsides and pressure points, then weigh up the 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Imperial Brands?
If Imperial Brands has sharpened your focus on valuation and income, do not stop here. Broader ideas can help you build a stronger overall portfolio.
- Target steadier potential outcomes by scanning a basket of stocks with robust financial resilience using the 5 resilient stocks with low risk scores.
- Hunt for potential mispriced opportunities by reviewing a curated set of quality companies trading below what their fundamentals may justify through the 15 high quality undervalued stocks.
- Strengthen your core holdings by zeroing in on businesses that pair healthy balance sheets with sound fundamentals using the list of solid balance sheet and fundamentals (9 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com