


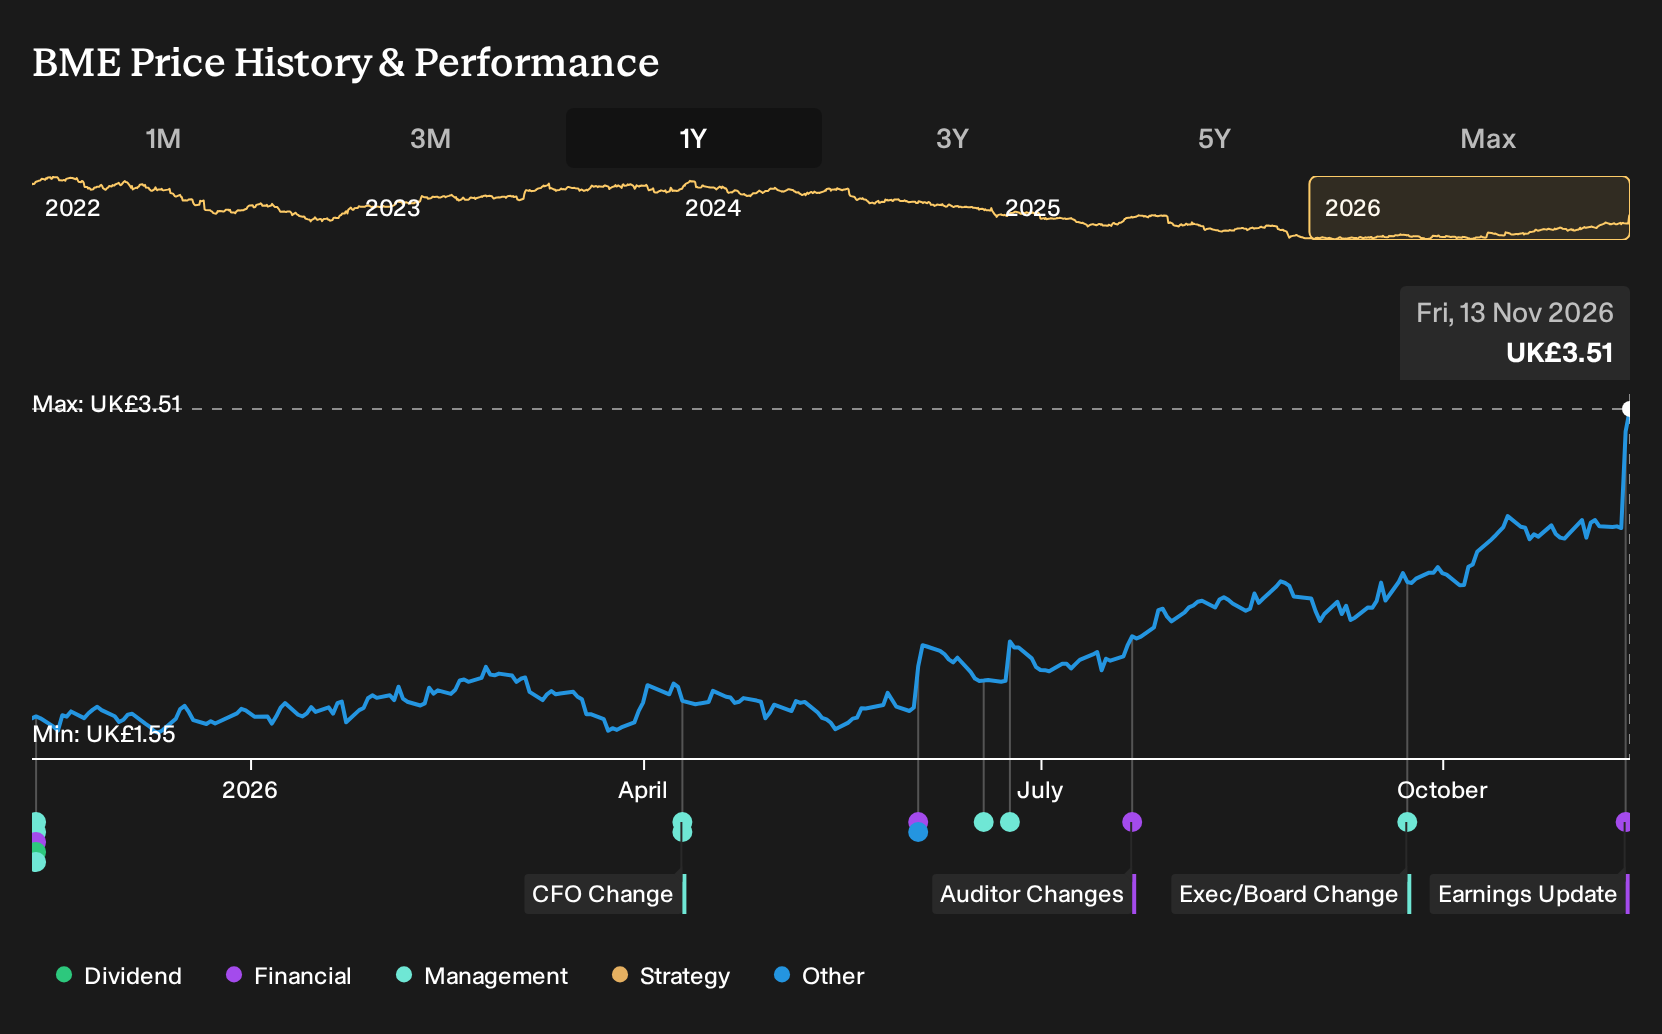
- B&M European Value Retail reported half year sales of £2,848 million and net income of £84 million, and guided for full year core profit to be at or slightly above market expectations.
- Improved UK like for like sales, a 94 basis point uplift in trading gross margin, and a strategy that prioritises refits over rapid store expansion highlight a shift toward efficiency and cash generation quality.
- We will now look at how B&M European Value Retail's higher full year profit guidance could reshape the company's broader investment narrative.
B&M European Value Retail Investment Narrative Recap
To own B&M European Value Retail, you need to believe it can keep turning its discount model into dependable cash while running a tighter UK estate. The upgraded full year profit guidance leans on better like for like trends and gross margin, so the key near term catalyst remains execution on refits and merchandising across the wider store base.
The biggest operational risk sits around cost pressure and debt, given interest payments are not well covered by earnings. If wage, rent or supply chain expenses increase further, that could squeeze cash generation just as management is trying to prove this new, slower expansion phase can still support the balance sheet.
The half year 2027 results, with sales of £2,848 million and net income of £84 million, are central to the current B&M European Value Retail story. Profit guidance in line with or slightly above market expectations places more emphasis on management’s claim that the refit first approach can support margins, even with fewer UK openings planned.
According to Zer0, an investor in the Simply Wall St Community, insider buying from the CEO and other directors has been a key part of the thesis. Zer0 highlights sizeable director purchases over the past two years, which may sharpen attention on execution of the profit upgrade and on whether earnings growth near the forecast 9% a year actually occurs.
Zer0’s narrative lands on a fair value of £1.50 per share for B&M European Value Retail, based on revenue rising 4.1% a year and future profit margins reaching 2.8%, which together are used to frame what they see as a reasonable earnings power for the business.
Uncover why B&M European Value Retail's fair value indicates a 57% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One big disagreement sits around margins. The most bearish analysts already expected B&M European Value Retail to reach only about £6.4b of revenue and £239.9m of earnings by roughly 2029, and to trade on a much lower 8.4x P/E. That paints a far more cautious story than today’s upbeat guidance, so it is worth comparing both views yourself.
Explore 5 other B&M European Value Retail fair value estimates, including one that suggests as much as 60% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your B&M European Value Retail research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for B&M European Value Retail. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate B&M European Value Retail's overall financial health at a glance.
Looking for more investment ideas beyond B&M European Value Retail?
If the B&M European Value Retail story has sharpened your thinking on risk, cash generation and expectations, it can help to set it alongside other businesses with different profiles. The Simply Wall St screener lets you quickly filter for traits that match how you like to invest, so you can build a shortlist that fits your own return and risk preferences.
- For investors who want income to do more of the heavy lifting, consider stocks in our hand picked set of 4 dividend fortresses that may appeal if you focus on yield and resilience.
- If capital preservation matters most to you, narrow the field to companies in the 5 resilient stocks with low risk scores and compare how their balance sheets and volatility profiles line up with your comfort level.
- When you are hunting for under followed ideas, broaden your watchlist with the 6 high quality undiscovered gems that pair strong fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com