


Power Corporation of Canada (TSX:POW) just released third quarter results that showed net income of CA$1,024 million versus CA$716 million a year earlier, catching the market’s attention and putting recent share performance under a brighter spotlight.
That earnings jump comes on top of a strong run in the stock, with Power Corporation of Canada’s share price up 30.54% year to date and the latest close at CA$93.9. The 1 year total shareholder return of 39.34% points to momentum that has been building for several years, reflected in very large 3 year and 5 year total shareholder returns of roughly 3x the starting value.
Capitalize on Power Corporation of Canada’s earnings momentum by scanning a curated 9 high quality undiscovered gems that share similar financial strength but are still flying under most investors’ radar.Bulls point to Power Corporation of Canada’s earnings jump and long run of strong total returns. Bears focus on how much has already been priced in. Which case does the current valuation support?
Price-to-Earnings of 20x: Is it justified?
Power Corporation of Canada’s valuation is no longer cheap on headline numbers. The stock trades on a P/E of 20x at a last close of CA$93.9, which sits above both the North American insurance industry average of 11.7x and its direct peer group at 18.9x.
The P/E ratio compares what investors are paying today for each dollar of current earnings. For a diversified financial group like Power Corporation of Canada, which spans life insurance, asset management, and alternative investments across Canada, the United States, and Europe, this metric gives a quick read on how the market is weighing its earnings power.
This richer multiple suggests buyers are willing to pay a premium for the group’s earnings profile relative to many insurers. The market is assigning a P/E of 20x even though recent net profit margins sit at 7.1%, below last year’s 8.1%, and five year earnings growth has been a modest 1% per year, which points to a full valuation rather than a clear bargain.
Compared with the North American insurance sector at 11.7x, Power Corporation of Canada trades on a significantly higher earnings multiple. The stock is also priced above its peer average P/E of 18.9x and above an estimated fair P/E of 15.4x. This is a level the market could eventually move towards if sentiment cools.
Explore the SWS fair ratio for Power Corporation of Canada.
Result: Price-to-Earnings of 20x (OVERVALUED)
Still, the recent share price run, combined with a P/E well above the broader insurance group, leaves Power Corporation of Canada exposed if earnings momentum cools or sentiment reverses.
Find out about the key risks to this Power Corporation of Canada narrative.
Another View on Power Corporation of Canada’s Value
Our DCF model points to a fair value of CA$92.31 per share for Power Corporation of Canada, slightly below the current CA$93.9 price, which suggests the stock screens as modestly overvalued on cash flow grounds rather than outright cheap. If earnings momentum cools, does the margin of safety feel tight to you?
Look into how the SWS DCF model arrives at its fair value.
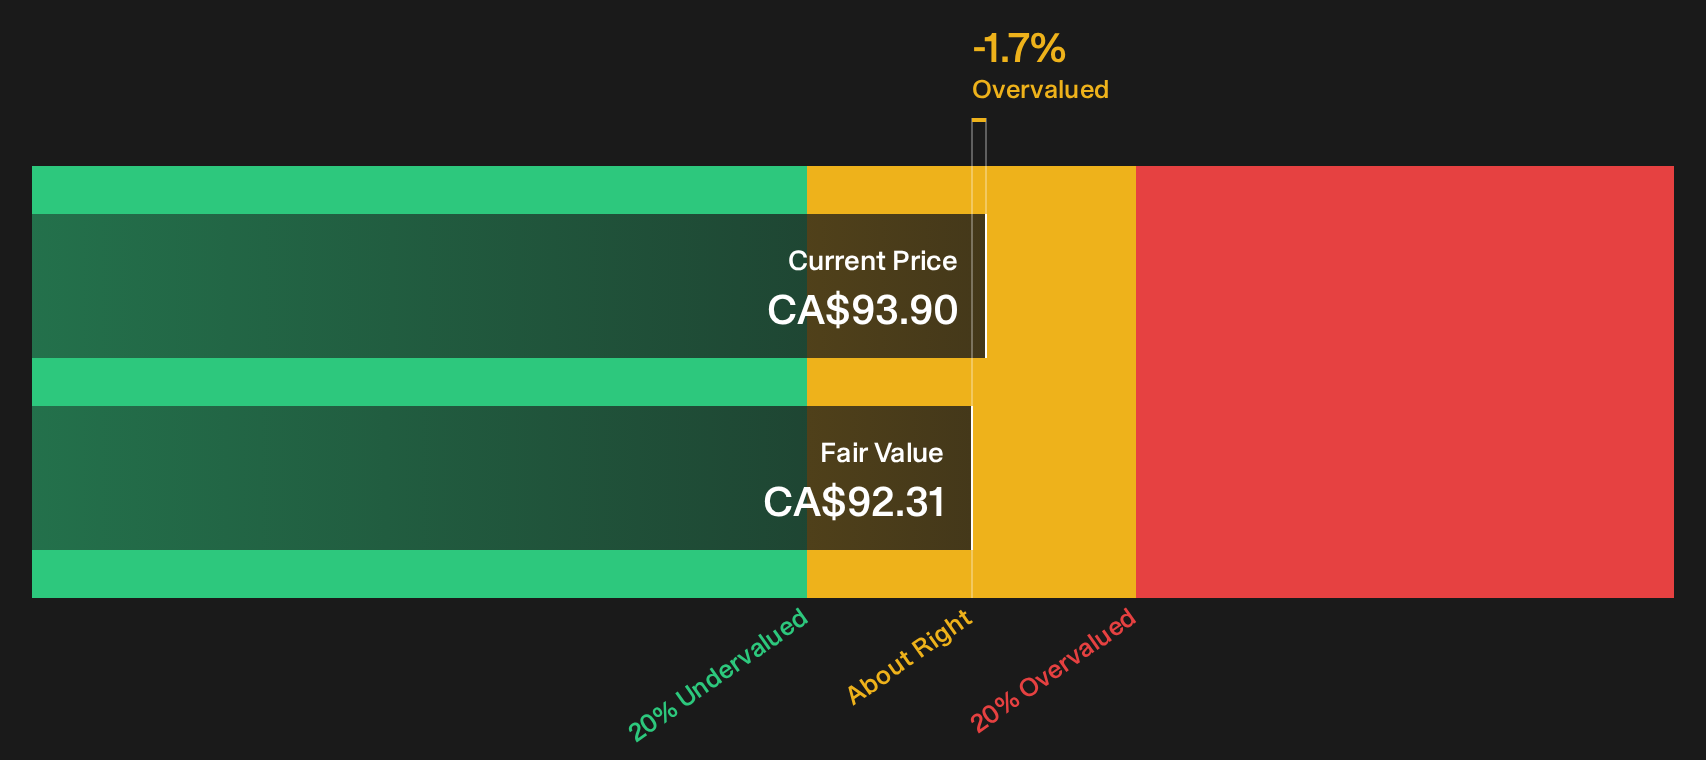
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Power Corporation of Canada for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Power Corporation of Canada is clearly split, with strong recent returns pulling one way and valuation concerns tugging the other. Act quickly, review the key data for yourself, and weigh both the upside and the pressure points highlighted by the 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Power Corporation of Canada?
If valuation questions around Power Corporation of Canada have you thinking about your next move, this can be a useful moment to widen your watchlist and upgrade your opportunity set.
- Target potential mispricings by scanning a focused list of 6 high quality undervalued stocks that pair stronger fundamentals with more modest expectations.
- Build a portfolio with staying power by reviewing a curated list of solid balance sheet and fundamentals (6 results) that can better handle financial shocks.
- Dial back portfolio stress and concentrate on resilience by zeroing in on a 9 resilient stocks with low risk scores that filters for more stable profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com