


Q3 earnings beat sets the tone for Landstar System
Landstar System (LSTR) kicked off its latest chapter with third quarter earnings that topped expectations, helped by firmer truck pricing and heavier freight volumes, even as higher insurance and claims costs pressed on profitability.
The transportation group also leaned into shareholder returns through a regular dividend and buybacks, while analysts flagged softer freight demand, rising truck capacity, and ongoing driver shortages as reasons for a more cautious stance.
Recent trading has been choppy. Landstar System’s share price has fallen 11.6% over the past month and 21.3% over the last quarter, even though the year-to-date share price return is slightly positive and the 1-year total shareholder return of 21.8% suggests that longer term holders are still ahead.
Spot opportunities beyond Landstar System by scanning a curated 32 high quality undervalued stocks that combine resilient cash flows with balance sheets built to handle choppy freight cycles.After a sharp pullback, but with earnings, cash returns and a flagged valuation gap all in play for Landstar System, does the current price still tip the risk reward balance toward buyers or toward patience?
Most Popular Narrative: 17% Undervalued
On the analyst consensus Narrative on Simply Wall St, Landstar System screens as undervalued, with a fair value of $181.13 against the last close of $149.68. That gap sits on top of a model that leans heavily on revenue growth and margin repair over time.
The current valuation, with the stock trading on a forward P/E in the low to high 30s after recent declines in revenue and EPS, implies the market is already pricing in meaningful future benefits from heavy haul growth, AI driven efficiency and Landstar System’s safety focused network.
See why 1 investors see Landstar System as 17% undervalued.
Result: Fair Value of $181.13 (UNDERVALUED)
Still, the bullish story around Landstar System only holds if insurance and claims expenses stop surprising to the upside and if AI spending actually feeds through to productivity and margin gains.
Find out about the key risks to this Landstar System narrative.
Another View on Landstar System’s Valuation
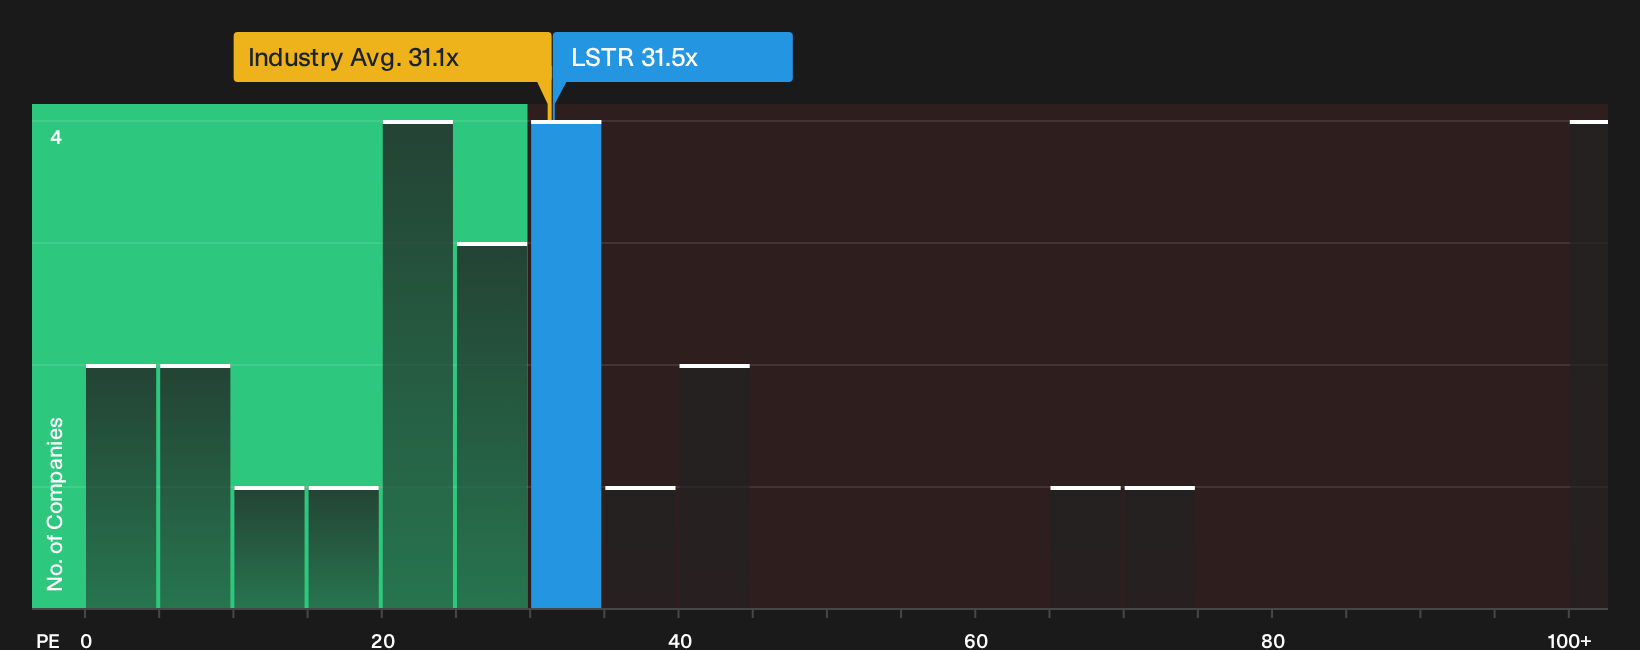
On simple earnings multiples, Landstar System looks less clear cut. The stock trades on a P/E of 31.5x, slightly above the US Transportation industry at 31.1x, and well above a fair ratio of 18x that the market could eventually lean toward.
Peers on average change hands at 60.3x earnings, which makes Landstar System look cheaper than direct comparables but still expensive against that fair ratio anchor. For anyone weighing the DCF upside against this richer multiple, which signal feels more important to your process right now: the cash flow gap or the earnings-based risk of de rating?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this all sounds conflicted, that is because the Landstar System story mixes clear rewards with live risks and moving pieces. Spend a few minutes with the underlying charts, forecasts and quality checks. Then decide whether those positives matter most by reviewing the 3 key rewards.
Looking for more investment ideas beyond Landstar System?
Landstar System may be on your radar already, but the real edge often comes from lining it up against a few carefully chosen alternatives.
- Target resilience by scanning companies with steady balance sheets and solid fundamentals through a curated list of solid balance sheet and fundamentals (24 results).
- Hunt for value by comparing Landstar System with a broader pool of potentially mispriced opportunities using our focused 32 high quality undervalued stocks.
- Build a smoother ride for your portfolio by zeroing in on income ideas with staying power via a hand picked 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com