


Record earnings update shifts attention to CECO Environmental
CECO Environmental (CECO) has drawn fresh attention after reporting record third quarter 2026 revenue of US$404.43 million, alongside a quarterly net loss and a sharply higher full year 2027 sales outlook.
The fresh guidance and record update have come alongside a sharp move in CECO Environmental’s share price, with a 1 day share price return of 4.67% and a 7 day share price return of 28.12%. However, the 90 day share price return is down 29.64% and the 30 day share price return is down 10.24%, while the 1 year total shareholder return is 13.15% and the 5 year total shareholder return is more than 7x. This suggests that recent momentum has picked up again after a weaker stretch.
Scan how CECO Environmental compares with other industrial players showing sharp moves and upgraded outlooks by reviewing the hand picked 32 high quality undervalued stocks in this corner of the market.
Bulls point to CECO Environmental’s record top line and upgraded 2027 outlook, while bears focus on the recent losses and volatile share path. Which story does the current valuation lean toward?
Most Popular Narrative: 53% Undervalued
On the analyst consensus Narrative on Simply Wall St, CECO Environmental carries an estimated fair value of about $119.57 against a last close of $56. The gap frames CECO as materially undervalued in that model, which is built on detailed revenue and earnings forecasts.
Backlog that has grown for 12 consecutive quarters to more than $1.8 billion and a sales pipeline that has expanded from about $1.5 billion in 2021 to over $8.5 billion by Q2 2026 give CECO Environmental a wide set of identified opportunities that can feed future revenue and provide potential operating leverage.
See why 12 investors see CECO Environmental as 53% undervalued.
Analysts in that framework apply an 8.74% discount rate to those projected cash flows and arrive at a fair value that is more than double the current share price. The view implies that the current market price does not fully capture the record backlog, the 2027 guidance range of $2.1b to $2.3b, or the planned Thermon synergies that underpin the forecasts.
The same Narrative flags risks around leverage, reliance on large power and gas projects, and delayed industrial water work in the Middle East, which could affect how much of the current pipeline turns into revenue and profit. Anyone using this valuation still needs to judge for themselves whether those execution and funding risks are adequately reflected in a fair value of roughly $120.
Result: Fair Value of $119.57 (UNDERVALUED)
Still, the CECO Environmental story could change quickly if large power and gas projects slow, or if higher leverage squeezes future profitability and cash generation.
Find out about the key risks to this CECO Environmental narrative.
Another View: CECO Environmental Looks Pricey On Sales
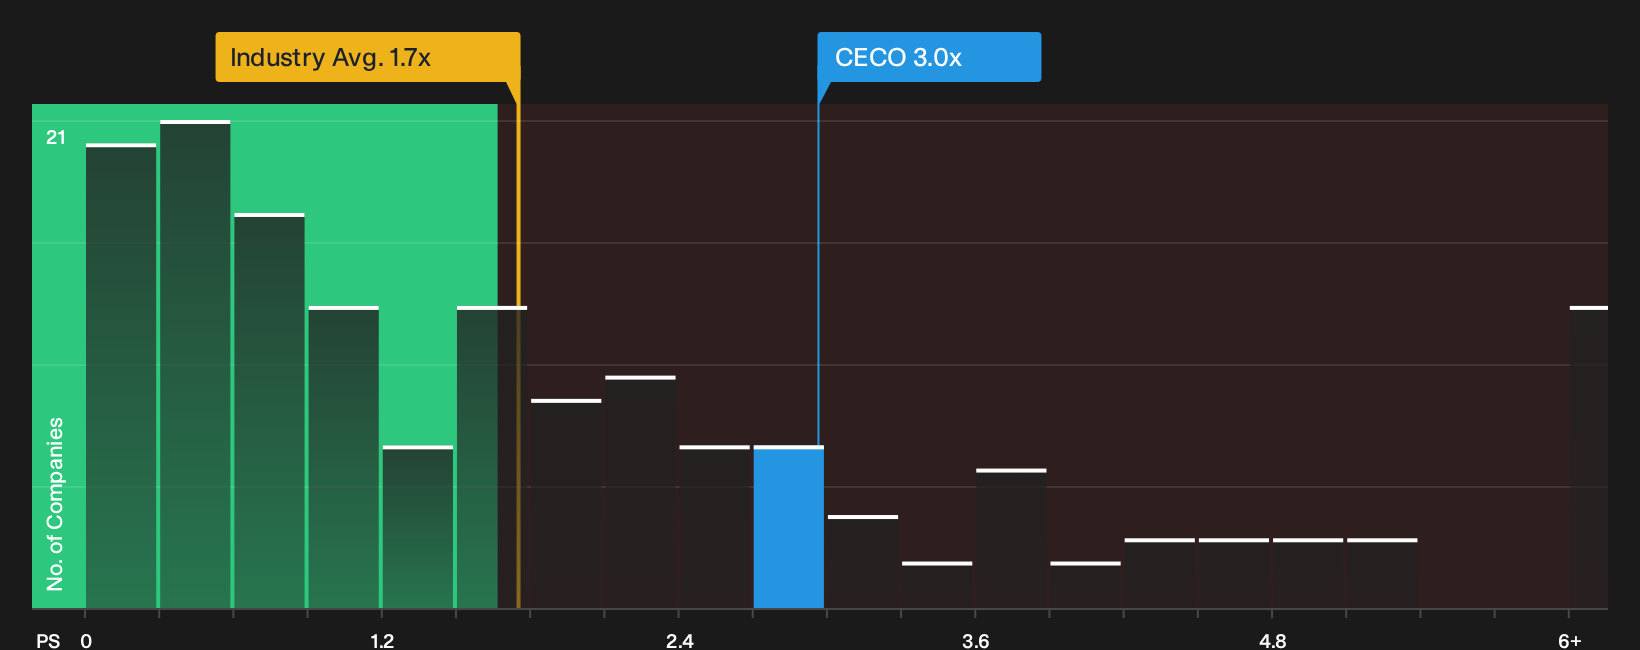
There is a twist when the focus shifts from cash flows to simple sales multiples. CECO Environmental trades on a P/S of 3x, compared with 1.8x for the wider US Machinery group and a fair ratio of 4.8x that the market could eventually move toward.
That mix means the stock screens more expensive than peers on today’s revenue, yet still below the fair ratio implied by regression work. Is that a margin of safety or a warning that expectations already run high?
To see how the numbers stack up using this lens, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around CECO Environmental can feel confusing, so move quickly to review the full picture, weigh the concerns and upside, and decide where you stand with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond CECO Environmental?
If CECO Environmental has sharpened your focus, do not stop here. Broaden your watchlist with other focused ideas that fit different risk and income goals.
- Target fresh opportunities in smaller companies that already show solid financial traits by reviewing the 13 elite penny stocks with strong financials.
- Pursue quality at a sensible price with companies that combine strong fundamentals and appealing valuations by scanning the 20 high quality undiscovered gems.
- Prioritise resilience and focus on stability by checking companies that score well on risk in the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com