


- In early November 2026, National University Health System signed a Memorandum of Understanding with Singtel and Telefonaktiebolaget LM Ericsson. At the same time, Verizon, AT&T and other partners expanded collaborations around AI driven network automation, satellite connectivity and Ericsson's new ISAC sensing system.
- These partnerships push Ericsson deeper into higher value uses of 5G, 5G Advanced and early 6G across healthcare, defense, public safety and autonomous networks. This is relevant for how its Networks and Enterprise activities might evolve operationally.
- We will look at how Ericsson's 5G Advanced healthcare initiative through the National University XG AI Centre fits into the existing investment narrative.
Scan beyond Telefonaktiebolaget LM Ericsson and explore other connectivity and AI infrastructure plays that could benefit from similar tailwinds with our hand picked 53 AI infrastructure stocks.
Telefonaktiebolaget LM Ericsson Investment Narrative Recap
To own Telefonaktiebolaget LM Ericsson, you need to be comfortable with a relatively steady top line, earnings that the analyst consensus Narrative on Simply Wall St expects to grow slowly, and a story that leans on margins and cash conversion rather than rapid expansion. In the short term, a key swing factor is whether Networks and Cloud Software and Services can hold gross margin levels while telecom operator spending stays cautious.
The biggest risk remains pressure on profitability if component costs rise faster than Ericsson can reprice contracts or redesign equipment, together with the Enterprise segment staying loss making. The new healthcare, satellite and sensing projects look more like early proof points than near term drivers, so the direct financial impact may be limited for now.
The National University XG AI Centre partnership is the clearest operational link to the recent healthcare news. It concentrates Ericsson’s 5G Advanced and early 6G research into a real hospital setting, which matters for the narrative around AI powered connectivity and edge compute that could support future demand for advanced radio and core equipment.
For you as an investor, the interest lies in execution. If Ericsson can turn this healthcare testbed into repeatable network and software offerings, it connects directly to catalysts around differentiated enterprise connectivity and private networks. However, there is still a risk that Enterprise remains subscale or slow to reach breakeven if customer adoption lags behind the technical progress.
Telefonaktiebolaget LM Ericsson is modeled to reach revenues of SEK233.5b and earnings of SEK20.6b by 2029, based on analyst assumptions that top line performance stays fairly flat and that earnings rise from SEK19.3b today. This implies an increase of about SEK1.3b over that period.
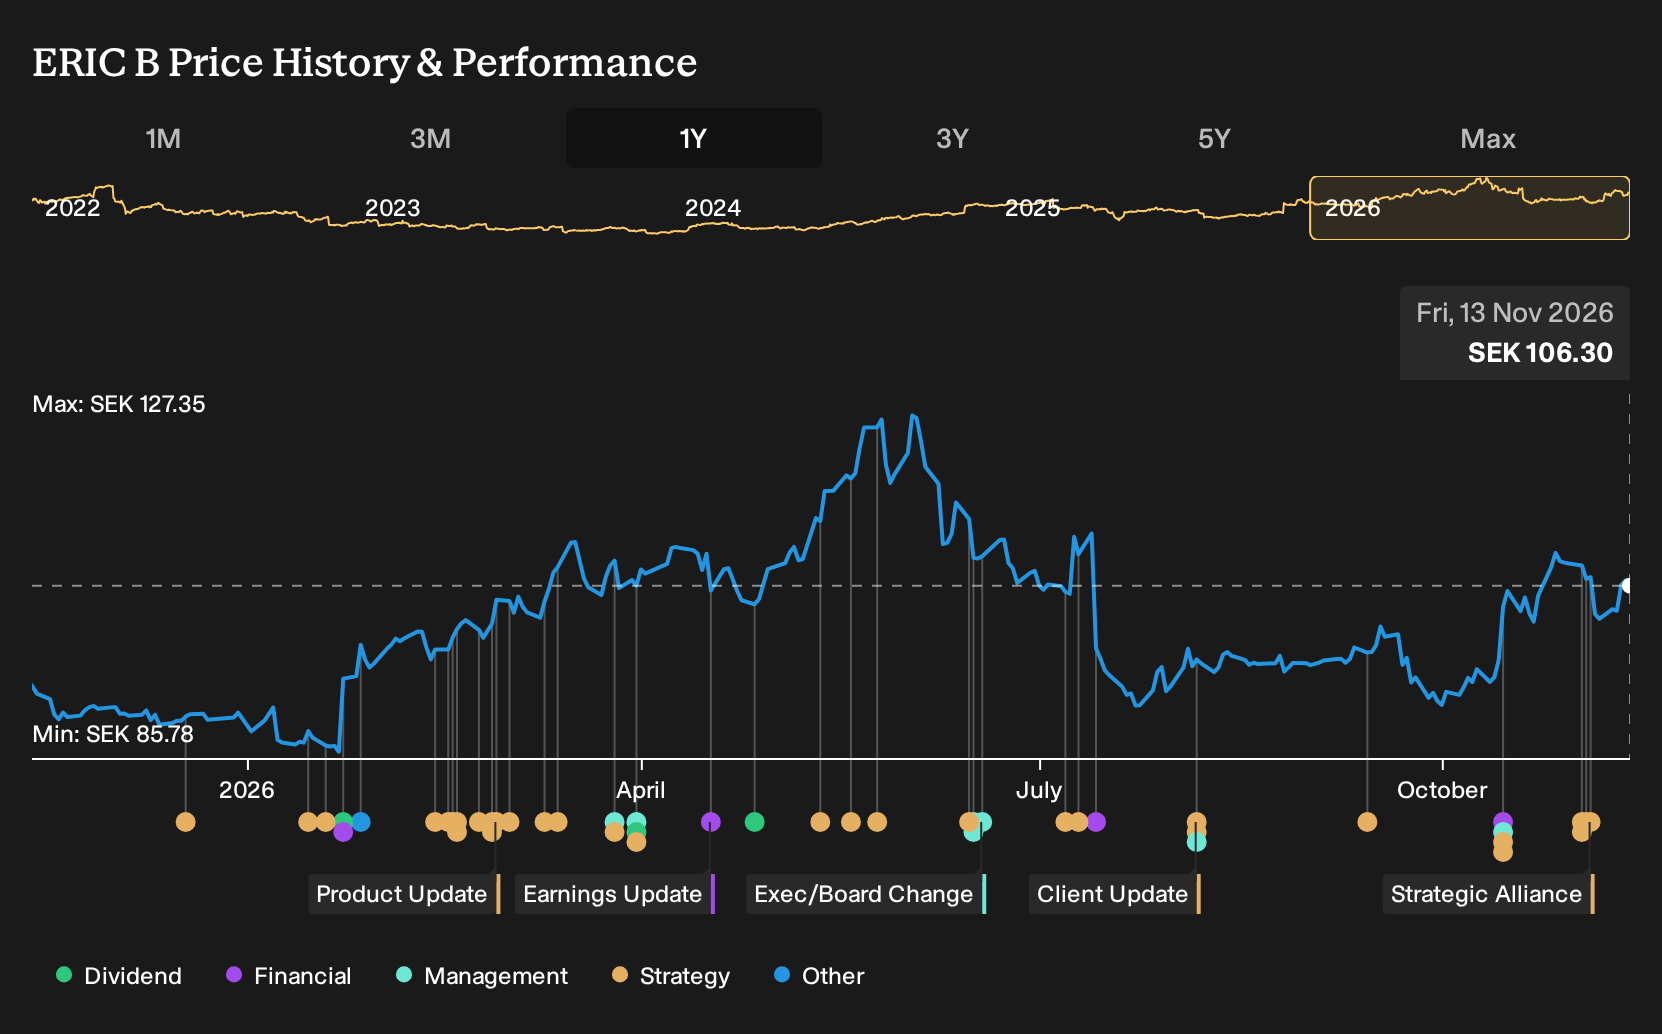
Uncover why Telefonaktiebolaget LM Ericsson's fair value indicates a 6% potential downside to its current price, suggesting that its valuation premium may not hold.
Exploring Other Perspectives
One alternate view focuses on margin risk rather than the healthcare upside. The most cautious Ericsson analysts had been working off earnings of about SEK16.8b by 2029 on roughly SEK228.4b of sales, well below the consensus path. Your own view may change as these new healthcare and AI partnerships are incorporated into future models.
Explore 4 other Telefonaktiebolaget LM Ericsson fair value estimates, including one that suggests as much as 31% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Telefonaktiebolaget LM Ericsson research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Telefonaktiebolaget LM Ericsson. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Telefonaktiebolaget LM Ericsson's overall financial health at a glance.
Looking for more Telefonaktiebolaget LM Ericsson style investment ideas?
If the Ericsson story around connectivity, AI and resilient cash generation resonates with you, it can help to line it up against other opportunities with different risk and reward profiles. The Simply Wall St Screener lets you quickly narrow the universe to stocks that better match your goals on value, income or resilience.
- If you want potential mispricing on your side, start with high quality businesses trading on what looks like a discount by checking out 197 high quality undervalued stocks.
- If income matters more to you than excitement, focus on reliable payers that combine sturdy operations with meaningful yields through our 220 dividend fortresses.
- If capital preservation is near the top of your list, concentrate on companies with sturdier balance sheets and lower risk profiles using the 210 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com