


PDF Solutions (PDFS) drew fresh attention on 5 November 2026 after reaffirming its full year target of 20% annual revenue growth and reporting third quarter and nine month results showing higher sales and net income versus a year earlier.
Even with the reaffirmed 20% revenue growth goal and stronger earnings, PDF Solutions’ recent momentum has cooled, with the share price down 9.0% over the last day and 27.4% over 3 months. However, it is still showing a year to date share price gain of 25.1% and a 1 year total shareholder return of 47.3%, which points to longer term holders remaining well ahead despite the recent pullback.
Scan for other semiconductor and factory software plays that show similar earnings traction and guidance strength by using our curated list of 42 profitable AI stocks that aren't just burning cash.
PDF Solutions now pairs accelerating financials with a sharp pullback in the share price. This reset may leave more upside potential than downside risk as valuation comes under closer scrutiny next.
Most Popular Narrative: 34% Undervalued
PDF Solutions closed at $36.98 while the analyst consensus Narrative on Simply Wall St anchors fair value at $56.25. This frames a sizable valuation gap that analysts connect directly to the business model and its data platform ambitions.
The shift toward a higher mix of recurring and subscription based revenue, highlighted by US$205.1m of recurring revenue in 2025 and a backlog of US$271m that excludes future runtime and gainshare, indicates a larger base of future contracted revenue that can support operating leverage and steadier earnings.
See why 14 investors see PDF Solutions as 34% undervalued.
Result: Fair Value of $56.25 (UNDERVALUED)
Still, the bullish PDF Solutions narrative could be challenged if heavy R&D and CapEx pressure free cash flow, or if volume based gainshare stays inconsistent.
Find out about the key risks to this PDF Solutions narrative.
Another View: PDF Solutions On Earnings Multiples
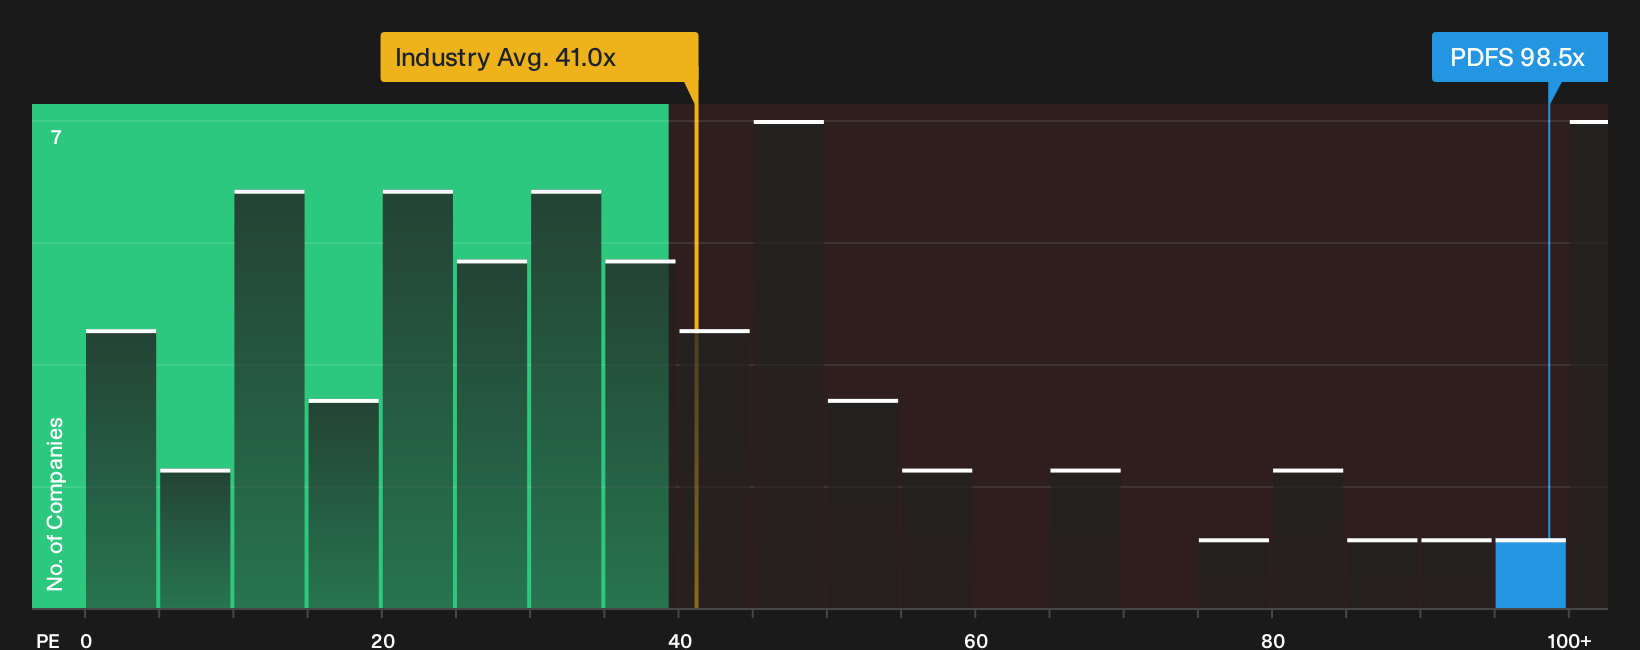
The undervalued fair value of $56.25 appears to conflict with what earnings multiples indicate for PDF Solutions. The stock trades on a P/E of 98.5x, compared with 41x for the US Semiconductor industry and 67.4x for peers, while the fair ratio is 38.8x. That kind of gap places more valuation risk on each dollar of earnings. Which signal do you trust more right now?
To stress test this richer pricing against the earnings profile, take a closer look at how the current P/E compares with the fair ratio and sector range in our valuation breakdown, powered by See what the numbers say about this price — find out in our valuation breakdown..
Use the visual comparison of PDF Solutions’ P/E against its industry as another reference point on how much optimism may already be reflected in the share price
Next Steps
Mixed messages on value and risk can be useful if you let them sharpen your own thinking, so move quickly, test the numbers, and weigh both sides using 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond PDF Solutions?
If PDF Solutions has sharpened your thinking on value and risk, do not stop here. A broader watchlist can help identify opportunities that this pullback might not reveal.
- Target resilient performers that prioritise capital strength by scanning our list of solid balance sheet and fundamentals (24 results).
- Hunt for quality at a reasonable price by reviewing the 32 high quality undervalued stocks before the crowd pays attention.
- Spot potential leaders early by checking the 20 high quality undiscovered gems that combine strong fundamentals with lower profile coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com