


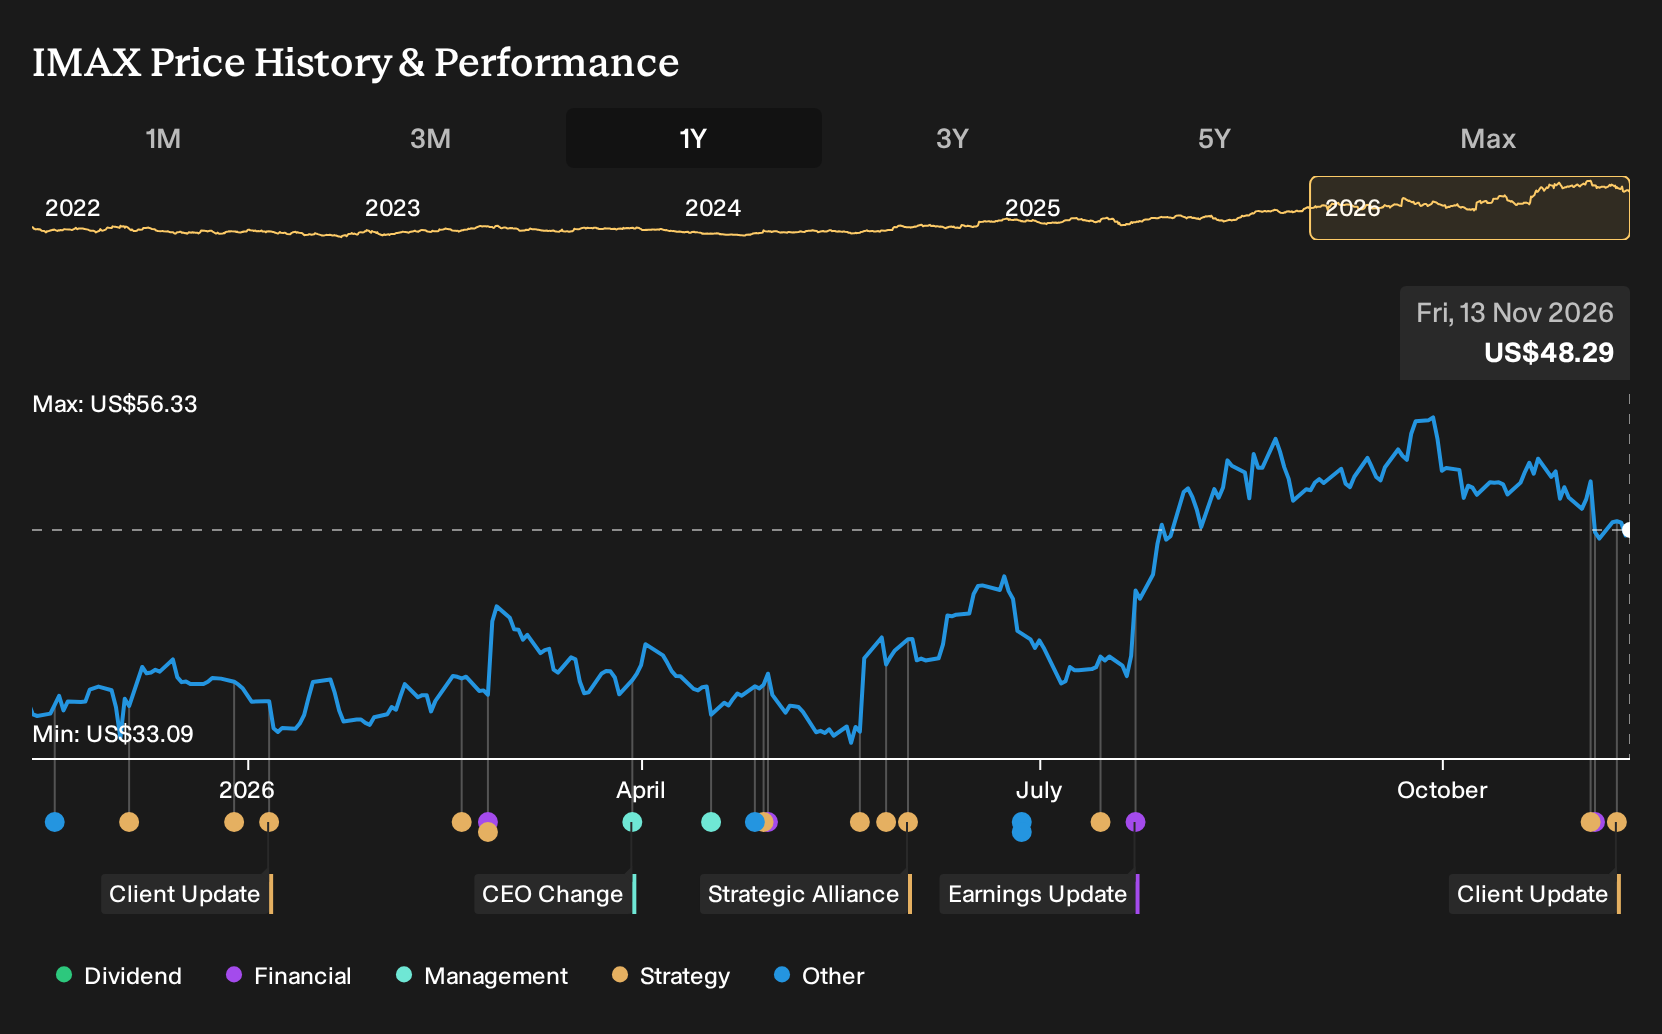
- IMAX Corporation reported third quarter 2026 revenue of US$174.55 million and net income of US$113.81 million, then announced an agreement to make Meta’s upcoming VR glasses the first IMAX Enhanced certified VR device, with a dedicated IMAX app planned for spring 2027.
- The Meta VR partnership extends IMAX Enhanced beyond TVs into headsets, which could deepen at home engagement and complement its cinema focused earnings profile.
- We will explore how IMAX's investment narrative aligns with this Meta VR Enhanced device deal and what it may signal for future monetisation.
Scan beyond IMAX and this Meta VR deal by comparing it with other media and tech players that screen well on our 20 high quality undiscovered gems list of potential under the radar opportunities.
IMAX Investment Narrative Recap
To own IMAX, you need to be comfortable with a premium format business that still leans heavily on theatrical box office while testing higher margin extensions such as IMAX Enhanced devices. The analyst consensus Narrative on Simply Wall St assumes the firm keeps converting its screen opportunity and content pipeline into solid cash generation. At present, the core near term swing factor is how a softer movie slate interacts with that high operating leverage.
The biggest operational risk remains concentration in blockbuster releases and any drag on cinema attendance from at home habits such as streaming or gaming. The Meta VR agreement is directionally relevant for at home engagement, but it does not change that near term dependence on tentpole releases or the exposure to an industry box office forecast that was cut by 11% for 2026.
The Meta VR glasses partnership appears most relevant when set against IMAX’s push into IMAX Enhanced devices that analysts already flag as a potential higher margin stream. It extends the existing ecosystem of certified TVs and streaming partners into headsets, which could gradually broaden where and how viewers experience IMAX formatted content beyond multiplexes.
As a potential catalyst, the deal gives IMAX another way to monetise its technology and content mastering across both cinema and home style environments, while still tying back to the same premium branding filmmakers use in theatres. Execution risk lies in content depth, user adoption of the new app, and ensuring this VR effort complements rather than cannibalises the box office driven network that underpins current earnings power.
IMAX's narrative projects US$520.6 million revenue and US$104.5 million earnings by 2029. This assumes 7.8% yearly revenue growth and requires earnings to rise by about US$63.6 million from US$40.9 million today.
Uncover why IMAX's fair value indicates a 23% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view sees the Meta VR glasses deal as a risk rather than a bonus. You might worry that at home IMAX experiences slowly chip away at cinema appeal. The most cautious analysts already framed that concern, even while still pencilling in revenue of about US$531.7 million and earnings of roughly US$113.5 million by 2029. Those numbers came before this announcement, so opinions on IMAX may move around as investors reassess how much value this VR push really adds.
Explore 2 other IMAX fair value estimates, including one that suggests it could be worth just $59.17!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your IMAX research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for IMAX. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate IMAX's overall financial health at a glance.
Looking for more IMAX style investment ideas?
If this IMAX and Meta VR story has you thinking about where else premium niches or under followed opportunities might exist, the Simply Wall St Screener can help you cast the net wider in a structured way.
- If you care most about financial resilience and clean balance sheets, start with companies that pass our list of solid balance sheet and fundamentals (24 results) and then compare how their fundamentals stack up against IMAX.
- For investors hunting for mispriced quality, focus on businesses that appear to trade below their estimated worth through our 32 high quality undervalued stocks and see which stories look more compelling than IMAX at today’s prices.
- Income focused readers who want cash returns as well as potential capital gains can review our 6 dividend fortresses and benchmark those yields and payout profiles against what IMAX currently offers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com